

1. Introduction to securitisation
2. Risk analysis and pricing of securitisations
3. Regulation of securitisations
4. Practical exercise 1: PURA RTS
5. Role of the ratings agencies
6. Liquidity of securitisations
7. Market drivers and motives for using securitizations
8. Practical exercise 2: Optimal Tranching
Analytics, software, proprietary algorithms, tools and quantitative models
Risk Control is a software and analytics company based in London. Founded in 2000, Risk Control is led by William Perraudin, Adjunct Professor and former Chair of Finance at Imperial College London, specialising in the field of risk
Risk Control staff include highly qualified financial and software engineers, specialised in implementing solutions for large financial firms
• We build bespoke high performance JEE solutions for our clients
• We are expert in valuation and risk modelling
• We have implemented financial planning software for multiple institutions
• We deliver robust, transparent, well-documented solutions
Risk Control works with regulators, central banks and commercial firms on data, risk and valuation issues
Objectives:
• Risk Control aims to increase transparency within our client’s business environments and assist them in reducing the likelihood and cost of potential adverse events
• To achieve these objectives, Risk Control deploys multi-disciplinary teams of finance specialists, software engineers and statistical and mathematical modellers
• Our analyses of financial risk and liquidity have shaped the thinking of regulators and industry participants
1. Introduction to securitisation
2. Risk analysis and pricing of securitisations
3. Regulation of securitisations
4. Practical exercise 1:PURA RTS
5. Role of the ratings agencies
6. Liquidity of securitisations
7. Market drivers and motives for using securitizations
8. Practical exercise 2: Optimal Tranching
• A securitisation is created when • The terms of the note issues are such that if the
1. A financial institution (e.g., a bank) income on the asset pool becomes too small to pay sells a pool of risky assets into a all the contractual coupons, the coupons will be bankruptcy-remote legal entity called a reduced but without the SPV being considered Special Purpose Vehicle. (Often, SPVs insolvent. are established as trusts.) • The liabilities of the SPV have a range of
2. (Alternatively, a manager can create a seniorities. securitisation by forming a fund for • In a typical transaction, the par value of the senior bonds via an SPV financed by issuing class of liabilities might make up 80% of the value notes.) of the underlying asset pool.
3. The SPV funds its acquisition of the • Often, there are several so-called mezzanine classes assets by issuing liabilities, generally of securities with successively lower seniorities. notes (or bonds), to the market. • Each class of liabilities is collectively called a tranche.
• In each period, income to the SPV is used to pay the coupons due to the different note holders starting with the most senior tranche.
• If at the maturity of the structure, the net reinvested income on the assets exceeds the amounts needed to repay the notes, the proceeds are paid to the holder of the so-called equity tranche.
• The detailed rules governing the way income to the SPV is split up and directed to holders of debt of different seniorities is called the “cash flow waterfall”.
Securitisations
Funded Synthetic
ABS MBO CDO
Bilateral Index
Balance Autos Student CMBS RMBS Arbitrage Sheet etc loans
Cash Market Cash Flow Value Flow
S 0% Risk Synthetic CDO Weight Asset £98
Investing Interest & Principal
Originating CDS OECD CDS SPV Interest L A Bank Premium Bank Premium is CDS & Principal Note Loan is CDS is CDS Seller Rated Collateral Buyer Seller with AAA £100 with with OECD £98 OECD Originator Bank @ Bank Credit and CDS Credit Funding libor + Protection Buyer Protection s(AAA) V = Equity with SPV £2
• The crisis started as a localised problem of higher than anticipated default rates in US sub-prime mortgages.
• These mortgages had been parcelled up and sold to banks round the world through RMBS and CDO. Confidence in valuations of these opaque transactions collapsed in the summer of 2007.
• The ratings agencies which had acted as experts in this market lost all credibility.
• Banks started to distrust their counter-parties because each bank knew that other banks could not value their books so anyone could be insolvent.
• Any bank with a business model requiring liquidity was in trouble.
Source: Understanding the Subprime Mortgage Crisis Demyanyk and Van Hemert, February, 2008
• Delinquency rates by age of mortgage plotted for different origination years.
• Sub-prime mortgages (equal to about 20% of US mortgage market in 2007) showed major deterioration for mortgages originated in 2006.
• More broadly, fixed rate mortgages did not deteriorate so much. (Defaults rates looked like those seen in early 2000s.
• Plot shows prices of AA-rated US Fixed Rate Home Equity Loan Asset Backed Securities (ABS) with face value of 100.
• Prices are measured relative to “curve” the average AA-rated issue.
• Plot shows opening up of substantial price variation from August 2007 onwards.
• No one knew at that time how to value illiquid ABS. This created distrust and confusion in banks.
Loophole 1:
• Banks are allowed to calculate capital separately on trading book and banking book assets.
• The trading book capital rules in Basel II were hardly changed from those employed under Basel I. Banks calculated capital using short-term volatility models.
• This was reasonable if trading book exposures were very liquid and could be bought and sold easily if market prices started to move substantially.
• But post 2000, banks had built up major credit derivative and structured product positions in their trading book , incentivised by fact that trading book capital was relatively low for such exposures. Loophole 2:
• Basel II was overwhelmingly about capital and paid insufficient attention to funding liquidity.
• The risk implications of business models that heavily relied on the availability of short term funding (secured or unsecured ) were not understood or properly allowed for.
• In Basel II banks were required to monitor and Portfolio Value for 3 ABS manage their liquidity positions through such devices as maturity ladders, liquidity stress testing and contingency planning.
• But these systems were not enforced rigorously enough to constrain behaviour and typically banks aimed to be able to cope with disruptions to funding that lasted a couple of weeks not six months or a year.
• What one could expect from a banking system that had been radically transformed through the growth in credit derivative and risk transfer markets was little understood before the crisis.
Key points:
1. Thirty years ago, a crisis in US subprime might have affected a group of geographically specialised lenders with a particular emphasis in their customer base. When the crisis occurred, the market was concerned that almost any bank was exposed to the crisis.
2. The volume and complexity of risk transfers meant that the true extent of values or liabilities values was very hard to assess. Reliance on the ratings agencies had become excessive.
3. In a world where values are uncertain there is a much increased risk of general distrust between counterparties and hence a higher risk of a breakdown in the markets for liquidity.
Ashcraft and Schuermann (2008): “Understanding the Securitization of Subprime Mortgage Credit”
But all securitisation markets were not the same…
US Securitisation Markets European Securisation Markets
1. Vertically disintegrated industry 1. Vertically integrated issuers common
2. Non-bank balance sheet issuers common 2. Most balance sheet issuers banks
3. Mortgage market without recourse 3. Mortgage market with recourse
4. Regulation split between agencies 4. Regulation more unified
5. Most of market covered by government 5. Almost no public role in market guarantees (via agencies)
• Post-crisis volatility in European securitisation ratings occurred despite good credit performance.
• Since 2007, UK, France, Spain and Italy showed peak to trough GDP declines of 7.2%, 4.4%, 5.0%, and 7.2% respectively
• Retail and SME loan backed securitisations have been strikingly robust to the crisis
• RMBS, Other Consumer ABS, Credit Card ABS and SME ABSs experienced cumulative default rates of 0.10%, 0.13%, 0.00% and 0.41% respectively between 2007 and 2013
Structured finance average 1-year default rates for 1983-2012
Source: Standard & Poor’s
1. Are securitisations more opaque as securities than
a) Bank stocks
b) Bank bonds
c) Covered bonds and hence deserving of tighter regulatory treatment?
2. If the crisis had not been triggered by securitisations, might the collapse of some other asset class have triggered it?
3. Is there any difference between a bank holding securitisations through the trading book versus the banking book? Should the capital treatments be different?
1. Following the crisis, securitisation was blamed by many commentators for what had gone wrong.
2. Naturally, a major effort began among regulators to tighten up the capital rules for securitisations.
3. (We shall talk about this tightening of regulation subsequently.)
4. A parallel move began to tighten regulation of ratings agencies particularly as their activities related to securitisation
5. Volumes of new issues sank with the exception of issues aimed at creating securities that could be retained and employed as collateral for central bank borrowing.
6. Investor demand disappeared with pension funds and insurers being much more conservative.
7. In the next few slides, we look at statistics to see how the market has evolved recently and what are the states of new issuance and amounts outstanding.
Europe US AU 2009 423.9 1,447.2 9.7 2010 378 1,245.9 15.5 2011 376.8 1,068.9 20.4 2012 257.8 1,609.0 14.8 2013 180.8 1,565.1 22.4 2014 217.1 1,190.9 22.1 2015 216.6 1,744.5 19.9 2016 239.6 1,860.4 16.4 2017 236.5 1,899.3 29.2 2017 (Q1 to Q3) 162.3 1,414.3 21.6
• Recent US issuance has been stable with some 2018 (Q1 to Q3) 180.1 1,338.6 14 fluctuations sustained by agency securitisations Source: Bank of America Merrill-Lynch, Bloomberg, Citigroup, Dealogic, Deutsche Bank, JP Morgan, Macquarie, Refinitiv, Unicredit, AFME, SIFMA
• European issuance has trended downwards since the Lehmans Brothers collapse with a stabilisation in 2016.
• Much issuance has been associated with central bank collateral.
• European issuance has been 10-15% of US volumes
European Issuance by Collateral (€ Billions) US Issuance by Collateral (€ Billions)
2018 (Q1 2017 (Q1 2017 (Q1 2018 (Q1 2017 (Q1 2017 (Q1 to Q3) to Q3) to Q4) to Q3) to Q3) to Q4) ABS 39.3 30.2 52.9 ABS 170.2 163.1 219.1 CDO/CLO 42 31 44.7 CDO 121.8 192.2 262.4 CMBS 3.9 1.8 0.9 Agency MBS 818.2 918.2 1,223.3 RMBS 87.4 90.5 123 Non-Agency CMBS 56 58.1 84.4 SME 7.5 10.4 14.9 Non-Agency RMBS 172.3 82.5 110.1 WBS/PFI 0 0 0 Total 1,338.6 1,414.3 1,899.3 Total 180.1 162.3 236.5
European Issuance by Retention (€ Billions)
• RMBS are the bulk of European issues 2018 (Q1 2017 (Q1 2017 (Q1 followed by CDOs/CLOs and ABS (autos to Q3) to Q3) to Q4) and cards) Placed 100.2 79.8 111.3
• SME-loan-backed issues have been minor Retained 80 82.7 125.2
• Only about half of European issuance is Total 180.1 162.3 236.5 sold into the market
• 61% of US issues are agency MBS, of non-agency,
• 56% of European issues are placed and 44% ABS and CDOs comprise 33% and 24%, the rest retained being property related
Source: Bank of America Merrill-Lynch, Bloomberg, Citigroup, Dealogic, Deutsche Bank, JP Morgan, Macquarie, Refinitiv, Unicredit, AFME, SIFMA
Issuance by Country of Collateral (€ Billions) Issuance by Collateral Type and Country of Collateral:Q3 2018 (€ Billions)
ABS CDO/CLO CMBS RMBS SME WBS/PFI TOTAL 2018 (Q1 2017 (Q1 2017 (Q1 Belgium to Q3) to Q3) to Q4) Denmark - Belgium 0.2 12.3 12.3 France 0.6 5.0 5.6 Denmark 0 0 0 Germany 2.0 2.0 France 16.8 35.1 36.9 Greece 0.1 0.1 Ireland 0.4 3.3 3.8 Germany 7.6 7.5 12.9 Italy 1.7 9.5 1.7 12.9 Greece 0.1 0 0 Netherlands 1.5 1.5 Ireland 8.5 1.6 4.4 Portugal - Italy 29 12.1 29.5 Spain 0.6 0.2 0.8 Netherlands 25.5 15.8 15.9 UK 2.2 0.8 9.2 12.3 Other EU 0.1 0.1 Portugal 2.9 0.3 1.1 Other Europe 0.1 0.1 Spain 5.9 10.1 25.6 PanEurope 14.2 0.2 14.4 UK 36.7 33.6 47.2 Multinational - Other EU 0.6 0.8 1.5 European Total 7.8 14.2 1.1 28.6 1.9 - 53.6 Other Europe 1.2 1 2.3 NON- NON- PanEurope 45.1 31.6 45.4 AGENCY AGENCY AGENCY Multinational 0 0 0 ABS CDO MBS CMBS RMBS TOTAL European Total 180.1 161.9 235 US Total 43 24.2 293.8 18.2 105 484.2 US Total 1,338.6 1,414.3 1,899.3
• UK RMBS contribute most to recent issuance volume followed by Netherlands and Italian RMBS
• These three contribute 53% of the entire market
• CDO/CLOs are Pan-European in underlyings
Source: Bloomberg, Citigroup, Dealogic, Bank of America-Merrill Lynch, Deutsche Bank, JP Morgan, Macquarie, Refinitiv, Unicredit, AFME, SIFMA
European Issuance by Rating (€ Billions) US Issuance by Rating (€ Billions)
2018 2017 2018 (Q1 2017 (Q1 2017 (Q1 AAA 101.7 113 to Q3) to Q3) to Q4) AA 28.1 52.2 AAA 200.8 259.7 343.5 A 12.7 27.2 AA 24.7 38.8 51.2 BBB & Below 11.7 12.3 A 25 31.6 42.9 Not Rated 25.9 31.8 BBB & Below 39.6 42.6 57.2 European Total* 180.1 236.5 Not Rated 230.3 123.4 181.3
Source: Bank of America-Merrill Lynch, Bloomberg, Citigroup, Agency MBS 818.2 918.20 1,223.30 Dealogic, Deutsche Bank, JP Morgan, Macquarie, Refinitiv, US Total 1,338.60 1,414.30 1,899.30 Unicredit, AFME, SIFMA
• In Europe, 56% of issues in 2018 were rated AAA, while 14% were unrated
• In contrast in the US, 25% of non-agency issues were AAA and 28% were unrated
• This suggests that the US market is less in thrall to the ratings agencies than the European
• Non-AAA fell from 52% to 44% of total European issuance from 2017 to 2018. On the other hand in the US, non-AAA went from 49% to 61% from 2017 to 2018.
European Outstandings by Collateral (€ Billions) US Outstandings by Collateral (€ Billions)
2018:Q3 2018:Q3 ABS 217.6 ABS 1,345.80 CDO/CLO 124.7 Agency MBS 6,173.70 CMBS 50.3 Non-Agency CMBS 702.4 RMBS 670.5 Non-Agency RMBS 459.3 SME 69.9 Total 8,681.2 WBS/PFI 63.2 Total 1,196.3
Source: Bloomberg (US & Europe), Fannie Mae (US), Federal Reserve (US), Freddie Mac (US), Ginnie Mae (US), Loan Performance (US), Dealogic (US), Macquarie (Australia), Refinitiv (US), AFME &SIFMA Estimates (US & Europe)
• In Europe, 56% of the outstanding market volume is RMBS with ABS, CD)/CLO, SME and CMBS contributing 18%, 10%, 6% and 4%.
• In the US, ABS, non-agency CMBS and non-agency RMBS represent 54%, 28% and 18% of non-agency issues.
• ABS and property related issues (agency and non-agency) represent 16% and 84% of total outstandings.
European Outstandings by Vintage (€ Billions) European Outstandings by Collateral and Country:Q3 2018 (€ Billions)
ABS CDO/CLO CMBS RMBS SME WBS/PFI TOTAL 2018:Q3 Austria 0.3 1.2 1.5 2018 168.7 Belgium 0.4 0.1 39.1 17.1 56.7 Finland 0.7 0.5 1.2 2017 202.0 France 21.5 0.07 0.2 83 0 104.8 2016 166.2 Germany 36.2 0.2 1.2 2.9 6.2 0 46.9 Greece 8.5 1.8 0.2 1.1 7.1 18.6 2015 95.9 Ireland 0.8 0.2 27.4 0.19 28.5 2014 82.7 Italy 65.5 0.5 2.7 59.9 13.9 0.3 142.9 2013 49.9 Netherlands 2.3 0 0.4 172.4 0 175.2 Portugal 3.7 0.53 18.1 4.3 26.8 2012 29.8 Russia 1.5 - 1.5 2011 29.0 Spain 23.9 0.3 0.3 115.7 14.7 154.9 Turkey 1.4 1.4 2010 83.0 UK 46.5 7.3 40.9 147.1 5.8 61.8 309.4 2009 42.5 Other 4.5 0.2 0.08 0.9 0.31 6 Prior 246.7 PanEurope 1.1 101.7 3.6 0.1 0.3 0.1 106.9 Multinational 0.1 12.7 0.4 13.2 Total 1196.3 European Total 217.6 124.7 50.3 670.5 69.9 63.2 1196.3 Source: Bloomberg, Macquarie, AFME, SIFMA
• The major European markets by amounts outstanding are, in order, UK, Netherlands, Spain and France.
• RMBS followed by ABS are the dominant contributors.
• Spain, Italy and Belgium have some SME-backed issues.
US (without Agency Europe US MBS) AU 2000 78.2 1088.0 2001 152.6 2308.4 2002 157.7 2592.7 2003 217.3 2914.5 2004 243.5 1956.6 2005 327.0 2650.6 2006 481.0 2455.8 2007 453.7 2147.1 1,289.19 2008 711.1 933.6 154.63 2009 423.9 1,447.2 127.92 9.7 2010 378 1,245.9 95.42 15.5 2011 376.8 1,068.9 123.25 20.4 2012 257.8 1,609.0 220.34 14.8 2013 180.8 1,565.1 271.54 22.4 2014 217.1 1,190.9 373.49 22.1 2015 216.6 1,744.5 431.20 19.9 2016 239.6 1,860.4 332.99 16.4 2017 236.5 1,899.3 676.0 29.2 2017 (Q1 to Q3) 162.3 1,414.3 496.1 21.6 2018 (Q1 to Q3) 180.1 1,338.6 520.4 14
Source: Bank of America Merrill-Lynch, Bloomberg, Citigroup, Dealogic, Deutsche Bank, JP Morgan, Macquarie, Refinitiv, Unicredit, AFME, SIFMA
European Total US Total US Total (without Agency MBS) 2007:Q3 1467.5 2007:Q4 1617.5 2008:Q1 1607.7 6167.9 3165.3 2008:Q2 1736.7 6341.0 3235.5 2008:Q3 1795.8 6984.4 3449.5 2008:Q4 2134.9 7056.3 3424.5 2009:Q1 2179.9 7365.0 3521.2 2009:Q2 2199.6 7056.5 3228.1 2009:Q3 2237.0 6780.0 3017.0 2009:Q4 2220.9 6892.0 3000.7 2010:Q1 2167.0 7568.9 3435.8 2010:Q2 2070.1 8135.7 3667.1 2010:Q3 2083.5 8139.5 3163.4 2010:Q4 2089.8 8264.2 3154.1 2011:Q1 2115.3 6541.5 2527.0 2011:Q2 2079.0 6330.9 2391.3 2011:Q3 1992.1 6783.8 2513.3 2011:Q4 1993.7 6922.9 2529.5 2012:Q1 1922.6 6682.8 2493.7 2012:Q2 1810.3 6978.1 2552.3 2012:Q3 1733.4 6827.2 2450.4 2012:Q4 1712.7 6646.7 2358.9 2013:Q1 1653.9 6852.5 2408.2 2013:Q2 1600.4 6751.9 2328.3 2013:Q3 1551.1 6496.9 2192.1 2013:Q4 1503.5 6449.1 2151.6 2014:Q1 1446.9 6448.1 2152.6 2014:Q2 1444.6 6438.9 2110.3 2014:Q3 1446.8 7056.2 2335.6 2014:Q4 1441.0 7407.5 2442.1 2015:Q1 1373.2 8375.1 2765.8 2015:Q2 1355.6 8126.3 2676.7 2015:Q3 1329.7 8125.0 2625.5 2015:Q4 1301.9 8382.3 2656.4 2016:Q1 1273.0 8034.3 2500.2 2016:Q2 1278.2 8252.7 2529.1 2016:Q3 1249.2 8204.1 2451.1 2016:Q4 1262.5 8851.5 2567.8 2017:Q1 1229.7 8810.3 2587.3 2017:Q2 1231.6 8274.8 2404.3 2017:Q3 1198.2 8076.3 2313.4 2017:Q4 1217.2 8077.2 2309.2 2018:Q1 1190.4 7927.4 2252.5 2018:Q2 1200.9 8499.5 2450.1 2018:Q3 1196.3 8681.2 2507.5
Source: Bank of America Merrill-Lynch, Bloomberg, Citigroup, Dealogic, Deutsche Bank, JP Morgan, Macquarie, Refinitiv, Unicredit, AFME, SIFMA
1. List the three differences between the US and European securitisation markets that strike you as most important?
2. What are the challenges that these differences create for international regulation such as the Basel framework?
3. What are the legitimate uses of securitisation that regulators may view favourably – if any?
4. What would you forecast will happen to the securitisation market in the US and Europe over the next few years?
1. Introduction to securitisation
2. Risk analysis and pricing of securitisations
3. Regulation of securitisations
4. Practical exercise 1: PURA RTS
5. Role of the ratings agencies
6. Liquidity of securitisations
7. Market drivers and motives for using securitizations
8. Practical exercise 2: Optimal Tranching
• How can one model expected losses and calculate capital requirements for holdings of different tranches of a securitisation?
• Focus on a simple, essentially static model, in which exposures default or not by some terminal date T.
• Suppose an SPV has issued a set of tranches of notes of different seniorities and that these tranches are repaid or not again at the terminal date T.
• Structured product agreements are complex and contain detailed rules on how senior tranches are amortised early (e.g., if financial triggers based on ratios of asset value to liabilities are contravened).
• We ignore possibilities of cash flow prior to T and rule out the complexities of real life deals such as collateral or interest rate triggers and early amortization.
• While very stylised, this approach reveals much about the basic properties of structured exposures.
• The starting point for analysis is the distribution of losses on the pool.
• After examining some simple binomial examples, we shall study the Vasicek distribution (which is the basis for the Basel II capital formulae for loans) both in its conditional and unconditional form.
3 Assets Pascal Tree for Portfolio of 1, 2 and 3 Assets
12.5% 2 Assets
25% 1 1 Asset
37.5% 50% 1 + 3
100% 50% + 2
37.5% + 50% 1
25% 1
50% probability of going up (no default)
12.5% 1 PD = 50% probability of going down (default)
Any point of the Pascal probability tree is the sum of two previous probability of occurrence weighted respectively by the probabilities of going up (no default event) and down (default event with LGD=100%)
The integers on the right (in pink), are the number of possible outcomes
© Dr. Georges Duponcheele 30
Loss Distribution with 1 asset (PD=50%, LGD=100%)
100%
1 asset
80% The loss distribution (in blue) is horizontal Average Loss
Max Loss 60% PD=50%, LGD=100%, N=1 50.0000%
40% Probability (%) Situations where the only 50% tranche defaults
20%
0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 31
Loss Distribution with 2 uncorrelated assets (PD=50%, LGD=100%)
100%
80% 75.0000% Situations where top tranche defaults
60%
50% + 25% Average Loss
Max Loss 40% Probability (%) PD=50%, LGD=100%, N=2
25.0000% Situations where bottom tranche defaults 20%
25%
0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 32
Loss Distribution with 3 uncorrelated assets (PD=50%, LGD=100%)
100%
87.5000%
Situations 80% where Situations mezzanine where top tranche tranche defaults 60% defaults
50.0000% 37.5% + 37.5% + 12.5% Average Loss
Max Loss 40% Probability (%) PD=50%, LGD=100%, N=3 Situations where bottom tranche 20% defaults 37.5% + 12.5% 12.5000%
12.5% 0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 33
Loss Distribution with 4 uncorrelated assets (PD=50%, LGD=100%)
100% 93.7500%
Situations Situations Situations 80% where top where upper where tranche 68.7500% mezzanine bottom defaults tranche tranche defaults 60% defaults Situations Average Loss where lower mezzanine Max Loss 40% Probability (%) tranche PD=50%, LGD=100%, N=4 31.2500% defaults
20%
6.2500%
0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 34
Loss Distribution with 5 uncorrelated assets (PD=50%, LGD=100%)
96.8750% 100%
bottom 81.2500% tranche 80%
junior mezzanine
60%
50.0000% Average Loss
middle Max Loss 40% Probability (%) mezzanine PD=50%, LGD=100%, N=5
18.7500% 20% top tranche senior
3.1250% mezzanine
0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 35
Loss Distribution with 6 uncorrelated assets (PD=50%, LGD=100%) 98.4375% 100%
89.0625%
80%
65.6250%
60%
Average Loss The “Inverted S” Max Loss 40% Probability (%) curve starts 34.3750% PD=50%, LGD=100%, N=6 taking shape
20%
10.9375%
1.5625%
0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 36
Loss Distribution with 7 uncorrelated assets (PD=50%, LGD=100%) 99.2188% 100% 93.7500%
77.3438% 80%
60%
50.0000% Average Loss
Max Loss 40% Probability (%) PD=50%, LGD=100%, N=7
22.6563%
20%
6.2500%
0.7812%
0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 37
Loss Distribution with 8 uncorrelated assets (PD=50%, LGD=100%) 99.6094% 100% 96.4844%
85.5469%
80%
63.6719%
60%
Average Loss
Max Loss 40% 36.3281% Probability (%) PD=50%, LGD=100%, N=8
20% 14.4531%
3.5156% 0.3906% 0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 38
Loss Distribution with 9 uncorrelated assets (PD=50%, LGD=100%) 99.8047% 98.0469% 100%
91.0156%
80% 74.6094%
60%
50.0000% Average Loss
Max Loss 40% Probability (%) PD=50%, LGD=100%, N=9
25.3906%
20%
8.9844%
1.9531% 0.1953% 0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 39
Loss Distribution with 10 uncorrelated assets (PD=50%, LGD=100%) 99.9023% 98.9258% 100% 94.5313%
82.8125%
80%
62.3047% As the 60% granularity Average Loss increases, Max Loss 37.6953% 40% Probability (%) the PD=50%, LGD=100%, N=10 “Inverted S” curve is
17.1875% 20% clearly visible 5.4687%
1.0742% 0.0977% 0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 40
Pascal Tree for up to 10 Assets: Probabilities Cumulated Number of Probability of Binomial (10 defaults Number 1 occurrence assets) of Assets 1 2 3 4
- - - - - - - - - - 0.1% 0 0.0977%
- - - - - - - - - 0.2% -
- - - - - - - - 0.4% - 1.0% 1 1.0742%
- - - - - - - 0.8% - 1.8% - +
- - - - - - 1.6% - 3.1% - 4.4% 2 5.4688%
- - - - - + 3.1% - 5.5% - 7.0% -
- - - - 6.3% - 9.4% - 10.9% - 11.7% 3 17.1875%
- - + - 12.5% - + 15.6% - + 16.4% - 16.4% -
- - 25.0% - 25.0% - 23.4% - 21.9% - 20.5% 4 37.6953%
- 50.0% - 37.5% - + 31.3% - 27.3% - 24.6% - + 100.0% - 50.0% - 37.5% - 31.3% - 27.3% - 24.6% 5 62.3047% +
- 50.0% - 37.5% - 31.3% - 27.3% - 24.6% -
- - 25.0% - 25.0% - 23.4% - 21.9% - 20.5% 6 82.8125% + +
- - - 12.5% - 15.6% - 16.4% - 16.4% -
- - - - 6.3% - 9.4% - 10.9% - 11.7% 7 94.5313%
- - - - - + 3.1% - 5.5% - 7.0% -
- - - - - - 1.6% - 3.1% - 4.4% 98.9258%
- - - - - - - 0.8% - 1.8% - + 9 99.9023%
- - - - - - - - 0.4% - 1.0%
- - - - - - - - - 0.2% - 10 100.0000%
- - - - - - - - - - 0.1%
50% probability of going up (no default)
PD = 50% probability of going down (default)
The probability of occurrence for each outcome obtained via a Pascal Tree is also called the “binomial distribution”. It depends on the number of assets and on the probability of the event (such as “exactly 7 default” (11.7%)).
The “cumulated binomial distribution” gives the probability of having at least a given event (such as “3 defaults or more” is 94.53%)
© Dr. Georges Duponcheele 41
Default Correlation 0%
Loss Distribution with 10 correlated assets (PD=50%, LGD=100%, ρD=0%) 99.9023% 98.9258% 100% 94.5313%
82.8125%
80%
62.3047%
60%
Average Loss
Max Loss 37.6953% 40% Probability (%) PD=50%, LGD=100%, ρD=0%
17.1875% 20%
5.4687%
1.0742% 0.0977% 0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 42
Default Correlation: 2.5%
Loss Distribution with 10 correlated assets (PD=50%, LGD=100%, ρD=2.5%) 99.7610% 98.0868% 100%
92.3942%
80.0090% 80%
60.8869%
60%
Average Loss
38.9511% Max Loss 40% Probability (%) PD=50%, LGD=100%, ρD=2.5%
19.9686% 20%
7.6920%
1.9891% 0.2612% 0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 43
Default Correlation: 5%
Loss Distribution with 10 correlated assets (PD=50%, LGD=100%, ρD=5%) 99.5565% 97.1375% 100%
90.3793%
77.6414% 80%
59.6760% 60%
Average Loss
39.7981% Max Loss 40% Probability (%) PD=50%, LGD=100%, ρD=5%
22.2261%
20%
9.8656%
3.1560% 0.5635%
0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 44
Default Correlation: 7.5%
Loss Distribution with 10 correlated assets (PD=50%, LGD=100%, ρD=7.5%) 99.2899% 100% 96.1119%
88.4829%
80% 75.5929%
58.6258% 60%
Average Loss
40.3906% Max Loss 40% Probability (%) PD=50%, LGD=100%, ρD=7.5%
24.0681%
20%
11.8961%
4.4954% 1.0465%
0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 45
Default Correlation: 10%
Loss Distribution with 10 correlated assets (PD=50%, LGD=100%, ρD=10%) 98.9637% 100% 95.0343%
86.6965%
80% 73.7870%
57.6998% 60% As the Average Loss correlation 40.8167% Max Loss 40% Probability (%) increases, it PD=50%, LGD=100%, ρD=10% flattens the 25.5896% “Inverted S”
20% curve 13.7489%
5.9228%
1.7407%
0%
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100%
Risk Scale: Capital Structure
© Dr. Georges Duponcheele 46
1. Can you explain intuitively why, for a given number of loans, the curve flattens as correlation goes up?
2. In the binomial model, what do you think happens to the loss curve as the number of loans goes to infinity if the loan defaults are independent?
3. In the binomial model, what happens to the curve if the number of loans goes to infinity and the defaults are perfectly correlated?
4. Can you guess how things turn out if loans are imperfectly correlated and the number goes to infinity?
• Given a loss distribution for the underlying pool (typically of loans), we shall consider how one can calculate the Expected Losses (EL on a tranched exposure to that pool.
• A short set of arguments will take us to the marginal Value at Risk (MVaR) associated with holdings of tranches of a tranched exposure.
• Finally, we shall talk about pricing and show that again, from the EL, we may infer the price of the tranched exposure.
• The framework we use has been called the Arbitrage Free Approach (AFA).
• It build on a classic paper by Pykhtin and Dev on capital for securitisations, first, in a static version recalibrating and aligning to Basel II capital analysis, and second, generalising that approach to multiple periods.
• The AFA model employs as its starting point the same assumption as the original Asymptotic Single Risk Factor (ASRF) model employed in Basel II.
• Both start with the Vasicek distribution of losses on a loan pool.
• The ASRF model presumes that the exposures in give classes in the bank’s portfolio have Basel-prescribed asset correlations, e.g., any pair of high credit corporates had asset correlations of 24%.
• The AFA model assumes that a securitisation pool exposure has the same Basel-prescribed correlation with an exposure in the bank portfolio as it would have if the two exposures were both in the bank portfolio (again, in our example, 24%); but that it is more correlated with other comparable exposures in the securitisation pool.
• A single parameter, r* , describes this additional within-poolcorrelation.
• Varying r* alters the allocation of capital across tranches of different seniority but does not affect the total capital of all the tranches together since this is determined by the correlations of the pool exposures with bank portfolio exposures which are set at Basel II levels
• The AFA model is based on a simple extension of the assumption of the original Asymptotic Single Risk Factor model employed in Basel II.
• The latent variable for the ith loan in the bank portfolio:
• The probability of default is:
• Here, YB is the Basel Asymptotic Single Risk Factor, X is an uncorrelated additional common factor and the ei’s are idiosyncratic shocks.
• Choosing the correlation parameters, r*, to take the Basel II values, ensures that the MVaRs of a pool of such assets will equal the Basel II levels and so capital for all the tranches of a securitization equals the Basel II levels for on balance sheet assets.
• The additional common factor risk from X spreads risk and capital across tranches in the structure in a smooth and economically well-motivated way.
• Rearranging, we get the latent variable for the ith pool exposure:
• Here, rPool is the pairwise correlation of individual obligors’ asset values.
• Note that rPool is higher than the Basel parameter, r, reflecting the fact that there is additional correlation or concentration in the securitization pool assets by assumption.
• Vasicek (2002) explains how to calculate the distribution of portfolio losses in such a model.
• A given thin tranche defaults when losses exceed the tranche attachment point.
• If the tranche is thin, the detachment point is just slightly higher so if default occurs, the loss given default on the tranche is 100%.
• So the expected loss on the tranche equals the probability of default.
• One may think of a thick tranche with attachment point discretely below its detachment point as a portfolio of thin tranches.
• Expected losses are additive in exposures so the expected loss on the thick tranche is the sum of those on the thin ranches that make it up.
• Thin tranche expected loss with attachment point A
• Thick tranche expected loss with attachment point A and detachment point D
• Gourieroux, Laurent and Scaillet (2001) show in general that:
Expected Losses Unexpected Losses conditional on bank (with a confidence Expected Losses = portfolio losses level of a) equalling their aquantile
• In other words, to work out the capital on a tranche, we can (i) calculate the expected loss conditional on total bank losses equalling their a-quantile and
(ii) subtract the expected loss.
• Thin tranche expected loss equals its default probability and this in turn equals the probability that losses exceed the attachment point.
• Calculating this with and without a stress and then integrating over successive ‘thin tranche’ attachment points up to the thick tranche detachment point then gives us the capital number.
• Stressed default probability of pool exposures
• Stressed correlation between pool assets
• Unexpected-loss based capital K(A,D)
Note that, the stressed PD The stressed correlation (r*) is obtained by calculating how much pairwise asset (denoted PDa) is obtained by correlation will be left once we have assumed a calculating the PD when YB has a big negative shock. particular shock for YB .
Expected Loss and Thin Tranche Capital as a function of attachment/detachment points:
Cumulative Probability
Capital Structure
• For a discretely thick tranche with attachment and detachment points A and D has EL equal to the area between A and D under the real line, Marginal Value-at-Risk equal to the area under the blue curve between A and D and Unexpected losses equal to the difference between the two.
• The shape of the EL curve is determined by rPool whereas the shape of the Marginal Value-at-Risk curve is determined by r*.
• Unexpected-loss based capital K(A,D) can be expressed in terms of pool unexpected loss, K, and pool EL in that: = KIRB PDα = K+ EL LGD LGD
PD= EL/LGD
• It follows that
EL KIRB

LGD - ELTℎicktrancℎe A, DฬρPool, LGD
• This is a key result: tranche capital depends on (i) attachment and detachment points, (ii) pool capital and (iii) pool EL.
• Here, KA, D is the tranche Unexpected Loss (UL), the first term on the RHS is the tranche Marginal VaR and the second term on the RHS is the tranche Expected Loss (EL).
• KA, D is exactly symmetric with the standard Basel II capital formula for loans which is based on a UL notion of capital.
Thin Tranche MVaR for Different r* Values:
Cumulative Probability
Capital Structure
• When r* is zero, the capital curve is a step function.
• For higher values, the curve flattens out, implying higher capital for senior tranches.
• The key parameter in the above capital model is r*.
• This determines how the pool capital is spread out over different tranches.
• It can be calibrated using rating change correlations in a two-step process described below.
Maximum Likelihood based Step 1: Estimate Intra-Sector All regions All regions North America North America Correlations Sample 2000-2012 2005-2012 2000-2012 2005-2012
• The r* parameter may be inferred 1. RMBS 83.9% 75.1% 84.2% 75.2% from estimates of the correlation 2. ABS 50.5% 50.4% 48.3% 50.8%
3. Other 79.3% 81.0% 82.7% 83.5% between bank and SPV pool factors
4. PF 48.7% 42.7% 48.7% 42.7%
• If there were no additional risk
5. CDO 68.8% 77.2% 76.4% 85.1% factors in the SPV pool, then all 6. CMBS 72.4% 73.0% 71.3% 74.1% ratings would move together in 7. Structured Products 65.9% 64.7% 84.2% 75.2% perfect lock-step.
• Step 1: estimate (asset) correlation of individual tranche
• So one may identify the r* from ratings. the degree to which changes in individual tranche ratings are
• Step 2: infer r* given that correlations between pool correlated. and bank portfolio exposures must equal Basel II assumptions.
Step 2: Infer r*
Maximum Likelihood based estimates • This approach yields r* r r* r* r* r* estimates for different periods All All North North and data sets Assumed regions regions America America Basel 2000- 2005- 2000- 2005-
• We find plausible patterns 2012 2012 2012 2012 Sector value with higher r* for CDO and
1. RMBS 15% 3% 6% 3% 6% ABS (with structured and other
2. ABS 10% 11% 11% 12% 11% underlyings) and lower values
3. Other 10% 3% 3% 2% 2% for retail
4. PF 20% 26% 34% 26% 34%
5. CDO 20% 11% 7% 8% 4%
• Note the fact that one can
6. CMBS 9% 4% 4% 4% 3% calibrate r* from data does not
7. Structured Products 16% 10% 10% 4% 6% mean we do not see it as a
• Alternative calibration approaches for r* include direct regulator control variable – estimation of correlation for pools and bank portfolios but it is surely an advantage
• This is data intensive
• The model described above is a single period model.
• We now turn to deriving a multi-period model consistent with it.
• We replace Gaussian random factors with Brownian motions evolving for t>0.
• We assume the same correlation structure over discrete time periods.
• The credit quality of the ith loan is driven by:
• The pairwise correlation of the discrete time increments
• Conditional on , the correlation is equal to We need
• The risk adjusted process followed by the latent variable for the
1. To include a ith loan is: risk premium in the asset value processes for t>1. • The default probability inclusive of appropriate risk premiums is:
2. To include a stress on the bank risk factor where pdM is the M-period default probability and is equal to
• The stressed default probability is:
which may be set in the following way to ensure the neutrality between on- and off-balance sheet capital:
• We calculate capital for portfolios of loans held within a wider bank portfolio of loans.
• We also calculate capital for tranched exposures to this loan portfolio.
• A ratings-based model is employed but this time with a Longstaff-Schwarz approach to pricing the (long-lived, M-year-maturity) tranches at the 1-year VaR horizon.
• We assume securitization pools of 200 loans comprising 7% of the par of a wider bank portfolio of 500 BBB-rated loans.
• We look at cases with BB-rated and BBB-rated pool loans and with maturities of 1,2,3,4 and 5 years.
Tranche Par Assumptions
• We adopt the factor structure of the AFA with a r*=10% and the standard Basel II r values.
• We construct the tranched positions assuming 27 tranches as shown in the table.
Unexpected loss : maturity = 1 year(s) Unexpected loss : maturity = 2 year(s) 80 Unexpected loss : maturity = 3 year(s) Unexpected loss : maturity = 4 year(s)
• When maturity is increased, Unexpected loss : maturity = 5 year(s) the distribution of Unexpected Losses across tranches shifts to the right and widens out.
50 • Note here UL=MVaR-EL, i.e, UL is stressed EL – actual EL. Unexpected loss (%)
0 5 10 15 20 25 30 35 40 45 50 Protection (%)
• Given the concentration correlation ρ∗and the pool correlation ρPool = ρ+ 1 −ρ∙ρ∗, the correlation should be adjusted with a pool-level granularity adjustment (the same as in the current SFA) by using the square of the weights consolidated by obligors
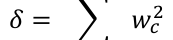
c⊂Pool to obtain the granularity-adjusted pool correlation (to calculate EL):
ρ′Pool = ρPool + δ∙1 −ρPool
and to obtain the granularity-adjusted stressed correlation (to calculate Stressed EL): sρ′ = ρ∗ + δ∙1 −ρ∗
• Numerical illustrations: Experiments
• For 1000 identical assets, δ= 0.1% and ρ∗ = 10%, suggests a we have sρ′ = 10% + 0.1% ∙1 −10% = 10.09% (insignificant change) granularity
• For 100 identical assets, δ= 1% and ρ∗ = 10%, adjustment should we have sρ′ = 10% + 1% ∙1 −10% = 10.9% (about 10% change) be used with
• For 10 identical assets, δ= 10% and ρ∗= 10%, portfolio with less we have sρ′ = 10% + 10% ∙1 −10% = 19% (significant change) than [100] effective exposures
Adjusting for granularity in the AFA Option 2 needs the following steps:
EADi
• given the notional weight wi of an asset i, (wi = EADPool)
• given the consolidated weight wc for the obligor of asset i, (wc = σi,i⊂c wi)
• given the concentration correlation ρi∗ for asset i,
• given the pool correlation ρiPooli in the theoretical pool: (ρiPooli = ρi + 1 −ρi ∙ ∗) ρi
We define an asset-level granularity adjustment δi for the theoretical pool Pooli such that: δi = wc
• the granularity-adjusted pool correlation (to calculate EL):
ρ′iPooli = ρiPooli + δi ∙1 −ρiPooli
• the granularity-adjusted stressed correlation (to calculate Stressed EL):
∗ ∗ + δi ∙1 −ρi sρ′iPooli = ρi
We have conducted convergence analysis of the granularity adjustments in Duponcheele, Perraudin, Pickett and Totouom- Tangho (2013d)
AFA and MC unexpected loss ( 128 pool exposures ) AFA and MC unexpected loss ( 64 pool exposures ) 100 100 AFA UL AFA UL 80 Monte Carlo UL 80 Monte Carlo UL
60 60
40 40
20 20 Unexpected loss(%) Unexpected loss(%) 0 0 0 5 10 15 20 25 30 35 40 0 5 10 15 20 25 30 35 40 Protection (%) Protection (%)
AFA and MC unexpected loss ( 32 pool exposures ) AFA and MC unexpected loss ( 16 pool exposures ) 100 100 AFA UL AFA UL 80 Monte Carlo UL 80 Monte Carlo UL
60 60
40 40
20 20 Unexpected loss(%) Unexpected loss(%) 0 0 0 5 10 15 20 25 30 35 40 0 5 10 15 20 25 30 35 40 Protection (%) Protection (%)
Examples suggest the AFA and MC unexpected loss ( 8 pool exposures ) AFA and MC unexpected loss ( 4 pool exposures ) 100[100] granularity adjustment δ to be AFA UL AFA UL 80 Monte Carlo UL 80 Monte Carlo UL down to [10] effective
60 60 exposures. 40 40
20 20 Unexpected loss(%) Unexpected loss(%) 0 0 0 5 10 15 20 25 30 35 40 0 5 10 15 20 25 30 35 40 Protection (%) Protection (%)
Sensitivity to heterogeneity in granularity: half of the portfolio is granular and the other half is increasingly less granular.
AFA and MC unexpected loss (aggregate 64 to 32 pool exposures ) AFA and MC unexpected loss (aggregate 64 to 16 pool exposures ) 100 100 AFA UL AFA UL N≈85.3 80 Monte Carlo UL 80 N≈51.2 Monte Carlo UL
60 60 Unexpected loss(%) Unexpected loss(%)
00 5 10 15 20 25 30 35 40 0 5 10 15 20 25 30 35 40 Protection (%) Protection (%)
AFA and MC unexpected loss (aggregate 64 to 8 pool exposures ) AFA and MC unexpected loss (aggregate 64 to 4 pool exposures ) 100 100 AFA UL AFA UL 80 N≈28.4 Monte Carlo UL 80 N≈15.1 Monte Carlo UL 60 60
40 40 Unexpected loss(%) Unexpected loss(%)
00 5 10 15 20 25 30 35 40 0 5 10 15 20 25 30 35 40 Protection (%) Protection (%)
AFA and MC unexpected loss (aggregate 64 to 2 pool exposures ) AFA and MC unexpected loss (aggregate 64 to 1 pool exposures ) 100 100 AFA UL AFA UL 80 Monte Carlo UL 80 Monte Carlo UL 60 N≈7.8[60] N≈3.9 Unexpected loss(%) Unexpected loss(%)
00 5 10 15 20 25 30 35 40 0 5 10 15 20 25 30 35 40 Protection (%) Protection (%)
Examples suggest the granularity adjustment δ to be down to [10] effective exposures. Sensitivity to heterogeneity in credit quality: a good credit quality portfolio is mixed with an increasing portion of low credit quality portfolio.
AFA and MC unexpected loss (90% BBB and 10% CCC ) AFA and MC unexpected loss (80% BBB and 20% CCC ) 100 100 AFA UL AFA UL Monte Carlo UL Monte Carlo UL 80 80
60 60 Unexpected loss(%) 20 Unexpected loss(%) 20
0 0 0 5 10 15 20 25 30 35 40 0 5 10 15 20 25 30 35 40 Protection (%) Protection (%)
AFA and MC unexpected loss (70% BBB and 30% CCC ) AFA and MC unexpected loss (60% BBB and 40% CCC ) 100 100 AFA UL AFA UL Monte Carlo UL Monte Carlo UL 80 80
60 60
40 40 Unexpected loss(%) 20 Unexpected loss(%) 20
0 0 0 5 10 15 20 25 30 35 40 0 5 10 15 20 25 30 35 40 Protection (%) Protection (%)
The AFA is more conservative than the Monte Carlo model for highly heterogeneous credit quality portfolio.
• Above we explained how a single expression can be used to calculate Expected Losses for a tranche as a function of pool EL and LGD:

LGD
• and also can be used to calculate tranche UL + EL: ELTℎicktrancℎe A, Dฬρ∗, KIRB LGD
• The same expression can be used in pricing since the value of a guarantee against the credit losses in the pool may be expressed as the risk adjusted Expected Loss: ELTℎicktrancℎe A, DฬρPool, ELRA LGD
• Here, ELRA is the pool risk-adjusted Expected Loss.
• Suppose that the loans consist of 1-year pure discount bonds paying $1 at the end of the year in case they do not default and yielding a value of (1 −LGD) in the event that they do default.
• If we observe the spread on such a loan, S, we can infer the riskadjusted pool EL, denoted ELRA , using the following logic: ELRA = 1 −exp−S
• This gives a powerful method that can be generalised in multiple ways for pricing tranches of securitisations.
• If we want to infer a spread for a 1-year note associated with the tranche in question, we can reverse the logic to get: STℎicktrancℎe = −log1 −ELTℎicktrancℎe A, DฬρPool, ELRA LGD
1. The AFA as calibrated here requires that intra-pool correlation is greater than the correlation between average pairs of assets on the bank balance sheet. Is this reasonable?
2. In slide 60, the area under the blue curve equals the total capital for all the tranches. What do guess this equals? (Hint: you might guess from the name.)
3. We have emphasised one approach to valuing securitisations that requires specification of correlations, pool PDS, LGDs etc. What alternative “simple” approach do you think is also used?
1. Introduction to securitisation
2. Risk analysis and pricing of securitisations
3. Regulation of securitisations
4. Practical exercise 1: PURA RTS
5. Role of the ratings agencies
6. Liquidity of securitisations
7. Market drivers and motives for using securitizations
8. Practical exercise 2: Optimal Tranching
• Here, we present perspectives on how much capital banks should hold against securitisation investments and explain how regulatory views on securitisation capital have varied over time and across jurisdictions.
• Securitisations are tranched exposures to pools of assets, typically credit exposures such as bonds or loans.
• A securitisation tranche experiences losses when pool losses exceed the tranche’s attachment point, and are limited to the tranche thickness, determined by the tranche’s detachment point.
• Since a securitisation just splits pool cash flows between tranche holders, the risk of holding all the tranches of a securitisation is identically equal to that of holding all the loans or bonds in the pool.
• However, if a tranche is sold to outside investors, the incentives of those involved in the origination or servicing of the underlying loans may be affected.
• For example, if the pool servicer no longer holds all the risk, their incentive to manage the pool effectively may be reduced.
• Equally, an originating bank that intends to sell the risk via a securitisation, may have weaker incentives to choose prudently from among prospective borrowers.
• These problems are referred to as “agency risk”. They provide arguments for some capital non-neutrality in the sense that one may require that the capital for all the tranches in a securitisation should somewhat exceed that required for holding pool assets.
• Academic research has uncovered evidence of agency risk in the US sub-prime market. Elul (2011), in particular, shows that the default rates of securitised sub-prime loans in the crisis period exceeded those of comparable but non-securitised loans.
Nonparametric Default Hazard Functions from Elul (2011)
The horizontal axis represents the age of the mortgage (in months) and the vertical axis shows the probability of default in the next quarter, conditional on not having defaulted before.
• Perraudin (2013) calculates, based on Basel II loan capital formulae, the boost in capital implied by these higher default rates and deduces an implied capital premium of 10-20%. Capital increases implied by “agency
• The current European securitisation market is certainly much cost” PD adjustments – Mortgage less subject to agency risk than the US sub-prime market at the Loans height of the pre-crisis US housing market boom. Capital Increase
• The European market consists of relatively simple Corporate Scaling including excluding securitisations of well-established asset classes implemented in Ratings PD Factor EL EL a vertically integrated way by regulated banks operating in a AA 0.04% 1.2544 19.87% 19.63% credit regulated environment. A 0.08% 1.2544 19.38% 19.08% BBB 0.29% 1.2544 18.33% 17.84%
• In this, it is very different from the pre-crisis US market in BB 1.05% 1.2544 16.85% 15.98% which sub-prime loans with little track record were originated B 5.14% 1.2544 14.12% 11.94% and securitised by non-bank specialist lenders that were following an originate-to-distribute business model. The PDs are from S&P 2011 annual
• Since the crisis, regulators have put in place a variety of global corporate default study and measures to reinforce the stability and performance of the rating transitions. The LGD securitisation market. calibration in this calculation is
• These include, among other measures, retention requirements, irrelevant. The asset value correlation improvements in transparency and availability of pool exposure coefficient is calibrated as 0.15. data and increased due diligence requirements for investors.
• Even before these changes were implemented, one should Perraudin (2014b) calculates the note that, despite the severity of the recent crisis, the peak to trough GDP declines for European market performed relatively well. UK, France, Spain and Italy after
• The GDP shock experienced in many European countries 2007 as being 7.2%, 4.4%, 5.0%, exceeded that in the US and yet default rates in the bulk of and 7.2% respectively, compared the European securitisation market were negligible. to 4.3% for the US.
• The primary exceptions were (i) securitisations that, while Excluding CDOs of ABS, CMBS European, contained indirect exposures to US mortgage and other CDOs, the default rate of assets and (ii) Commercial Mortgage Backed Securities European securitisations was (CMBS). 0.12%.
• The latter are subject to refinancing risk in the sense that Data in Standard & Poor’s (2013) the underlying mortgages often require refinancing when implies cumulative default rates in the securitisation matures which proved difficult in the Europe between 2007 and 2013 recent crisis. for RMBS, Other Consumer ABS,
• When the Basel II securitisation capital framework was Credit Card ABS and SME CLOs of designed, regulators were clear that the main risk in a 0.10%, 0.13%, 0.00% and 0.41%, securitisation depends on the risk of the underlying pool respectively. of assets.
• Therefore, the approach taken should start from capital neutrality but then include reasonable capital premiums.
• Following the crisis, regulators have been concerned to review and where appropriate modify prudential rules for securitisation, sometimes before modifying the prudential rules for the underlying assets where the main risk resides.
• In the trading book, substantial changes were implemented quite soon after the crisis in 2009.
• The banking book treatment of securitisation capital was subjected to a multi-year review by the Basel Committee’s RSW.
• The RSW’s initial consultative paper (see BCBS 236) published in December 2012 proposed for IRB banks a highly complicated capital formula based on an analytic approximation to an underlying model.
• The underlying model employed assumptions that were inconsistent with the assumptions behind the Basel II capital for on-balance-sheet loans.
• This meant that substantial deviations from capital neutrality arose for some exposures and much smaller deviations for others just because of inconsistency of assumptions rather than because of clear policy decisions.
• For SA banks, the RSW introduced a simple ad hoc formula, the so-called Simplified Supervisory Formula Approach (SSFA).
• This formula had the advantage that one could transparently calculate from the model’s parameters the deviation from capital neutrality that the framework implied (leaving aside the effect of capital floors).
• Specifically, a parameter p within the SSFA equals the fraction by which the sum of capital for all tranches post-securitisation exceeds pre-securitisation pool capital.
100%
• As a formula, the SSFA has a long history in that it was proposed in an early Basel II paper on SSFA (p=1) securitisation capital but rejected in favour of the 75% KSA complex SFA (which remained the Basel II C formula-based approach). a p
50%
• Since the crisis, the SSFA has been used for bank i t trading book capital for securitisations by the US a l authorities.
25%
• In July 2013, after a consultation period, the SSFA was implemented by the US as a Standardised Approach formula for banking book 0% 0% 1KSA 10% 2KSA 20% 3KSA 30% 4KSA 5KSA 6KSA 50% investments in securitisations, for which the US Capital Structure has set the p parameter to 0.5.
• The US implemented the SFA and SSFA For tranches with an attachment point respectively as IRB and SA methods for A greater than KT, capital is calculated securitisation. using an exponential function:
• It followed this approach in order to meet the requirements of the Dodd-Frank Act of 2010 which required the removal of references to KSSFA l, u= eau −eal agency ratings from regulatory rules. au−l
• In 2013, a set of industry quants specialised in securitisation risk analysis published a series of papers advocating securitisation capital calculation based on analytically solvable models.
• In these models (which in different versions were generalised to cover granularity, multi-period securitisations and multiple asset classes), either capital neutrality or controlled and reasonable deviations from it were allowed for.
• In December 2013, the RSW published in BCBS 269 a substantially revised framework which extended the USdesigned SSFA framework to an IRBA securitisation approach from a SA securitisation approach.
• Later, to avoid confusion with the names of the methods used for the underlying pool of assets, IRBA and SA were renamed SEC-IRBA and SEC-SA.
• The parameter p was set to a constant value of 1.0 in the SEC- SA while, in the SEC-IRBA, p, is a function of deal and pool characteristics with a floor of 0.3. For re-securitisations, p takes a constant value of 1.5.
• An important constraint on the RSW was to produce a Basel III set of rules that could be adopted by the US, and that meant using formulae-based instead of external ratings-based approaches.
• The External Ratings Based Approach (ERBA) (later renamed SEC-ERBA) proposed by the RSW is not used by the US.
• The role of ratings in regulation has been controversial not just in the US.
• The summit declaration of the Toronto G20 meeting announced the intention by other jurisdictions to reduce mechanistic reliance of regulation on agency ratings.
• In Europe, despite repeated subsequent statements by the authorities, little progress was been made.
• The hierarchy of capital approaches in BCBS 269 implied that, if possible, a bank should calculate capital for a securitisation position using in order
1. The SEC-IRBA (a version of the SSFA in which the pool capital input is based on a calculation of pool capital KIRB under Basel IRB standards)
2. The External Ratings Based Approach in which capital is deduced from a look up table based on agency ratings
3. The SEC-SA (a version of the SSFA in which the pool capital input is based on a calculation of pool capital KSA under the Basel Standardised Approach)
• After the December 2013 publication of BCBS 269, it became progressively more apparent to economic policy-makers who had followed the development of the Basel rules from a distance that the degree of conservatism would make it very difficult for the securitisation market to revive in jurisdictions where bank investors were a significant part of the buy side.
• This was particularly regrettable for the European market in which, in many countries, bank lending remained very subdued and where, after all, the securitisation market had been largely free of significant delinquencies throughout the crisis.
• In this context, the Bank of England and the ECB published in March and May 2014 two papers arguing that one should distinguish between High Quality Securitisations (HQS) (which are simple in structure and transparent in risk implications) and more complex deals.
• Perraudin (2014b) provided statistical evidence in favour of the notion that HQS are less risky and more liquid than non-HQS.
• While the joint Bank of England-ECB papers did not directly propose concessions in the regulatory treatment of HQS, many took this to be their implication.
• The EBA was mandated by the Commission to draft rules for such securitisation.
• HQS should exhibit superior risk and liquidity behaviour.
• The material in this section is extracted from Perraudin (2014), an investigation of the risk and liquidity performance of European securitisation tranches since 2005, commissioned by the Dataset 1: data from S&P starts in 2009 and includes bid-ask spreads. industry institution Prime Collateralised Securities (PCS).
• We focus on AAA-rated tranches for volatility and AAA and AA-rated tranches for liquidity in order to show that the HQS definition has incremental value in differentiating performance Dataset 2: drawn from Bloomberg and Reuters, starts in 2005. after allowing for the rating.
• We define HQS consistent with PCS’s key principles, namely:
1. Excluding securitisations that are issued under an originate-to-distribute business model.
2. Excluding securitisations that involve “leverage” in the sense that they create highly rated securitisation tranches out of pools containing lower rated, already credittranched securitisations.
3. Ruling out maturity transformation.
4. Requiring transparency.
• In practice, to represent the above principles, we define HQS as follows:
1. We rule out CMBS and large corporate securitisations (consistent with 3.)
2. We rule out resecuritisations (consistent with 2.)
3. We rule out any originate-to-distribute deals using a flag provided to us by PCS.
4. We require that the tranche be the most senior in the structure.
5. We require that the face value exceed 100mn monetary units (Euros, GBP or USD)
• Note: in fact, there were not any resecuritisations in our sample. This affects the comparisons we report below between HQS and non-HQS risk and liquidity measures. (If we did have resecuritisation data, one might expect to observe even bigger differences.)
All Countries - All Asset Types Non-periphery - All Asset Types % % 20[35] Note: results are 16 intuitive in all cases 12[20] except for periphery 8 volatilities in crisis
6 10 period. This reflects bank-level 0 0 selectivity effects in
HQS Non-HQS HQS Non-HQS the Spanish data,
Periphery - All Asset Types UK - All Asset Types % % with almost all the 12 25 HQS being issued by 10 20 8 distressed cajas. The results for periphery countries other than Spain are consistent 0 0 with intuition.
• The figure shows volatilities of HQS and Non-HQS over time for all asset types in four different country-groupings: all countries, non-periphery countries, periphery countries and the UK.
• Average volatilities are calculated as annualised percentages.
• For instance, in February 2010, the estimated volatility for all HQS asset types in all countries was approximately 5%, compared to a volatility of approximately 15% for non-HQS assets.
HQS Non-HQS Avg Avg
• The table displays key Mean Avg Avg Sample Mean Avg Avg Sample Price Price SD Volatility Size Price Price SD Volatility Size summary statistics for time All Asset Types All 97.65 3.60 1.97 143.43 96.76 7.82 5.29 378.98 Non-periphery 98.33 2.16 1.45 69.10 95.63 6.60 4.67 100.16 series of individual security Periphery 96.54 4.05 2.63 40.18 94.44 5.67 3.59 47.09 UK 98.68 3.33 2.42 34.15 98.19 7.82 6.93 231.73 specific quantities. RMBS All 97.09 3.92 3.02 93.39 97.94 6.58 5.99 272.22 Non-periphery 97.36 2.58 2.42 46.59 95.59 6.11 4.22 66.38 • Time series for each asset Periphery 95.17 3.97 4.95 23.64 92.86 5.30 3.96 20.93 sub-class are further UK 99.04 3.46 2.93 23.16 98.35 6.40 7.08 184.90 CLO All 100.27 1.04 0.69 1.00 99.27 4.11 2.97 15.46 divided by whether they Non-periphery 100.01 0.00 0.62 0.14 101.33 2.71 2.50 9.29 Periphery 97.51 0.00 1.61 0.15 94.86 3.31 3.80 3.54 belong to the Non- UK 100.75 0.69 0.58 0.71 95.30 4.70 2.54 2.62 CLO-SME All 91.18 3.99 1.64 5.57 80.19 2.95 2.37 8.48 periphery, Periphery, the Non-periphery 86.81 1.45 0.35 1.96 57.09 0.23 0.21 1.04 UK, or all countries. Periphery 85.00 1.95 2.78 2.77 65.14 3.35 3.56 6.64 UK 31.35 0.21 0.60 0.84 23.42 0.60 0.43 0.79
• For each aggregation the Auto Loan All 99.07 1.12 1.05 20.52 99.58 0.54 1.11 4.45 Non-periphery 99.33 0.69 0.87 15.67 99.68 0.52 0.76 2.82 mean price, average price Periphery 98.36 1.40 1.42 3.67 98.02 0.00 2.51 0.15 UK 100.09 0.09 0.36 1.17 100.15 0.22 0.84 1.48 standard deviation, average Consumer Loan All 97.45 1.47 1.64 2.99 84.55 6.71 8.60 0.28 Non-periphery 99.17 0.33 0.77 1.16 84.55 6.71 8.60 0.28 volatility (with a window of Periphery 96.00 1.44 2.13 1.71 - - - 0.00 125 days) and average UK 101.70 0.00 0.94 0.12 - - - 0.00 Credit Card All 98.20 1.11 1.97 5.03 99.33 0.26 1.02 1.17 sample size are displayed. Non-periphery - - - 0.00 - - - 0.00 Periphery - - - 0.00 - - - 0.00 UK 98.20 1.11 1.97 5.03 99.33 0.26 1.02 1.17 HEL All 99.37 1.74 1.02 3.98 98.51 3.47 2.76 9.17 Non-periphery 96.83 1.62 0.85 1.08 97.83 1.45 1.90 2.78 Periphery - - - 0.00 84.69 0.00 4.55 0.29 UK 100.22 0.46 1.22 2.90 99.33 2.13 2.66 6.10
Note: In other cases, where sign of effect is not as expected, it reflects time period or bank/country sample selectivity as explained in note on (3/6) slide.
• The figure total, average Full criteria Relax not OTD Relax most Relax not Relax principle time series volatilities of senior tranche CMBS amount > 100m Relax all HQS and Non-HQS for all criteria Non- Non- Non- Non- Nonasset types and for RMBS HQS HQS HQS HQS HQS HQS HQS HQS HQS HQS for the four different country-groupings. All Asset All 2.32 6.64 2.58 6.54 2.80 9.72 2.76 6.50 2.37 6.66 4.97 Types • Reading across the Noncolumns, we show the periphery 1.54 6.17 1.89 5.61 1.81 12.86 1.62 6.13 1.54 6.18 3.29 result of relaxing Periphery 3.14 4.10 3.20 4.19 3.14 4.44 3.15 4.10 3.15 4.22 3.73 successively individual criteria from our HQS UK 3.25 8.54 4.27 8.43 3.77 11.31 4.85 8.44 3.38 8.56 7.09 definition.
• For example, the effect of RMBS All 3.59 7.42 4.06 7.23 4.40 11.43 3.59 7.42 3.68 7.45 6.58 relaxing the most senior Nontranche requirement is to periphery 2.57 4.99 3.17 3.92 2.76 6.69 2.57 4.96 2.56 4.97 3.77 boost the volatility of All Asset Types in All regions Periphery 5.97 4.60 5.85 4.56 5.73 4.22 5.97 4.60 5.66 4.78 5.50 by 0.48 = 2.80 - 2.32 percent. UK 4.36 8.92 6.79 8.71 5.08 15.37 4.36 8.92 4.39 8.96 8.58
Note: on periphery RMBS, see note to slide (3/6) on bank level selectivity effects in Spain.
% All Asset Types All % All Asset Types Non-periphery • The plots show the 1.8 1.6 1.6 1.4 evolution of average bid- 1.4 1.2 ask spreads of HQS and 1.2 1 1 0.8 Non-HQS for all asset 0.8 0.6 types in four different 0.6 0.4 0.4 country-groupings: all 0.2 0.2 countries, non-periphery countries, periphery
HQS Non-HQS HQS Non-HQS countries and the UK. % % All Asset Types Periphery All Asset Types UK 2.5 2.5
• Bid-ask spreads have been
2 2 estimated by Standard & 1.5 1.5 Poor’s. 1 • For instance, in May 2009 the bid-ask spread of all 0.5 0.5 non-periphery HQS assets 0 0 was approximately 0.6% of HQS Non-HQS the bond’s par value, compared to bid-ask spreads of approximately 0.8% for non-HQS assets.
• A major contribution of EBA (2014) was the analysis of the impact of different capital rules on realistic example securitisations.
• This yields results that are more relevant to the market than the calibration exercises behind the BCBS SEC-ERBA, as the RSW calibration was performed, as far as is publicly known, using stylised securitisation deals rather than actual transactions.
• Focussing on the existing Basel II approaches (formula-based SFA, IRB Ratings Based Approach (RBA) and Ratings Based Standardised Approach (RB(SA)) so as not to impinge on the work of the RSW, the EBA showed that the formula- and ratings-based approaches had become completely misaligned.
• A variety of factors contributed.
1. Rating agencies had increased the conservatism of their rating methodologies following the crisis.
2. The major agencies imposed sovereign ceiling caps on securitisation ratings.
3. As mentioned above, the rating agencies are very conservative in their evaluation of European SME backed deals.
• The net effect, documented by the EBA, is that the post-securitisation capital can easily be 5 times or more the pool capital for significant parts of the European market.
• The figure displays statistics of the Non-neutrality ratios for EDW securitisations before distribution of non-neutrality ratios and after rescaling for over 2,000 securitisation deals contained in the European Data 8.0 10th percentile Warehouse (EDW) as published by 7.0 1st quartile the EBA (2015b). 6.0 3rd quartile
• The non-neutrality ratio for a given 5.0 90th percentile securitisation under a particular
4.0 capital treatment equals the ratio of
• the capital requirement a 3.0 Non-neutrality ratio bank must meet if it holds all 2.0 the tranches in a 1.0 securitisation -
• to the capital it must Sec-IRBA Sec-IRBA, rescaled Sec-SA Sec-SA, rescaled Sec-ERBA Sec-ERBA, rescaled maintain if it owns the assets in the securitisation pool.
• The plots show the 25% and 75% quantiles (the bottom and top level of the bars) and the 10% and 90% quantiles (the extreme points on the lines).
• The quantiles are shown for before and after the EBA ‘re-scaling’ (for STS) of capital charges is performed and for the three approaches contained in BCBS 303, the SEC-IRBA, SEC-ERBA and the SEC-SA.
• The dislocation and inconsistency of the current Basel II and intended Basel III (BCBS 269 and later, finalised as 303 in December 2014) capital frameworks has been extensively explored and documented by industry studies.
• Perraudin (2014c) presents an analysis of the regulatory capital implications of different rules for the securitisation holdings of 8 major international banks.
• Using primarily US bank data on exposures to US deals, it shows that the BCBS 269 ERBA is more conservative than the SEC- IRBA and SEC-SA formulae and that, looking across tranches, the risk weights implied by the former have low correlations with the formulae-based capital.
• More pertinent to the European market, Duponcheele, Linden and Perraudin (2014) analyse 1,771 European securitisations for which public data is available, calculating risk weights under the three BCBS 269 approaches.
• Their conclusions were striking in that they showed very substantial relative conservatism of the SEC-ERBA when applied to European prime mortgage and SME deals in particular.
• In February 2015, the Commission launched its “Consultation Document on an EU framework for simple, transparent and standardised securitisation”.
• In June 2015, EBA (2015a) published proposals for a category of “Simple, Transparent and Standardised” (STS) securitisations and a suggested recalibration of the RSW’s BCBS 303 risk weight rules for this category.
• The recalibration for STS securitisations consists of halving (vis-à-vis the BCBS 303 values) the p parameter employed in both the SEC-IRBA and SEC-SA (while maintaining the floor of 0.3 in the case of the SEC-IRBA).
• The resulting SEC-SA p value of 0.5, one may note, equals the value used in the current domestic US SA approach adopted in July 2013.
• EBA (2015a) also presents a recalibration of the SEC-ERBA for STS securitisations. The effectiveness of this recalibration is open to doubt, however.
• EBA (2015a) presents calculations based on European Data Warehouse (EDW) data suggesting that SEC-ERBA risk weights are reduced by only 7% .
• Perraudin (2015b) analyses the impact of the EBA (2015a) recalibration using the same 1,771 securitisations employed by Duponcheele, Linden and Perraudin (2014) and shows that the SEC-ERBA remains prohibitively conservative for European prime mortgage and SME loan backed securitisation, especially for senior tranches.
• The final package of Basel III rules for securitisation capital was published in BCBS D374 in July 2016.
• This revised the December 2014 BCBS 303 to include less conservative capital rules for “simple, transparent and comparable” securitisations.
Simplicity refers to the homogeneity of underlying assets with simple characteristics, and a transaction structure that is not overly complex. Simplicity
Criteria for transparency provide investors with sufficient information on the underlying assets, the structure of the transaction and the parties to the transaction, Transparency promoting a more comprehensive and thorough understanding of the risks involved. The manner in which the information is available should not hinder transparency, but instead support investors in their assessment.
Criteria promoting comparability could assist investors in their understanding of such investments and enable more straightforward comparison across securitisation Comparability products within an asset class. Importantly, they should appropriately take into account differences across jurisdictions.
• The European version of STC is called Simple, Transparent and Standardised
1. Originators and Sponsors may notify ESMA that a transaction is “STS” if both of them and the SPV are established in the Union and the securitisation meets the STS-securitisation criteria. The notification is published on the ESMA website.
2. For non-ABCP securitisations, to be STS, it must involve:
3. Unconditional and unencumbered transfer of ownership of a homogenous pool of assets to the SPV.
4. No “originate to distribute-model” in that loans cannot be entered into in the first place only for sale and repackaging.
5. No transferred assets may be in default and all must have at least one payment.
6. Interest rate and currency risks arising from the securitisation must be swapped and multiple legal aspects must be fully disclosed with responsibilities specified.
7. Statistical data and liability cash flow models must be available.
Background and rationale for the criteria related • Referenced interest payments (Article 21(3)) to simplicity • Requirements in case of enforcement or delivery of an
• True sale, assignment or transfer with the same legal acceleration notice (Article 21(4)) effect, representations and warranties (Article 20(1)- • Non-sequential priority of payments (Article 21(5)) (6)) • Early amortisation provisions/triggers for termination of
• Eligibility criteria for the underlying exposures, active the revolving period (Article 21(6)) portfolio management (Article 20(7)) • Transaction documentation (Article 21(7))
• Homogeneity, obligations of the underlying exposures, • Expertise of the servicer (Article 21(8)) periodic payment streams, no transferable securities • Remedies and actions related to delinquency and default (Article 20(8)) of a debtor (Article 21(9))
• No resecuritisation (Article 20(9)) • Resolution of conflicts between different classes of
• Underwriting standards (Article 20(10)) investors (Article 21(10))
• No exposures in default and to credit-impaired Background and rationale for the criteria related to debtors/guarantors (Article 20(11)) transparency
• At least one payment made (Article 20(12)) • Data on historical default and loss performance (Article
• No predominant dependence on the sale of assets 22(1)) (Article 20(13)) • Verification of a sample of the underlying exposures Background and rationale for the criteria related (Article 22(2)) to standardisation • Liability cash flow model (Article 22(3))
• Risk retention (Article 21(1)) • Environmental performance of assets (Article 22(4))
• Appropriate mitigation of interest-rate and currency • Compliance with transparency requirements (Article risks (Article 21(2)) 22(5))
• KIRB is the capital charge of the underlying pool . It is is the ratio of (a) the IRB capital requirement (including the expected loss portion and, where applicable, dilution risk) for the underlying exposures in the pool to (b) the exposure amount of the pool (eg the sum of drawn amounts related to securitised exposures plus the exposure-at-default associated with undrawn commitments related to securitised exposures).
• LGD is the exposure-weighted average loss-given-default of the underlying pool
• MT is the maturity of the tranche calculated
• KSSFAKIRB is the capital requirement per unit of securitisaion exposure under the SEC-IRBA
• p is the supervisory parameter
• N is the effective number of loans in the underlying pool
• 0.3 denote the p-parameter floor
• 15% denote the risk weight floor
• The parameters A,B,C,D and E are determined according to the following look-up table.
SEC-IRBA look-up table
A B C D E Senior, granular (N>=25) 0 3.56 -1.85 0.55 0.07 Senior, non-granular (N<25) 0.11 2.61 -2.91 0.68 0.07 Wholesale Non-Senior, granular (N>=25) 0.16 2.87 -1.03 0.21 0.07 Non-Senior, non-granular (N<25) 0.22 2.35 -2.46 0.48 0.07 Senior 0 0 -7.48 0.71 0.24 Retail Non-Senior 0 0 -5.78 0.55 0.27
Source: BCBS (2014)
• For normal securitisations p= max0.3, A+ B× 1 N + C× KIRB + D× LGD+ E× MT
• For STC securitisations p= max0.3, A+ B× 1 × 0.5 N + C× KIRB + D× LGD+ E× MT
ea×u−ea×l 1 KSSFA(KIRB) = a×(l−u) , a= − p×KIRB , u= D−KIRB , l= max(A−KIRB, 0)
12.5 ifD≤KIRB, ifA≥KIRB, max 15%, KSSFAKIRB × 12.5 RW= KIRB−A D−KIRB max 15%, D−A × 12.5 + D−A × 12.5 × KSSFA(KIRB) Otℎerwise
• Under the normal method, let EADi represent theexposure−at−default associated with the ith instrument in the pool, LGDi represent the average LGD associated with all exposures to the ith obligor σi EADi σi EADi×LGDi N=[2] , LGD= σi EADi σi EADi
• Let cmdenote the share of the pool corresponding to the sum of the largest m shares. The level of m is set by each bank. If the portfolio share associated with the largest exposure, c[1], is no more than 0.03 −1 , LGD= 0.5 N= c[1] × cm + cm −c[1] m−1 × max 1 −m× c[1], 0
• If only c[1] is available and c[1] ≤0.03 N= 1 , LGD= 0.5 Source: BCBS (2014) c[1] ERBA risk weights for short-term ratings for normal securitisations
External Credit Assessment A-1/P-1 A-2/P-2 A-3/P-3 All other ratings Risk Weight 15% 50% 100% 1250%
ERBA risk weights for short-term ratings for STC securitisations External Credit Assessment A-1/P-1 A-2/P-2 A-3/P-3 All other ratings Risk Weight 10% 30% 60% 1250%
EBRA risk weights for long-term ratings EBRA risk weights for long-term ratings for STC for normal securitisations securitisations Senior Tranche Non-Senior (Thin) Tranche Senior Tranche Non-Senior (Thin) Tranche Rating Tranche Maturity (MT) Tranche Maturity (MT) Rating Tranche Maturity (MT) Tranche Maturity (MT) 1 year 5 years 1 year 5 years 1 year 5 years 1 year 5 years AAA 15% 20% 15% 70% AAA 10% 10% 15% 40% AA+ 15% 30% 15% 90% AA+ 10% 15% 15% 55% AA 25% 40% 30% 120% AA 15% 20% 15% 70% AA- 30% 45% 40% 140% AA- 15% 25% 25% 80% A+ 40% 50% 60% 160% A+ 20% 30% 35% 95% A 50% 65% 80% 180% A 30% 40% 60% 135% A- 60% 70% 120% 210% A- 35% 40% 95% 170% BBB+ 75% 90% 170% 260% BBB+ 45% 55% 150% 225% BBB 90% 105% 220% 310% BBB 55% 65% 180% 255% BBB- 120% 140% 330% 420% BBB- 70% 85% 270% 345% BB+ 140% 160% 470% 580% BB+ 120% 135% 405% 500% BB 160% 180% 620% 760% BB 135% 155% 535% 655% BB- 200% 225% 750% 860% BB- 170% 195% 645% 740% B+ 250% 280% 900% 950% B+ 225% 250% 810% 855% B 310% 340% 1050% 1050% B 280% 305% 945% 945% B- 380% 420% 1130% 1130% B- 340% 380% 1015% 1015% CCC+/CCC/CCC- 460% 505% 1250% 1250% CCC+/CCC/CCC- 415% 455% 1250% 1250% Below CCC- 1250% 1250% 1250% 1250% Below CCC- 1250% 1250% 1250% 1250%
The variable W equals the ratio of the sum of the nominal amount of delinquent underlying exposures to the nominal amount of underlying exposures.
• If the bank does know the delinquency status KA = 1 −W× KSA + W× 0.5
• If the bank does not know the delinquency status
Subpool1 wℎerewknown + EADSubpool2 wℎereWunknow KA = EADSubpool1 wℎereWknow × KA EADTotal EADTotal ea×u−ea×l 1 KSSFA(KA) = a×(l−u) , a= − p×KA , u= D−KA , l= max(A−KA, 0)
The supervisory parameter p in the context of the SEC-SA is set equal to 1 for a securitisation exposure that is not a resecuritisation exposure. The supervisory parameter p in the context of the SEC-SA is set equal to 0.5 for an exposure to an STC securitisation.
12.5 ifD≤KA, ifA≥KA, max 15%, KSSFAKA × 12.5 RW= KA−A D−KA max 15%, Otℎerwise D−A × 12.5 + D−A × 12.5 × KSSFA(KA)
The resulting risk weight is subject to a floor risk weight of 15%. Moreover, when a bank applies the SEC-SA to an unrated junior exposure in a transaction where the more senior tranches (exposures) are rated and therefore no rating can be inferred for the junior exposure, the resulting risk weight under SEC-SA for the junior unrated exposure shall not be lower than the risk weight for the next more senior rated exposure.
Source: BCBS (2014)
Risk Weights (Par Weighted Averages) Most senior tranches
• This table displays weighted averages for the Most Senior, Mezzanine and Junior tranches of three asset classes under a number of proposed regulatory approaches.
• Weighted averages are based on par values. Results are given for three securitisation Mezzanine tranches sub-sectors: RMBS, SME loan backed and Other Retail loan backed securitisations.
• All tranches considered are rated to permit comparison with RBA and SEC-ERBA. Averages are provided for two Basel II approaches, the RBA and the SFA, the three Junior tranches BCBS 303 approaches: SEC-IRBA, SEC- ERBA and SEC-SA, and for their variants following EBA (2015b) rescaling.
• See Duponcheele, Linden and Perraudin
(2014) for details on the dataset and methodologies used to determine the risk weights. Comparison of the Rescaled STS SEC-IRBA and Rescaled STS SEC-SA • This Figure displays graphically the risk weights implied by the EBA (2015b) re-scaled STS formulae-based approaches for the 1,771 tranches.
• In the upper panels of the figure, each point represents a comparison between the STS SEC- SA risk weights (shown on the vertical axis) and the STS SEC-IRBA risk weight (on the horizontal axis) for the same individual tranche.
• The left hand panel contains a scatter plot for all the tranches in our dataset while the right hand panel shows a scatter plot only for those tranches that have risk weights less than 200% under both approaches being compared, i.e. the higher credit quality segment of the market.
• The lower panels of the figure show the frequency distribution of the gap between the rescaled STS SEC-SA and STS SEC-IRBA risk weights.
Distribution of wholesale p values in SEC-IRBA
• The figure shows histograms for SEC-IRBA p values (under different assumptions) for the 211 corporate or wholesale tranches in our dataset.
• Top left shows the distribution without imposing floor of 0.3 and without EBA (2015)-style rescaling.
• Top right shows results with a 0.3 floor but no rescaling.
• Bottom left shows rescaling but no floor.
• Bottom right shows the distribution with both rescaling and a 0,3 floor.
• The wholesale pools in the European dataset generate p-values between 0.3 and 0.6. The key point to notice is that rescaling the p values (by halving) for STS rescaling, leads all p values to be at the floor of 0.3.
1. Are there any drawbacks of using an ad hoc formula like the SSFA rather than a model-based framework like the AFA?
2. What should the capital premium be in the SSFA? Is a capital premium of 50% for STC justifiable let alone 100% for non-STC?
3. Have you noticed that there is an additional non-neutrality in the rules in that securitisation capital unlike whole loan Basel capital adds in EL and is not UL based?
4. What are the advantages and disadvantages of distinguishing between STC and non-STC securitisations? Was it an advisable step for regulators to take?
5. What challenges may European banks face in implementing the SEC- IRBA?
1. Introduction to securitisation
2. Risk analysis and pricing of securitisations
3. Regulation of securitisations
4. Practical exercise 1: PURA RTS
5. Role of the ratings agencies
6. Liquidity of securitisations
7. Market drivers and motives for using securitizations
8. Practical exercise 2: Optimal Tranching
• In June 2018, the EBA issued draft Regulatory Technical Standards on what European banks must do in order to employ the SEC-IRBA.
• The framework described build on the permissions already in the CRR for calculation of KIRB in the context of the Purchased Receivables Approach (PURA)
• In this exercise, we shall consider what the EBA should include in the RTS particularly as relates to modellers.
• We shall focus on those articles in the draft RTS that appear most material for quantitative modelling:
1. Article 5 on “General conditions for risk differentiation”
2. Article 9 on “Requirements on data”
• We shall go through some material on the issues and then discuss what additional clarification may be advisable.
Confidential © Risk Control Limited 2020 105
• Clarifying what banks must do to implement the SEC-IRBA is very important:
1. To level the playing field with non-EU banks
2. To ensure bank capital equals that envisaged by Basel
• It has been doubtful whether European banks would be able to employ the SEC-IRBA for securitisation deals other than those for which they themselves are the originators.
• The reason is that national regulators, even within Europe, vary significantly in how strictly they enforce the Basel IRBA data and modelling standards.
• At various stages through the development of the Basel 3 securitisation capital rules, regulators have suggested that KIRB for securitisation capital purposes might be estimated using proxy data.
• But the nature of possible relaxation in data standards has not been clarified as they relate to securitisation activities.
• And no guidance has been given for the specific IRB modelling challenges has been available.
Confidential © Risk Control Limited 2020 106
• Key take-aways for modelers from the draft RTS are:
1. The usual data hierarchy is reversed in that banks should start with data close to the transaction pool in question and should regard internal bank data only as a proxy.
2. Banks should explicitly take account of the under-writing standards of the originators of the pool exposures.
3. Top down and bottom up modelling approaches are feasible but in top down approaches in particular no guidance is provided on the degree to which data may deviate from standard Basel definitions.
4. A central part of IRBA modelling in the securitisation context is the combination of estimates from different data sources. This should be acknowledged and some guidance given as to approaches.
Confidential © Risk Control Limited 2020 107
• In this section, we start by discussing in general terms the challenges faced by banks in PURA modelling.
• Banks likely to use the PURA framework fall into different categories depending on:
1. Whether they wish to apply the framework to bank originated or non-bank originated assets
2. Whether they wish to apply the framework to multiple national markets or have a narrow national focus
• The distinction between bank and non-bank assets is important because the nature of the data in the latter case is more difficult to square with standard Basel data and modelling standards
• The distinction between national and multi-market applications is important because markets vary substantially across countries and data sources are more or less complete in different jurisdictions
Confidential © Risk Control Limited 2020 108
• Article 5 states that: “When assigning exposures to grades or pools, institutions shall consider the originator’s underwriting standards and the servicer’s recovery practices and servicing standards as risk drivers, unless they use different calibration segments for different originators and different servicers in quantifying the risk parameters associated with those grades or pools.”
• Such a requirement that the under-writing standards of the originator be explicitly considered is challenging.
• Purchasers of bank loan pools are well aware that the credit performance of loan portfolios depends as much on underwriting standards as on the stage of the business cycle.
• But, observing differences in such standards or being able to measure them statistically is not straightforward.
Confidential © Risk Control Limited 2020 109
• Article 9 states that: “1. Where the securitised exposures and the obligors of those exposures were, before the transfer of such exposures to the SSPE, not obligors or exposures of the institution calculating KIRB, instead of the requirement of representativeness of the data used for model development in accordance with Article 174(c) of Regulation (EU) No 575/2013, the representativeness of the data shall be assessed in relation to the securitised exposures.”
• Also, it states that “2. Instead of the requirement in the first sentence of Article 180(2) (c) of Regulation (EU) No 575/2013, institutions shall regard data related to the securitised exposures as the primary source of information for estimating loss characteristics.”
• This article effectively reverses the usual data hierarchy encountered in IRB modelling.
• In developing conventional IRB models for a bank’s on loan book, internal data are preferred and external data are only applicable if internal data are scarce.
• In the context of PuRA, the EBA is emphasises the need to rely, if these are available, on external data that is closely comparable to the pool under consideration.
Confidential © Risk Control Limited 2020 110
• PuRA (as set out in the CRR Amendment • These are important relaxations in data
(2017) and clarified in the RTS) allows and modelling requirements for banks to use certain IRB modelling receivables from non-financial originators approaches that are not generally available for which data may not be recorded in in a standard IRB context. ways that are standard in the banking
• Specifically, a bank may employ a Retail industry. Standard approach for corporate • For example, loss data may be stored purchased receivables that satisfy certain rather than default events and recoveries. requirements. • It may also be somewhat more
• Under the Retail Standard (also called the straightforward to calculate pool level PDs Top Down approach in Basel documents), and LGDs rather than employing banks may calculate PDs for homogeneous regression-style models to predict defaults loan pools rather than by implementing a and mean LGDs at a loan level.
• statistical default prediction model on a However, if conventional loan level loan by loan basis. securitisation pool data is available then
• Also, a bank may estimate a pool PD or the challenge of implementing loan-level LGD by using one of these two quantities regressions model is not major and so in conjunction with an estimate of a pool these concessions are not so material. level losses.
Confidential © Risk Control Limited 2020 111
• Different IRB exercises, particularly those that rely on proxy data, require some combination of data. But the task of combining datasets becomes a central concern in the case of PuRA.
• The reason is that the usual data IRB hierarchy is inverted with the key data for calibration consisting of information about exposures closely related to the loan pool for which one seeks to estimate KIRB.
• This means that instead of having a stable data source (such as a large volume of historical data on loans the bank has originated itself or some database provided by an external data vendor or data consortium), the modellers must use different datasets whenever they wish to calculate capital for a particular pool.
• Thus, a PuRA model should be seen as a set of methodologies and procedures that are applied in a dynamic way to multiple deals as they arise and reapplied as long as the bank maintains its exposure to the positions in question.
• Such an approach must be sufficiently flexible that it is practical to apply to multiple, somewhat heterogeneous deals as they are presented to the bank.
• Yet, it must be sufficiently precise in formulation that regulators can be confident that the investor bank is approaching its securitisation risk in an orderly and prudent manner.
Confidential © Risk Control Limited 2020 112
• For this ‘stable’ external
• The figure shows the data data, a distinction may be hierarchy that we envisage made between data from would actually apply for a bank Deal data different originators (source implementing a PuRA model.
1. Pool loan data
• At the bottom of the hierarchy is 3) and data on loans issued source 4 which consists of data by the originator of the deal on loans the bank has originated in question (source 2). itself. Above that, we expect that
• Lastly and at the top of the the bank would access a ‘stable’ hierarchy is source 1 Database on External Loan source of external securitisation Information consisting of data directly pool data.
3. Data for relevant for the deal in
2. Data for the
• This might take the form of loan other same question. level from the European Data originator originators
• If the loans are newly issued, Warehouse (ED). performance data of the
• In some jurisdictions such as the Data hierarchy actual deal loans will not be UK, substantial volumes of data may be obtained from issuer available but the originator websites. Bank’s Internal Database may possibly be able to
• Also, data might be sought from 4. Investor bank data supply data on closely other data providers like Intex. comparable loans (which could be used in addition to the data from source 3).
Confidential © Risk Control Limited 2020 113
• Given multiple datasets, the issue arises how in practice may a bank combine the information they each yield?
• One possibility would be to pool data from multiple sources. If this is done without some weighting in the combination will place a somewhat arbitrary emphasis on the different data sources and the results of the weighting will be opaque.
• Potentially, models or forecasts may be combined using a formal statistical approach.
• Data is combined in some well-known area of risk management such as in the context of operational risk modelling.
• Typically, data from a small volume of internal loss observations is combined with a dataset obtained from a consortium of financial institutions.
• Comparable methods are required in a PuRA application.
Confidential © Risk Control Limited 2020 114
Risk Control’s response to the RTS consultation briefly set out a possible approach.
Confidential © Risk Control Limited 2020 115
Applying this approach to PURA could also meet EBA 2017 guidelines requirements
Confidential © Risk Control Limited 2020 116
• Article 5 of the EBA draft RTS indicates that banks should reflect in their modelling variation in underwriting standards.
• This is challenging as empirical analysis of the effects on credit quality of underlying standards is limited.
• Some academic studies have examined the issue (see O’Keefe, Olin and Richardson (2003), Black, Chu, Cohen and Nichols (2012), Dell’Ariccia and Marquez (2006), Asiedu, Freeman and Nti-Addae (2012), Demyanyk and Van Hemert (2009) and An, Deng, Rosenblatt and Yao (2011)).
• Official publications have focussed on underwriting standards. Financial Stability Board (2011) provides a thematic review of residential mortgage underwriting and origination practices. Subsequently, the FSB published a principles-based framework for sound underwriting practices. The Office of the Comptroller of the Currency (OCC) conducts annual surveys and assessments of credit underwriting standards and practices.
• None of these papers provides what is necessary for PuRA modelling, however, which is a systematic analysis of how loans with identical performances vary in credit performance across countries, banks and origination years.
Confidential © Risk Control Limited 2020 117
• Here, we sketch how, using the • Differences in the average loan performance framework described in Section 3, we (in PD or LGD terms) for a given set of loans would go about analysing this issue. holding the right hand side variables
• Given an extensive dataset of loan pool constant, then reveals how much data, one may estimate scoring models underwriting standards and macroeconomic by country, bank, deal and origination conditions vary across banks. year. • Variation across banks may be identified
• National markets are so different that it directly as an underwriting standard effect. is sensible to estimate models country by • Variation across time is more complex to country. Within any given country, one interpret as it could reflect cyclical changes may then estimate models by originator. or changes in underwriting standards over
• By including right hand side variables time. within a logit regression (for the PDs) or • Some judgment may be necessary to non-linear regression for the LGDs, one untangle these two influences. may allow for the fact that the • On the basis of the estimates and judgments, composition of loans differs across we would propose to develop bank and banks and years. origination-year specific scaling factors for PDs.
• These would then be used to set the bias adjustments in equation (18).
Confidential © Risk Control Limited 2020 118
• It is most straightforward to meet the data standards in a bottom up approach so this may be preferable for bank originated exposures
• Here, we illustrate what would have to be done to implement such a model
• We estimate PDs and LGDs for mortgage loans using data from the European Data Warehouse.
• The exercise is instructive as it shows what a bank may have to do to satisfy the PuRA rules and what additional guidance from the EBA may be helpful to industry modellers.
• The methodology we follow in implementing the model is similar to many IRB models that we have observed in use in major banks.
• We have implemented this methodology in software that can be conveniently applied to large datasets of loan credit histories.
Confidential © Risk Control Limited 2020 119
• Let us review the steps involved in a typical IRB modelling exercise in order to understand the challenges involved in doing so for large numbers of different datasets in a dynamic way (as is required by PuRA).
• The steps in our methodology are as follows.
Confidential © Risk Control Limited 2020 120
• Number of performing loans at the beginning of each year • Number of defaulted loans in each year
Confidential © Risk Control Limited 2020 121
• We estimate models pooling data from each country
Confidential © Risk Control Limited 2020 122
• We calculate PD estimates for a set of countries using this methodology.
BE DE ES FR IE IT PT UK
BE 100 98 65 9 87 34 7 3 89
DE 98 100 7 0 15 89 40 7 8 93
ES 65 7 0 100 7 7 92 92 99 90
FR 9 15 7 7 100 52 96 69 46
IE 87 89 92 52 100 7 2 96 98
IT 34 40 92 96 7 2 100 86 67
PT 7 3 7 8 99 69 96 86 100 94
UK 89 93 90 46 98 67 94 100
Mean PDs 0.13% 0.06% 1.94% 0.46% 0.49% 1.56% 1.69% 0.27 %
Confidential © Risk Control Limited 2020 123
Caja
• Model Rural de parameters by Caja Banco de Granada, ES Bancaja Madrid Valencia S.C.C. BBVA ES-deal bank LTV Ratio 0.04 0.04 0.05 0.05 0.05 0.03 0.001 Debt to Income Ratio 0.08 0.07 0.16 0.07 0.03 0.02 -0.11 Smoothed Odds Ratio of Loan Origination Year 0.49 1 1.17 0.8 0.7 1 1.47 0.83 Constant 7 .58 7 .69 11 7 .48 6.55 8.09 6.97
Caja
• PD estimates Rural de by bank Caja Banco de Granada, ES Bancaja Madrid Valencia S.C.C. BBVA ES-deal ES 100 66 90 84 88 83 35 Bancaja 66 100 7 4 58 84 54 67 Caja Madrid 90 7 4 100 85 94 90 41 Banco de Valencia 84 58 85 100 7 8 7 4 14
Caja Rural de Granada, S.C.C. 88 84 94 7 8 100 87 54 BBVA 83 54 90 7 4 87 100 36 ES-deal 35 67 41 14 54 36 100 Mean PDs 1.67 % 2.05% 0.23% 2.7 9% 6.97 % 1.7 5% 0.26%
Confidential © Risk Control Limited 2020 124
• Top down approaches will often be necessary for certain pools, in particular non-bank receivables because exposure level data may not be available and data may be recorded as arrears rates and loss rates
• The general messages of earlier sections will still apply:
1. The data hierarchy is inverted
2. Combining data sources is a central issue
3. Allowing for underwriting standards is key
• In this case, the major challenge is to infer PDs from time series of numbers of loans/receivables in different arrears buckets
• Basel requires that PDs be estimated by tracking a set of loans that are not in default at a given moment and check whether they have been more than in arrears for a period of more than 90 days (or otherwise have been categorised as in default) within the following year
• LGDs estimates should be based on the same loans employed in the PD estimation
Confidential © Risk Control Limited 2020 125
• Here, we set out techniques for inferring PDs from time series observations of the number of loans in different arrears buckets
• The approach uses transition matrices to unscramble the dynamics of movements between the different arrears buckets.
• From the figure below, one may observe that loans in a particular arrears category (i.e., some range of days overdue) either “cure” in that they become performing or “roll” in that they move into the next category or bucket of arrears (corresponding to a longer period overdue).
• Loans in the 90-180 days past due bucket may remain in this bucket (since the bucket exceeds a single month). The >180 days overdue bucket is assumed to be absorbing.
Confidential © Risk Control Limited 2020 126
• The figure shows the rates at which NPLs move • One may fit the transition matrix using between the 6 categories corresponding to aggregate data at some frequency (monthly “performing” and non-performing for different or quarterly) for individual pools or numbers of days. originator datasets.
• The parameters c1 to c5 represent cure rates, i.e., the • To do this, the vector of loan values in each rates at which NPLs become Performing Loans in the bucket for one quarter is multiplied on the next monthly period. right by the third power of the transition
• The roll rates denoted 1-c1, 1-c2, 1-c3, 1-c4 and r5 matrix shown in the figure, to forecast the represent the rates at which NPLs migrate over a arrears breakdown for the next quarter. month to the next range of days overdue. • For each quarter, this forecast is compared
• Loans in the 90-180 days past due bucket may remain to the actual value, and values of c1, c2, c3, in this bucket (since the bucket exceeds a single c4, c5 and r5 are chosen to minimize the month). The >180 days overdue bucket is assumed to sum of the squared residuals. be absorbing.
Confidential © Risk Control Limited 2020 127
1. Consider your general attitude to what the EBA is trying to achieve. Do you believe that there should be concessions in IRBA standards so that calculating KIRB to serve as an input to the SEC- IRBA is more straightforward? (In this context, be aware that US regulators have authorised US banks to develop elaborate frameworks for estimating KIRB for SEC-IRBA purposes.)
2. The options for relaxation of the standards include the use of top-down modelling as ratings agencies typically do for measuring movements between different arrears buckets. It is hard to achieve strict adherence to Basel standards in this because the data consists of fractions of pools in different buckets rather than loan level information about loans that are performing and then data on whether they have been more than 90 days overdue within the following year. Should clarification on top-down modelling be provided?
3. The EBA’s emphasis on making allowance for the underwriting standards of the loan originator appears reasonable but raises the bar for modelling. But is it sensible if the objective is to encourage use of the SEC-IRBA?
4. Does it matter if the EBA does not fully clarify what European banks must do to access the SEC- IRBA? Might it be better to allow practices to emerge as banks and supervisors become familiar with their use in practice?
Confidential © Risk Control Limited 2020 128
• We recognise that, by their nature, RTS are concise statements of regulatory requirements placed on banks implementing regulatory approaches and do not constitute guidelines
• Nevertheless, we believe that the RTS should more directly reflect the key modelling challenges raised by
1. the inverted hierarchy,
2. the need to allow for originator standards, sampling error and data quality limitations
3. the fact that PURA will be applied both to bank and non-bank securitisation pools for which very different data is likely to be available
• On 1, the RTS should clearly state that a PURA model is a scoring methodology o that is applicable in a dynamic way to individual deal pools o that may appropriately combine data from different sources o that may involve a new estimation for individual deals
• On 2, the RTS should state that these may be addressed through a combination of data-driven exercises and prudent judgment
• On 3, the RTS should clarify that models based on loan level information and aggregate arrears data are acceptable with appropriate margins of conservatism
Confidential © Risk Control Limited 2020 129
Category Article Text Default definition 178(1)(b) “the obligor is past due more than 90 days on any material credit obligation to the institution, the parent undertaking or any of its subsidiaries. Competent authorities may replace the 90 days with 180 days for exposures secured by residential property or SME commercial immovable property in the retail exposure class, as well as exposures to public sector entities…” 178(4) “Institutions that use external data that is not itself consistent with the definition of default laid down in paragraph 1, shall make appropriate adjustments to achieve broad equivalence with the definition of default.”
Representativeness 174(c) “the data used to build the model shall be representative of the population of the institution's actual obligors or exposures” 179(2)(b) “the pool is representative of the portfolio for which the pooled data is used” Comprehensiveness 179(1)(a) “an institution's own estimates of the risk parameters PD, LGD, conversion factor and EL shall incorporate all relevant data, information and methods…” 180 “For purchased retail receivables, institutions may use external and internal reference data. Institutions shall use all relevant data sources as points of comparison.”
Category Article Text Default definition 178(1)(b) “the obligor is past due more than 90 days on any material credit obligation to the institution, the parent undertaking or any of its subsidiaries. Competent authorities may replace the 90 days with 180 days for exposures secured by residential property or SME commercial immovable property in the retail exposure class, as well as exposures to public sector entities…” 178(4) “Institutions that use external data that is not itself consistent with the definition of default … shall make appropriate adjustments to achieve broad equivalence with the definition of default.” Length of data 181(1)(j) “for exposures to corporates, institutions and central governments and central banks, estimates of LGD shall be based on data over a minimum of five years, increasing by one year each year after implementation until a minimum of seven years is reached, for at least one data source...” 181 “For retail exposures, estimates of LGD shall be based on data over a minimum of five years…. Subject to the permission of the competent authorities, institutions may use, when they implement the IRB Approach, relevant data covering a period of two years. The period to be covered shall increase by one year each year until relevant data cover a period of five years.”
Representativeness 174(c) “the data used to build the model shall be representative of the population of the institution's actual obligors or exposures”
179(2)(b) “the pool is representative of the portfolio for which the pooled data is used” Comprehensiveness 179(1)(a) “an institution's own estimates of the risk parameters PD, LGD, conversion factor and EL shall incorporate all relevant data, information and methods….”
181(1)(a) “institutions shall estimate LGDs by facility grade or pool on the basis of the average realised LGDs by facility grade or pool using all observed defaults within the data sources (default weighted average)”
181(2)(c) “For purchased retail receivables use external and internal reference data to estimate LGDs…”
1. Introduction to securitisation
2. Risk analysis and pricing of securitisations
3. Regulation of securitisations
4. Practical exercise 1: PURA RTS
5. Role of the ratings agencies
6. Liquidity of securitisations
7. Market drivers and motives for using securitizations
8. Practical exercise 2: Optimal Tranching
Europe US Aaa/AAA 50.16% 33.07% Aa/AA 30.94% 4.75% A/A 11.11% 5.66% Baa/BBB 2.99% 7.87% Ba/BB 2.28% 5.26% B/B 1.24% 5.16% Caa/CCC 0.69% 20.20% Ca/CC 0.33% 11.79% C/C 0.25% 6.25% Total 100.00% 100.00%
Outstandings by Moody's Investors Service Ratings: Q3 2018 (as a percentage of total Moody's rated securitisations)
Source: Macquarie, Moody’s Investors Service, S&P Global Ratings
• A large fraction of the rated universe of US securitisations remains in distress (38% are CCC or below).
• European securitisations include a higher fraction in AAA and particularly AA rating than US.
DBRS Fitch Ratings 2018 (Q1 2017 (Q1 2017 (Q1 2018 (Q1 2017 (Q1 2017 (Q1
• Ratings agencies have to Q3) to Q3) to Q4) to Q3) to Q3) to Q4) France 10/2 13/0 20/0 France 11/10 8/3 16/7 recently tended to Germany 24/0 18/0 25/0 Germany 5/7 12/24 19/33 upgrade securitisation Italy 52/10 52/8 66/8 Italy 45/4 39/132 42/132 ratings. Netherlands 10/0 1/0 2/4 Netherlands 54/6 14/46 30/47 Spain 54/0 24/5 29/5 Spain 238/13 90/29 105/34 • Moody’s has been UK 3/22 0/1 19/4 UK 130/21 254/29 314/54 particularly bullish. Multinational 25/0 12/14 19/14 Multinational 4/0 8/0 8/0
• S&P has revised up European Total 178/34 120/28 180/35 European Total 550/196 447/314 572/359 US 1286/47 1449/330 1801/354 US 2504/1053 1535/1600 3124/2242 European ratings more than US ratings. Moody's Investors Service S&P Global Ratings
• Agencies have taken 2018 (Q1 2017 (Q1 2017 (Q1 2018 (Q1 2017 (Q1 2017 (Q1 to Q3) to Q3) to Q4) to Q3) to Q3) to Q4) different approaches to markets in some cases. pessimistic about Italy in 2017 and DBRS was 2018.
DBRS Fitch Ratings* 2018 (Q1 2017 (Q1 2017 (Q1 2018 (Q1 2017 (Q1 2017 (Q1 to Q3) to Q3) to Q4) to Q3) to Q3) to Q4) Auto 25/26 26/0 38/0 Auto 19/3 16/7 25/7 CDO 17/4 23/13 33/13 Credit Card 3/0 3/0 13/0 CMBS 18/1 0/6 0/10 Other ABS 51/128 26/67 35/70 Credit Card 22/2 21/2 31/2 CDO 79/6 82/37 130/38 RMBS (prime) 51/1 41/6 65/9 CMBS 7/10 22/39 22/53 RMBS (non-prime) 6/0 4/1 7/1 RMBS (prime) 301/25 99/149 140/157 Other ABS 38/0 5/0 6/0 RMBS (non-prime) 68/4 185/6 191/25 Total 177/34 120/28 180/35 Other RMBS 22/0 14/9 16/9 Total 550/196 447/314 572/359 *The European totals may not match the constituent parts as a small number of European RMBS transactions are not categorised as either Prime or Nonconforming.
S&P Global Ratings Moody's Investors Service
2018 (Q1 2017 (Q1 2017 (Q1 2018 (Q1 2017 (Q1 2017 (Q1 to Q3) to Q3) to Q4) to Q3) to Q3) to Q4) Auto 18/2 11/6 20/14 Auto 16/0 11/0 12/0 CDO 18/0 121/4 251/5 CDO 40/14 198/39 218/47 CMBS 1/1 2/23 7/38 CMBS 9/23 9/56 14/58 Credit Card 0/0 2/0 4/0 Credit Card 0/0 0/0 0/0 RMBS (prime) 197/6 162/15 295/65 RMBS (prime) 214/9 112/16 204/21 RMBS (non-prime) 40/4 144/5 326/11 RMBS (subprime/non-conforming) 93/5 98/4 296/4 Total 274/27 442/53 903/133 Total 372/51 428/115 744/130
Source: DBRS, Fitch Ratings, Moody’s Investors Service, S&P Global Ratings
DBRS Fitch Ratings 2018 (Q1 2017 (Q1 2017 (Q1 2018 (Q1 2017 (Q1 2017 (Q1 to Q3) to Q3) to Q4) to Q3) to Q3) to Q4) Auto 190/1 141/0 161/0 Auto 91/0 71/0 105/0 CDO 30/0 24/28 33/43 Credit Card 0/0 11/0 11/0 CMBS 49/23 115/281 160/284 Other ABS 39/34 125/88 170/119 Credit Card 30/0 10/0 10/0 CDO 110/43 139/22 149/24 RMBS 873/22 1085/15 1350/21 CMBS 177/143 174/173 204/209 Other ABS 114/1 74/6 87/6 RMBS (prime) 245/384 206/718 221/771 Total 1286/47 1449/330 1801/354 RMBS (subprime) 559/149 28/262 1129/662 Other RMBS 1283/300 781/337 1135/457 Total 2504/1053 1535/1600 3124/2242
Moody's Investors Service S&P Global Ratings 2018 (Q1 2017 (Q1 2017 (Q1 2018 (Q1 2017 (Q1 2017 (Q1 to Q3) to Q3) to Q4) to Q3) to Q3) to Q4) Auto 117/0 164/0 318/0 Auto 229/1 245/0 319/0 CDO 48/20 258/12 426/22 CDO 57/20 218/27 252/37 CMBS 101/38 228/115 393/232 CMBS 103/82 267/116 328/153 Credit Card 0/0 0/0 0/0 Credit Card 17/0 0/0 12/0 RMBS 1180/226 1246/91 2221/203 RMBS (prime) 634/428 186/591 229/691 Total 1446/284 1896/218 3358/457 RMBS (subprime/non-conforming) 1106/1177 174/248 286/336 Source: DBRS, Fitch Ratings, Moody’s Investors Service, S&P Total 2146/1708 1090/982 1426/1217 Global Ratings
1. Which securitisation market appears the heathier post crisis?
2. Do you see any evidence of lower reliance on ratings in some market versus others?
3. Do the ratings agency judgments evident in recent downgrades and upgrades correspond to what you would have thought based on your knowledge of economic developments in different sectors and countries?
• Here we consider the role that agency ratings have played in the securitisation market particularly in a regulatory context.
• Key points we wish to emphasise are:
1. Extreme procyclicality of ratings and sovereign ceilings have created chaos for bank capital management since the crisis
2. Regulatory developments immediately following the crisis reinforced the role of agency ratings in securitisation capital contrary to prominent policy statements made by European regulators
3. Subsequently, the European regulators backed away from this, actually deviating from Basel in the hierarchy of securitisation capital approaches
1. G20 meeting in Toronto in June 2010 which stated: “We committed to reduce reliance on external ratings in rules and regulations. We acknowledged the work underway at the BCBS to address adverse incentives arising from the use of external ratings in the regulatory capital framework, and at the FSB to develop general principles to reduce authorities’ and financial institutions’ reliance on external ratings. [..]” (Appendix II, Paragraph 27)
2. The Dodd-Frank act in the US states (section 931(5)) that inaccurate credit ratings on structured financial products “contributed significantly to the mismanagement of risks by financial institutions and investors, which in turn adversely impacted the health of the economy in the United States and around the world.”
3. Dodd-Frank requires US regulatory agencies to remove dependence on external ratings from their rules and regulations
4. European regulators have adopted the objective of reducing reliance on external ratings in financial regulation substantially within Europe
• In May 2013 the European Parliament and Council adopted regulation on credit rating agencies which included reduction of reliance on credit ratings as a stated aim
• Article 6 of the May regulation states: “The Union is working towards reviewing, at a first stage, whether any references to credit ratings in Union law trigger or have the potential to trigger sole or mechanistic reliance on such credit ratings and, at a second stage, all references to credit ratings for regulatory purposes with a view to deleting them by 2020, provided that appropriate alternatives to credit risk assessment are identified and implemented.”
• In February 2014, the Joint Committee of the European Supervisory Authorities (EBA, ESMA and EIOPA - ESAs) published on “Mechanistic references to credit ratings” which said:
a) “Further work is needed however, especially in the international context (most notably, the Basel Committee Task Force on the Standardised Approach) to find alternatives for the mapping to external ratings in the standardised approach and the mapping for securitisation exposures
b) EBA, ESMA and EIOPA will take into account the reliance on external ratings when developing the ITS on ECAIs mapping required by Regulation (EU) No 575/201313”
• BCBS 269 in December 2014 streamlined the securitisation framework to a single hierarchy based on three approaches(*): SSFA - IRBA
1. The proposals encouraged banks investing in third party securitisation ERBA to use the SEC IRBA whenever possible, provided they had internal modelling approval; SSFA - SA
2. This was followed by the SEC ERBA Most European banks investing in
• third party securitisation will have to The pattern of extending reliance on use the SEC ERBA ratings was evident in other aspects of financial regulation in Europe:
3. This creates a regional bias as US banks are not allowed to use external 1. Liquidity Coverage Ratio (LCR) criteria includes ratings criteria. ratings for regulatory purposes and will use the SEC IRBA or SEC SA. 2. Proposals for Solvency II Category A (*) The Internal Assessment Approach (IAA) has been securitisations include ratings criteria retained for unrated ABCP exposures, subject to regulators’ (even if relatively undemanding) approval
3. Proposals for Money Market Fund regulations
• The background to the G20 resolution and the consequent change in the direction of US and European regulation is the major debate on why ratings agencies failed to foresee the crisis in sub-prime mortgage lending
• A common view is that the agencies contributed to the crisis by providing over-optimistic credit assessments of securitisations used to finance subprime lending
• Much of the academic analysis has focused on the incentives ratings agencies faced to offer over-optimistic credit assessments
• Ratings agencies switched in the 1970s from a business model in which ratings were paid for by investor subscriptions to one in which issuers paid to secure a rating
• Partnoy (2009) argues that the progressively wider use of ratings for regulatory purposes allowed a small group of ratings agencies to share a quasi-monopoly rent from providing regulatory “dispensations” and that this diverted them from their traditional role of providing expert opinions on credit
• As the main rationale of ratings shifted from credit evaluations (aimed at investors) to regulatory dispensations (aimed at regulated issuers and regulated investors), the incentives for agencies to focus narrowly on accurately assessing credit quality diminished
• Kisgen and Stahan (2010) provide empirical support for this view, demonstrating that the gain to issuers in obtaining a higher rating was a significant lowering of the spread
• Bolton, Shapiro and Freixas (2012) and Mathis, McAndrews and Rochet (2009) analyse the incentives of agencies to attract business by over-stating credit quality
• He, Qian, and Strahan (2011) present empirical evidence consistent with this point The incentive for agencies to rate generously was probably more intense in the field of structured product ratings than in traditional corporate ratings
• Securitisation ratings were a rapidly expanding and highly lucrative business in the run up to the crisis, in which the agencies were scrambling to gain market share
• Fitch was a more credible challenger to the two established ratings agencies in securitisation ratings than it was in the more stable area of corporate ratings and so competitive pressures were greater
• This may have diluted rating agency incentives to rate securitisations cautiously, especially in the largest securitisation market based on US residential mortgages
1. We focus more here on a critique of agencies since the crisis.
2. Struggling to restore their reputation, agencies have adopted sudden and drastic changes in methodology that have imparted an extreme form of procyclicality to securitisation ratings
3. Absent changes in methodology, the operation of caps and triggers included by agencies in their ratings evaluations to allow for transfer, convertibility and counterparty risk have had undesirable consequences particularly for banks located in unfavoured countries.
4. This caused major problems for securitisation markets in European periphery countries that suffered sovereign downgrades
5. The agencies’ practices in reviewing securitisation ratings (with intermittent and unsystematic surveillance) are not compatible with the frequency of capital calculations
6. The complexity and lack of transparency in structured product ratings, uncertainty about the agencies’ future ratings policies, inconsistency between rating agencies’ and regulators’ evaluations of risk hampered the recovery of the market
Moody’s 1-yr downgrade and upgrade rates on global CLOs
100%
• Ratings agencies made wholesale
80% changes in ratings post the crisis by adopting changes in methodology 60%
• These seem, in some cases, to have 40% been managerial decisions rather 20% than the result of new information 0% Jan-07 Jul-07 Jan-08 Jul-08 Jan-09 Jul-09 Jan-10 Jul-10 Jan-11 Jul-11 Jan-12 Jul-12
• An example is the stresses that 1-yr Downgrade Rate 1-yr Upgrade Rate Moody’s adopted for CLOs in 2009 Source: BNP Paribas and Moody’s.
• These resulted in a wave of downgrades
• The point here is not that ratings agencies
• The agency withdrew the stress in should refrain from employing new data or 2011 with no fanfare or explanation the best and latest techniques for forecasting credit market outcomes
• The consequence was a wave of upgrades • It is more that apparently arbitrary reactions to a crisis situation by ratings agencies may produce very substantial fluctuations in bank capital with little transparency as to the evidence that justifies such discrete (and, as it turned out, contrary) reactions
• Sovereign ratings ceilings for European
RMBS Ratings securitisation tranches generated wide- Distributions spread downgrades in entire country-specific sub-sections of the securitisation market in recent years
• The policies followed by ratings agencies in imposing sovereign ceilings on securitisation ratings are complex and apparently arbitrary
• Fitch imposes an absolute rule that the rating of a securitisation tranche cannot be more than 4 notches above the rating of the
• The link may reflect considerations of corresponding sovereign convertibility, reduced chances of a bailout or
• Moody’s methodology is less clear cut in that general macroeconomic correlations between the maximum gap between sovereign and sovereign default and pool performance structured product ratings is more variable
• Convertibility is much less relevant for a local
• It is not clear from rating agency bank investing in local securitisations documentation exactly how reduced credit
• Reduced chances of a bailout does not appear a standing of a sovereign affects the rating of relevant factor for regulatory capital. Should securitisations within the corresponding general correlation between sovereign default jurisdiction and pool performance justifies a hard link like a sovereign ceiling?
• The fact that ratings (and hence capital) changes occur both because of alterations in credit quality and other issues such as sovereign ceilings and methodology changes serves to reduce transparency
• Apart from US RMBS, most securitisations downgrades in recent years have occurred for reasons other than collateral performance, such as counterparty criteria, methodology changes, and sovereign linkage
• When ratings criteria become so variable that they predominate in the reasons for ratings actions, the very meaning of a rating - i.e. the risk it purports to signify – becomes unclear
Q3 2013 Italian RMBS Ratings
Ratings Adjusted for Sovereign and Counter-Party Effects Current Rating Distribution 1.5% 0.0% 1.5% 3.5% 0.0% 3.5% 0.0% 1.0% 1.5% AAA AAA 10.9% AA AA 18.8% 46.0% 48.5% A 15.8% A
BBB BBB
BB BB 24.7% 19.8% B B
CCC CCC
D D
• The relative risk measure from ratings agencies is sometimes not compatible with the risk measure of policy makers and regulators
– For example, a portfolio of SME exposures has a risk weight of 75% compared to 100% for a portfolio of BBB/BB large corporate exposures. In theory, if external ratings and regulatory risk measures were compatible, a securitised portfolio of SME should thus require less capital than a securitised portfolio of BBB/BB large corporate exposures. If this is not so, as in the case of SME, then there is a clear anti-SME bias in the risk assessment done by ratings agencies
– In Standard & Poor’s (2013b), the SME CLO “criteria uses the concept of an archetypical European SME pool for which [S&P] have assigned an average credit quality assessment of 'b+' as the starting point for obligor default analysis when assigning 'AAA' ratings. The archetypical pool represents [S&P] view of the average characteristics typically featured by SME portfolios securitised in Europe.”
– In fact, actual default data on SME pools in Europe do not support this arbitrary assumption of B+ since defaults rate tend be much lower than implied by a B+ rating. Moreover this overall B+ assumption does not reflect the reality of historical defaults even during the crisis. Interestingly, B+, which is more appropriate for highly leveraged corporate loans, has a risk weight of 150%, twice the level that is required for SME, at a 75% risk weight
• With a B+ assumption by S&P (Moody’s also considers European SMEs as a ‘B1’ quality), the tranching of a 75% risk-weighted SME pools will be much more capital intensive than the tranching of a 100% risk-weighted BBB/BB corporate portfolio. There is an inversion in the measure of risk Despite a major recession in the periphery…
13.00
8.00
3.00
-2.00 GDP Growth [% y-o-y]
-7.00
-12.00
Source: Moody's Analytics (ECCA) Forecast; Deutsche Bundesbank; Central Statistics Office (CSO); Italian National Institute of Statistics (ISTAT); Statistics Netherlands; National Institute of Statistics (INE); U.K. Office for National Statistics (ONS)
Rating agencies are penalizing SME ABS by …5Y cumulative default rate of assuming too high default rates for their base European SMEs remains limited case (before stress)
EUROPEAN SME 5Y CUMULATIVE Belgium Denmark DEFAULT VERSUS RATING AGENCIES Germany Greece 18.00% ASSUMPTION Italy Netherlands 12.00 16.00%
14.00% 10.00
12.00% 8.00 10.00%
6.00 8.00%
6.00% Defaults* [% of OB] 4.00 4.00% 2.00 2.00%
- 0.00% 1 3 5 7 9 11 13 15 17 19 21 23 25 27 29 31 33 35 37 39 41 43 45 47 49 51 53 55 57 59
Months Since Closing Source: Moody's Investors Service, Moody's Performance Data Service,
Methodology flaw by rating agencies when assigning ratings to SME securitisations • Ratings should not be used for capital or other regulations, especially so for SMEs
• The issues linked to ratings (methodological changes, rating triggers, sovereign linkage, etc… mixed in an opaque manner with collateral performance) have, in recent years, created major problems for European banks
• Negative shocks to bank capital, particularly in periods of crisis, generate forced asset sales and a credit crunch affecting new lending. Unnecessary volatility in regulatory capital requirements is, therefore, costly and tends to undermine financial stability
• In the CRR implementation of the Basel III securitisation capital rules, the European authorities deviated from the hierarchy contained in the final BCBS 2017 document, BCBS d374 in that European banks that are unable to use the SEC-IRBA should now use the SEC-SA for all except (i) low rated STS tranches, (ii) a broader set of non-STS tranches, (iii) cases in which the bank has told the authorities it will systematically employ the SEC-ERBA before the SEC-SA, or (iv) complex deals for which the SEC-SA would not be appropriate.
• This deviation from Basel reflects the concerns described above.
Article 254 Hierarchy of methods
1. Institutions shall use one of the methods set out in Subsection 3 to calculate risk-weighted exposure amounts in accordance with the following hierarchy:
(a) where the conditions set out in Article 258 are met, an institution shall use the SEC-IRBA in accordance with Articles 259 and 260;
(b) where the SEC-IRBA may not be used, an institution shall use the SEC-SA in accordance with Articles 261 and 262;
(c) where the SEC-SA may not be used, an institution shall use the SEC-ERBA in accordance with Articles 263 and 264 for rated positions or positions in respect of which an inferred rating may be used.
2. For rated positions or positions in respect of which an inferred rating may be used, an institution shall use the SEC-ERBA instead of the SEC-SA in each of the following cases:
(a) where the application of the SEC-SA would result in a risk weight higher than 25 % for positions qualifying as positions in an STS securitisation;
(b) where the application of the SEC-SA would result in a risk weight higher than 25 % or the application of the SEC-ERBA would result in a risk weight higher than 75 % for positions not qualifying as positions in an STS securitisation;
(c) for securitisation transactions backed by pools of auto loans, auto leases and equipment leases. More text…
1. Would ratings not be the natural basis for capital in markets for which exposures are extremely heterogeneous in their degree of subordination and in the nature of underlying risks? Do you agree with the objective of reducing reliance on ratings?
2. How could ratings be made more consistent and reliable? For example, should there be ratings of securitisations that strip out the effects of sovereign/country? Are there other changes that could be made that would make ratings a better basis for regulatory use?
3. In the post-crisis regime, ratings agencies are regulated by the SEC and ESMA. In general, the approach consists of evaluating them against their own policies. Is this appropriate? Should the accuracy of their evaluations be a criterion that regulators apply in evaluating ratings agencies?
1. Introduction to securitisation
2. Risk analysis and pricing of securitisations
3. Regulation of securitisations
4. Practical exercise 1: PURA RTS
5. Role of the ratings agencies
6. Liquidity of securitisations
7. Market drivers and motives for using securitizations
8. Practical exercise 2: Optimal Tranching
• Understanding the liquidity of different asset classes is important for deciding appropriate rules on bank liquidity
• Regulators have recently faced important decisions about the Liquidity Coverage Ratio
• Under LCR rules, banks must hold High Quality Liquid Assets (HQLA) in excess of potential liability run-offs that might occur in a crisis.
• Two key aspects of the regulation are:
– How are the run-offs defined? (not our focus here)
– Which assets are eligible for inclusion as HQLA?
• Different vintages and regulatory interpretations of Basel proposals, have led to different proposed and implemented HQLA treatments.
• Generally, the Basel proposals: i. Break HQLA into Category 1 and 2 assets (Category 1 are extremely HQLA). ii. Permit Category 2 to be no more than a set fraction of total HQLA. iii. Require that Category 2 assets are subject to haircuts
Category definitions Approach 1 2a 2b Minimum BCBS (2010) Cash; central bank reserves, and securities No distinction between 2a and 2b. Level 2 are claims on or guaranteed by 15% on Level 2. guaranteed by sovereigns, central banks (or sovereigns, central banks (or similar) with 20% Basel II risk weight. Corporate and similar) with 0% Basel II risk weight Covered bonds rated at least AA-.
BCBS Cash; central bank reserves, and securities Claims on or guaranteed by sovereigns, central RMBS rated AA or higher, 15% on 2a. Higher (2013): guaranteed by sovereigns, central banks (or banks, (or similar) with 20% Basel II risk weigh. corporate debt securities haircuts on 2b: 50% similar) with 0% Basel II risk weight Corporate and covered bonds rated at least AA-. rated between A+ and BBB- on corporate debt, Introduced ; and certain unemcumbered 50% on equities, and Level 2b equities. 25% on RMBS.
US: Fed Bank Balances; Foreign Withdrawable Claims on or guaranteed by US GSEs and certain Certain publically traded 15% on 2a. "Proposed Reserves; Securities Issued or Guaranteed by: US claims on or guaranteed by sovereign entities or a corporate debt securities 50% on 2b. Rule" Treasury or Government Agencies, Central Bank, multilateral development bank that are not included and publically traded shares Sovereign Entity, the BIS, IMF, ECB, EC or by a in Level 1 and have 20% Basel II risk weight. of common stock. multilateral development bank; certain debt securities issued by soverign entities.
Sweden: Cash, Central Bank Balances, Sovereign Debt, No distinction between 2a and 2b. Level 2 defined as: securities with a risk weight 15% on Level 2. Followed Securities with Zero Risk Weight of 20% issued or guaranteed by sovereigns, central banks, public sector bodies, or BCBS (2010) multilateral development banks, Covered and Corporate Bonds of Credit Quality Level 1.
Australia: Cash, Balances held with RBA, Commonwealth No Australian Category 2 assets are recognised. Government and Semi-Government securities; Followed BCBS (2010)
• Where Level 2 assets are defined, they must comprise no more than 40% of the total stock of High Quality Liquid Assets.
• Similarly, 2b assets must (where defined) comprise no more than 15% of the total stock of High Quality Liquid Assets.
Rating Min. Isssue Extremely HQLA Sovereign Bonds issued in Domestic Currency ECAI 1 €250m Covered Bonds ECAI 1 €500m Central Bank reserves - - Notes - - Coin - - Min. ECAI Min. Isssue Max time to maturity HQLA Sovereign Bonds issued in domestic curency ECAI 2 €100m - Covered Bonds ECAI 1 €250m - Corporate Bonds ECAI 4 €250m 10 years RMBS ECAI 1 €100m 5 years Bonds issued by supranational institutions in EEA currencies ECAI 1 €250m - Bonds issued by local government institutions in EEA currencies ECAI 2 €250m - Insufficiently liquid Assets Equities Gold Credit Claims ABS not backed by residential mortgages Central Bank Securities Securities issued by financial institutions Bank-issued government guaranteed bonds Bonds issued by promotional banks This showed some slight movement compared to the initial EBA recommendations Level 1 HQLA
• These may be used without limit in the liquidity buffer and are not subject to a discount (or haircut) to their market value.
• They include: cash, deposits at the central bank, government1 or government guaranteed bonds, and covered bonds that meet certain specific conditions.
• However, the last are subject to a 70% cap in the liquidity buffer and a 7% haircut. Level 2A HQLA
• These can be used up to maximum of 40% in the liquidity buffer and are subject to a
• minimum 15% haircut.
• They include third country government bonds and bonds issued by public entities with a 20% risk weight, EU covered bonds with an ECAI2 2 rating, non-EU covered bonds rated ECAI 1 and corporate bonds rated ECAI 1. Level 2B HQLA
• These can be used up to maximum of 15% in the liquidity buffer and are subject to a minimum haircut varying between 25 and 50%.
• They include: high quality securitisations for RMBS (retail mortgage backed securities), auto, SME and consumer loans; corporate bonds rated at least ECAI 3, shares that are part of a major stock index and other high quality covered bonds.
1. The approach of the LCR eligibility criteria is to include or exclude different assets based on an assessment of their risk and liquidity.
2. There are caps on some exposures but these are set quite high. Would it not be better to encourage diversification by allowing a broader range of assets so long as none dominates in the basket?
3. Does it make sense to allow low grade sovereign bonds some of which are quite illiquid to be in category 2A?
• Common presumption among regulators has been that:
– Covered Bonds are much more liquid than ABS
– Among ABS, RMBS are significantly more liquid than anything else and so
– RMBS are the only ABS sub-class that should be considered liquid.
• We are able to shed light on these views.
• There are many indicators of liquidity that have used to have been used to look at different dimensions of liquidity
• The EBA examined the following indicators:
1. The Amihud illiquidity ratio
2. An un-scaled price impact measure
3. The Roll measure
4. Trading volume
5. Turnover ratio
6. The number of zero trading days
7. Price volatility
• Bid-ask spreads are perhaps the most obvious indicator of liquidity. These were
(surprisingly) not employed by the EBA.
• Here, we present a comparison of bid-ask spreads for individual European ABS and Covered Bonds to shed light on the relative liquidity/illiquidity of these asset classes.
Covered Bonds data:
• Daily bid and ask quotes are obtained from Bloomberg on components of BoA Merrill Lynch Euro CB Index
• We focus on Euro-denominated, investment grade covered bonds publicly traded in the Eurobond or Euro member domestic markets.
• We require at least one year remaining term to final maturity, fixed coupon schedules, and minimum amounts outstanding of EUR 250 million.
• Sample period runs from 26th of May 2009 to 30th of September 2013.
• Number of AAA bid-ask spread observations is 1,334,538.
ABS data:
• Provided by Standard and Poor’s:
• Contains daily bid and ask quotes, characteristic information and cash flow projections for pricing - e.g. prepayment rates and weighted-average lives).
• The sample period runs from 26th May 2009 to 30th September 2013.
• Number of AAA bid-ask spread observations is 722,613; 564,467 are RMBS.
• We focus on AAA-rated ABS since these seem most relevant for a HQLA definition
– although, for some asset categories, the EBA has admitted AA and other ratings.
• Most observations in our sample are RMBS.
• In the middle of our sample there is a marked decline in the number of observations, this:
– mostly reflects downgrades and,
– in some cases, subsequent upgrades, and
– to some extent, changes in the coverage of the S&P dataset.
• The breakdown of the non-RMBS data exhibits considerable changes in composition – most notably for CLOs and CMBS.
• Distribution of Covered bonds by subsector shows that most of the data is for Non-Pfandbriefe.
• All Pfandbriefe are from the German market - with a split between standard and Jumbo Pfandbriefe.
• Non-Pfandbriefe come from the United Kingdom, Spain, France, and Italy.
• Our observations from Spain and Italy exhibit effects of the sovereign ratings ceiling:
• after a certain date, as countries were downgraded, no Covered Bonds could obtain AAA ratings.
• This explains the sharp decline in early 2011
350 600
Spain France UK Italy Pfandbriefe Jumbo Pfandbriefe Non-Pfandbriefe
CMBS CLO RMBS
3.5 3.5 3.5 3 3 2.5 2.5 2.51.52 1.52 1.52 1 1 0.5 0.5 0.5
mean Q-10% Q-90% mean Q-10% Q-90% mean Q-10% Q-90%
Auto Loan HEL ABT
3 1.2 1.6 1.4 2.5 1 1.2 2 0.8
0.6 0.8 1.5 0.6 1 0.4 0.4 0.2 0.5 0.2 0 0
mean Q-10% Q-90% mean Q-10% Q-90% mean Q-10% Q-90%
• The first exercise we perform with our data is to examine the evolution over time of bid-ask spreads for different asset-class sub-categories of the securities in our sample.
• The broad picture that emerges is one in which:
1. for house-market-sensitive ABS (RMBS and HEL), bid-ask spreads, on average, tend to decline over the sample period as concerns about the quality of mortgage lending in the countries in question gradually fell, while
2. spreads for CLOs and CMBS tended to increase initially before subsequently declining
Other Covered Bonds Pfandbriefe 1.2 1.2
0.8 0.8
0.6 0.6
0.4 0.4
0.2 0.2
mean Q-10% Q-90% mean Q-10% Q-90%
• Some jumps occur in the series reflecting Jumbo Pfandbriefe 0.7 changes in the coverage of the data 0.6 available. 0.5
• Broad picture is of a rise in covered bond 0.4 spreads (particularly Non-Pfandbriefe) 0.3 during the 2011 Sovereign debt crisis. 0.2
• Impact of the major ECB interventions of 0.1 2012 is evident – a “Draghi effect” – in the sustained recovery that occurs in the first half of 2012. mean Q-10% Q-90%
Whole sample period 2011 onward Mean Avg SD Avg 90% Avg 10% Mean Avg Avg 90% Avg 10% quantile quantile SD quantile quantile Pfandbriefe 0.32 0.16 0.51 0.12 0.35 0.13 0.52 0.18 Covered Bonds Jumbo Pfandbriefe 0.20 0.11 0.34 0.09 0.25 0.10 0.36 0.14 Other Covered Bonds 0.40 0.18 0.66 0.19 0.44 0.19 0.72 0.22 RMBS 0.98 1.00 2.27 0.16 0.77 0.89 1.89 0.11 ABS CLO 0.96 0.11 1.82 0.42 1.07 0.61 1.82 0.42 CMBS 0.97 0.83 1.75 0.18 1.03 0.88 1.82 0.14 ABT 0.58 0.29 0.91 0.28 0.61 0.31 0.93 0.29 HEL 0.65 0.49 1.27 0.10 0.47 0.39 0.99 0.04 Auto Loan 0.33 0.23 0.81 0.11 0.31 0.21 0.75 0.10
• Over the sample period, Covered bond bid-ask spreads are less than those of ABS.
• However, Auto-Loan ABS are comparable in liquidity to Pfandbriefe and more liquid than both Jumbo Pfandbriefe and other Covered Bonds.
• In the crisis (from 2011 onwards), the 10% quantiles of RMBS and HEL show greater liquidity than Covered Bonds
– This suggests that the most liquid ABS are more liquid than the most liquid covered bonds. 2011 January Frequency
0.35
0.3
0.25
0.2
0.15
• The key message is
0.1 that auto-loan ABS
0.05 and Covered Bonds have comparable
Bid-Ask Spread (%) liquidity All Covered Bonds Frequency 2013 January Auto Loan 0.35
0.3
0.25
0.2
0.15
0.1
0.05
Bid-Ask Spread (%) 2011 January Frequency
0.35
0.3
0.25
0.2
• The key message 0.15 is that, when 0.1 compared to
0.05 non-Pfandbriefe 0 Non-Pfandbriefe Covered Bonds, Bid-Ask Spread (%) Auto Loan Auto-Loan ABS Frequency 2013 January are superior in 0.35 liquidity. 0.3
0.25
0.2
0.15
0.1
0.05
Bid-Ask Spread (%)
• Spanish and Italian spreads terminate early because of the effects of the sovereign ratings ceiling.
• French bid-ask spreads peak just before Draghi intervention; UK bid-ask spreads remain high for longer.
Whole sample period 2011 onward Mean Avg SD Avg 90% Avg 10% Mean Avg Avg 90% Avg 10% quantile quantile SD quantile quantile
Spain 0.51 0.19 0.75 0.27 0.68 0.18 0.90 0.44 Covered Bonds (a) France 0.40 0.16 0.61 0.19 0.45 0.19 0.71 0.22 UK 0.41 0.16 0.62 0.21 0.48 0.18 0.73 0.25 Italy 0.37 0.11 0.51 0.22 0.62 0.18 0.75 0.34 Spain 0.58 0.16 0.76 0.35 0.68 0.15 0.83 0.45 Covered Bonds (b) Italy 0.54 0.11 0.67 0.37 0.73 0.14 0.83 0.47 RMBS (a) Spain 1.45 1.06 2.76 0.27 1.20 1.07 2.62 0.08 Italy 1.45 0.58 2.20 0.46 1.55 0.43 2.17 0.34 UK 0.81 0.92 2.08 0.18 0.49 0.66 1.14 0.09 Spain 1.40 0.92 2.49 0.34 1.24 0.85 2.28 0.31 RMBS (b) Italy 1.34 0.78 2.31 0.47 1.34 0.78 2.36 0.43
• In the rows designated (a) securities drop out of our sample when the sovereign downgrade forces them to lose their AAA ratings.
• In the rows marked (b) securities in our sample are fixed at their pre-sovereign downgrade levels, and so do not drop out of the sample. This is done to prevent a loss of observations.
• Again, Covered Bonds appear more liquid than RMBS over the entire sample period.
• The post-2011 comparability of CB and ABS liquidities is even more pronounced when looking at these national markets.
• One might expect the securities’ domiciles to influence both liquidity and risk indicators (such as the bid-ask spread).
• The calibration exercise implemented by the EBA to determine the LCR eligibility buckets, the EBA does not explore country-effects in its analysis for understandable reasons
• Ex ante, one would expect country effects to be powerful, as worries about different economies’ growth prospects and banking sector and sovereigns’ solvencies evolved over time.
• Leaving out country effects means that analysis suffers from an important ‘omitted variables’ problem.
• If one finds, for example, that differences in the regulation of Covered Bond markets have an influence on liquidity, it may be that this simply reflects an omitted country effect. UK Covered Bonds vs. RMBS: Spanish Covered Bonds vs. RMBS:
Frequency 2011 January Frequency 2011 January 0.45 0.4
0.4 0.35 0.35 0.3 0.3
0.25 0.25
0.2 0.2
0.15 0.15
0.1 0.1
0.05 0.05
0 0
Bid-Ask Spread (%) UK Covered Bonds Bid-Ask Spread (%) Spain Covered Bonds 2013 January UK RMBS Frequency Spain RMBS Frequency 0.45 2013 January 0.4 0.4 0.35 0.35 0.3 0.3
0.25 0.25
0.2 0.2
0.15 0.15
0.1 0.1
0.05 0.05
0 0
Bid-Ask Spread (%)
Bid-Ask Spread (%)
• One may also look at the problem of comparing the relative liquidities of Covered Bonds and ABS from a somewhat different perspective.
• In valuing an asset now, market participants will allow for the discounted costs of future - rather than current - transactions costs.
– Since sales may occur in crisis periods, their size may be substantial.
– Transactions costs in crises may be large and subject to significant risk premiums.
• Such discounts for future transactions costs reduce both the bid and ask prices of securities.
• By investigating the level of such discounts and how they behave over time, we obtain a perspective on how concerned the market has been about transactions costs for different asset classes in periods of crisis.
• The Draghi effect is very evident
• There are substantial differences between Pfandbriefe and other Covered Bonds.
• The illiquidity discounts are greatest for Spanish securities.
• There is major volatility in discounts in the Spring of 2011
• The timing is different for France and Britain - peak discounts in late 2011
• Liquidity discounts for AAA RMBS are large and similar sizes to Spanish CB.
• The emergence of liquidity discounts occurs later, however.
• We interpret this as showing that, when RMBS spreads narrow in 2011, the narrowing occurs first for liquid issues, opening a gap between liquid and illiquid RMBS.
• This section provide perspectives on the relative liquidity of two important European asset classes, Covered Bonds and ABS. We focus on evidence from bid-ask spread data - data neglected in the recent EBA analysis of asset class liquidity.
• We present:
1. simple, transparent calculations of bid-ask spread distributions and
2. more elaborate calculations that illustrate the contribution of market worries about future crisis-period transactions costs to individual security discounts.
• Both approaches suggest that Covered Bonds and ABS are not as different as some have suggested: i. The more liquid ABS exhibit greater liquidity than Covered Bonds. ii. In general, in the sovereign crisis period around 2011, Covered Bonds appear to have been less liquid than ABS. iii. One category of short-dated, non-mortgage-related ABS, auto-loan-backed ABS, ranked very low for liquidity by the EBA, has tight spreads and so appears comparable to the most liquid Covered Bonds.
• As a result, taken together, we believe our analysis implies a different picture of the relative liquidity of asset classes than is common among regulators
1. Did you find the data analysis convincing or not?
2. Can liquidity be reliably evaluated based on past episodes? Most banks regarded high-grade securitisations as highly liquid prior to the crisis.
3. Will the LCR rules be self-vindicating in that the designation of LCR eligible will make certain assets more liquid? Is this a concern?
1. Introduction to securitisation
2. Risk analysis and pricing of securitisations
3. Regulation of securitisations
4. Practical exercise 1: PURA RTS
5. Role of the ratings agencies
6. Liquidity of securitisations
7. Market drivers and motives for using securitizations
8. Practical exercise 2: Optimal Tranching
Based on the mechanism of credit risk transfer to the capital markets, there are two types of securitisation: Comparison of the two securitisation types True-sale Synthetic
• In a true-sale securitisation, the originator passes Portfolio of Passed onto Remains on the loan ownership to an SPV. loans an SPV bank balance
• This removes the loans from the originator’s balance Credit risk/ sheet and the SPV gaining entitlement to their cash Purpose Funding capital flows. management
• In a synthetic securitisation, the originator transfers Typical Mortgages, Corporate the credit risk of bundled loans via credit derivatives underlying consumer exposures, portfolio loans SME loans such as CDS or guarantees to the capital markets. Investor Cash flows of
• The loans themselves remain on the originator’s CDS premium return underlying balance sheet. Source: Deutsche Bank Research (2017)
• Often balance sheet synthetic securitisation take this form but in some cases the originator does not own the underlying loans and buys the credit protection solely for arbitrage opportunities. These are known as arbitrage synthetic securitisation.
Balance sheet synthetic securitisation
i) Synthetic securitisation has fewer administrative and legal requirements than true-sale transactions which require sale Originator and insolvency-proof transfer of the underlying loan. ii) Responsible approaches to such risk transfer require, in the language of Basel capital regulation, Simple Transparent and Standardised (STS) securitisation structures. iii) For non-synthetic securitisations, Basel has prescribed a set Derivative (CDS) of standards that must be met if deals are to be categorised Periodic credit as SST in which case they attract lower capital when held in bank’s portfolios. protection premium Reimbursement in case of loan default iv) EBA (2017) sets out the issues, listing possible features of an SST that might lead it to be considered as achieving Investor significant risk transfer (SRT) which would allow the originator to employ the beneficial STS risk weights for the retained securitisation positions. Source: Deutsche Bank Research (2017) The market is bilateral in that deals are typically unrated and are placed privately with buy-side institutions such as hedge funds, pension funds and insurers. The data in the figure below shows steady growth in issuance since 2013 and indicates that the large majority of underlying assets are either large corporate or SME loans.
Impetus to SST issuance has been provided by the relatively conservative nature of risk weights for corporates under Basel 3 rules. The introduction in Basel 3 of Standardised Approach floors to Internal Ratings Based (IRB) capital is likely to increase further the pressure on banks to transfer the risk of their corporate exposures through SSTs or other measures. Figure below shows the evolution of SST issuance in Europe up to 2016. Since the crisis volumes grew markedly as banks tried to economise on the high capital charges for corporate exposures.
Bilateral SSTs in Europe (EUR Billion) EU SST by asset class (% of 2015 issuance)
17%
53% 30%
• We will look at example synthetic securitisations.
• We will look at possible securitisation of non-corporate loans by prominent Multilateral Development Banks (MDBs).
• The approach to evaluating securitisation is not different from how it might be looked at by a commercial bank although in practical applications there is perhaps less “optimisation” and more tatonnement as parties examine different deal structures and their implications.
• MDBs may engage in an SST to economise on ‘ratings agency capital’ and economic capital. In contrast, commercial banks’ primary preoccupation is in the freeing up the regulatory capital.
• The exercise is explained in a note that will be distributed in printed form and is implemented in an Excel workbook with executable VBA code.
• We will go through the document and then you will explore different recalibrations, examining how the optimal tranching changes as the parameters of the underlying pool and of the pricing change. i. Using publicly available MDB data, we determine the optimal tranching structure if an MDB were to securitise its non-sovereign exposures using a synthetic securitisation transaction. ii. We consider four tranches: junior (retained), private investor, public investor and senior (retained). Let the thickness of the four tranches be denoted by ℎ[1], ℎ[2], ℎ[2] and ℎ[4]. We assume the private investor tranche is fully collateralised. iii. The optimal tranching structure is obtained by maximizing a benefit to cost ratio where the benefit is measured in terms of the reduction in bank’s RWA and the cost is measured in terms of the reduction in bank’s margin from the transaction. iv. The problem is formulated as,
RW[1]ℎ[1] + RW[2]ℎ[2] + RW[3]ℎ[3] + RW[4]ℎ[4] −1 RWBeforeSST max fℎ=

m−(ℎ[2] × c[1] + ℎ[3] × c[2] −1 m subject to the constraints:
ℎ[1] + ℎ[2] + ℎ[3] + ℎ[4] = 1 RWBeforeSST −(RW[1]ℎ[1] + RW[2]ℎ[2] + RW[3]ℎ[3] + RW[4]ℎ[4]) ≥0 ℎ[1] + ℎ[2] + ℎ[3] ≥PLR m−(ℎ[2] × c[1] + ℎ[3] × c[2]) ≥0
+ 0.7ℎ[2][2] c[1] = − 1 τ log1 −ELTℎick ℎ[1], ℎ[1] + ℎ[2]
i. The first constraint requires that the percentage tranche thicknesses of the tranches sum to 1. ii. The second constraint requires that the total RW after SST should be no greater than the total before SST (where the current value is inferred from S&P report). iii. The third constraint states that the detachment point of protection should be greater than the PLR so that the senior tranche is rated A. iv. The fourth constraint requires that the cost be less than the bank margin. We assume a bank margin of 3.8% denoted by m. v. The fifth constraint states that the cost of the private investor tranche denoted by c[1] is the tranche spread, where τ is the maturity and ELTℎick can be calculated as follows:
ELTℎick A, D= 1 −AELSenior A−1 −DELSenior D D−A

1 −X
, ρpool

N−1 PD− 1 −ρpoolN−1 XLGDΤ PDTrancℎe X= N ρpool i. We perform the optimisation first using S&P Risk Weights and then repeat the exercise using Basel Risk Weights. ii. The old S&P methodology applies , RW[1] = 1250% for the junior retained tranche, RW[2] = 3% for the private investor tranche that is fully collateralised, RW[3] = 3% for the public investor tranche where the public institution is rated “AA-” or higher and RW[4] = 50% for the senior retained tranche that is rated “A”. iii. The “A” rating of the senior retained tranche is realised only if the detachment point of the protected tranche is lesser than the portfolio loss rate (PLR). For estimating the PLR, we first calculate the total loss as the sum of three-year normalised expected loss, EL3Year and the unexpected loss, UL as,
EL3Year = 3 × (EADFI × LRFI + 0.75EADCorporate 0.95 × LRCorp + 0.05 × LRCRE
where, EADFI and EADCorporate denote the financial institution and corporate exposures, LRFI, LRCorp, LRCRE denote the loss rates for financial institution, corporate and construction and real-estate exposures. UL= RWAFI + RWACorporate 12.5
where, RWAFI and RWACorporatedenote the financial institution and corporate RWAs. Then,
TL PLR= EADFI + EADCorporate
i. For the case with using Basel risk weights, the RW before transaction is calculated as, RWbeforeSST = K× 12.5, RN−1 0.001 K= LGD× N N−1 PD− −PD × 1 + M−2.5 b , 1 −1.5b 1 −R
b= 0.11852 −0.05478 × LnPD R= 0.12 × (1 −e−50PD) + 0.24 1 − 1 −e−50PD 1 −e−50 1 −e−50 ii. To get the RW after transaction, we apply, RW[1] = 1250% for the junior retained tranche, RW[2] = 3% for the private investor tranche, RW[3] = 3% for the public investor tranche and RW[4] is determined as follows, 1250%, ifKIRB≥1 KSSFA(KIRB) × 12.5, ifℎ[1] + ℎ[2] + ℎ[3] ≥KIRB RW[4] = 1 −KIRB× 12.5 × KSSFA(KIRB) 12.5(KIRB−ℎ[1] −ℎ[2] −ℎ[3]) + , otℎerwi 1 −ℎ[1] −ℎ[2] −ℎ[3] 1 −ℎ[1] −ℎ[2] −ℎ[2]
RN−1 0.001 KIRB= LGD× N N−1 PD− × 1 + M−2.5 b 1 −1.5b 1 −R
KSSFA(KIRB) = eau −eal ) a(u−l
u= 1 −KIRB l = max(ℎ[1] + ℎ[2] + ℎ[3] −KRIB, 0)
a= − p× KIRB
p= max 0.3, A+ B + C× KIRB+ D× LGD+ E× MT N
where, A = 0.00, B=3.56, C=-1.85, D=0.55, E=0.02 and N is assumed to be large enough so that 1/N is close to zero.
1. Basel Committee on Bank Supervision (2013c) “Revisions to the securitisation framework,” Consultative Document, Bank for International Settlements, December, (BCBS 269)
2. Duponcheele, Georges, William Perraudin and Daniel Totouom-Tangho (2013a) “A Principles-Based Approach to Regulatory Capital for Securitisations,” BNP Paribas mimeo, April, available at: http://www.riskcontrollimited.com/public/Regulatory_capital_for_securitisations.pdf
3. Duponcheele, Georges, William Perraudin and Daniel Totouom-Tangho (2013b) “The Simplified Arbitrage-Free Approach: Calculating Securitisation Capital based on Risk Weights Alone,” BNP Paribas mimeo, July, available at: http://www.riskcontrollimited.com/public/Simplified_AFA_revised.pdf
4. Duponcheele, Georges, William Perraudin and Daniel Totouom-Tangho (2013c) “Maturity Effects in Securitisation Capital: Total Capital Levels and Dispersion Across Tranches,” BNP Paribas mimeo, September, available at: http://www.riskcontrollimited.com/public/Maturity_Effects_in_Securitisation_Capital.pdf
5. Duponcheele, Georges, William Perraudin, Alastair Pickett and Daniel Totouom-Tangho (2013d) “Granularity, Heterogeneity and Securitisation Capital,” BNP Paribas mimeo, September, available at: http://www.riskcontrollimited.com/public/Granularity_Heterogeneity_and_Securitisation_Capital.pdf
6. Duponcheele, Georges, William Perraudin and Daniel Totouom-Tangho (2014a) “Reducing the Reliance of Securitisation Capital on Agency Ratings,” BNP Paribas mimeo, February, available at: http://www.riskcontrollimited.com/public/Reducing_the_Reliance.pdf
7. Duponcheele, Georges, William Perraudin and Daniel Totouom-Tangho (2014b) “Calibration of the Simplified Supervisory Formula Approach,” BNP Paribas mimeo, March, available at: http://www.riskcontrollimited.com/public/Calibration_of_SSFA.pdf
8. Duponcheele, Georges, Alexandre Linden, William Perraudin and Daniel Totouom-Tangho (2014c) “Calibration of the CMA and Regulatory Capital for Securitisations,” BNP Paribas mimeo, April, available at: http://www.riskcontrollimited.com/public/Calibration_of_CMA.pdf
9. Duponcheele, Georges, Alexandre Linden and William Perraudin (2014d) “How to Revive the European Securitisation Market: a Proposal for a European SSFA,” BNP Paribas mimeo, November, available at: http://www.riskcontrollimited.com/public/How_to_Revive_the_European_Securitisation_Market.pdf
10. European Banking Authority (2014) “Discussion Paper on simple, standard and transparent securitisations,” (EBA/DP/2014/02), October
11. Perraudin, William (2014a) “Covered Bond versus ABS Liquidity: A Comment on the EBA’s Proposed HQLA Definition,” Risk Control Limited Research Paper, 17, January, available at: http://www.afme.eu/WorkArea/DownloadAsset.aspx?id=10360
12. Perraudin, William (2014b) “High Quality Securitisation: An Empirical Analysis of the PCS Definition,” June, available at: http://www.riskcontrollimited.com/public/High_Quality_Securitisation.pdf
13. Perraudin, William (2014c) “Quantitative Impacts of BCBS 269 Securitisation Capital Approaches,” Risk Control Limited Report, 14-73a, August, available at: http://www.riskcontrollimited.com/public/Quantitative_Impacts_of_BCBS_269_Securitisation_Capital_Approaches.pdf
14. Perraudin, William (2014d) “Securitisation Purchases by the ECB - What is ‘Senior Enough’?,” Risk Control Limited Report, 14-81a, September, available at: http://www.riskcontrollimited.com/public/Securitisation_Purchases_by_the_ECB_What_is_Senior_Enough.pdf
15. Peretyatkin, Vladislav and William Perraudin (2002) “Expected Loss and Probability of Default Approaches to Rating Collateralised Debt Obligations and the Scope for ‘Ratings Shopping,,’” in Risk Books volume edited by Michael Ong.
16. Peretyatkin, Vladislav and William Perraudin (2004) “Capital for Structured Products,” Risk Control Limited Report, November, available at: http://www.riskcontrollimited.com/research_papers/Peretyatkin_Perraudin_ref4_2.pdf
Website: www.riskcontrollimited.com Telephone: +44 20 3307 0730 Address: 13-14 Dean Street, London, W1D 3RS, U.K.
William Perraudin, Director
Notes
HQS Non-HQS HQS Non-HQS HQS Non-HQS Note: on periphery country bid-ask spreads, see note to (3/6) slide on bank level selectivity effects to do with distressed cajas in Spain. Source: BCBS (2014) Length of data 180(1)(h) “the length of the underlying historical observation period used shall be at least five years for at least one source…. institutions which have not received the permission … to use own estimates of LGDs or conversion factors may use, when they implement the IRB Approach, relevant data covering a period of two years…” 180(2)(e) “irrespective of whether an institution is using external, internal or pooled data sources or a combination of the three, for their estimation of loss characteristics, the length of the underlying historical observation period used shall be at least five years for at least one source…. Subject to the permission of the competent authorities, institutions may use, when they implement the IRB Approach, relevant data covering a period of two years. The period to be covered shall increase by one year each year until relevant data cover a period of five years” Confidential © Risk Control Limited 2020 130 Benchmarking 185(c) “institutions shall also use other quantitative validation tools and comparisons with relevant external data sources…” Maintenance 176(2) “For exposures to corporates, institutions and central governments and central banks, and for equity exposures …. institutions shall collect and store: (a) complete rating histories on obligors and recognised guarantors … (g) data on the PDs and realised default rates associated with rating grades and ratings migration.” Confidential © Risk Control Limited 2020 131 Confidential © Risk Control Limited 2020 132 Benchmarking 185(c) “institutions shall also use other quantitative validation tools and comparisons with relevant external data sources…” Maintenance 176(4)(g) “Institutions using own estimates of LGDs and conversion factors shall collect and store…data on the components of loss for each defaulted exposure.” 176(5)(c) “For retail exposures, institutions shall collect and store…. the identity of obligors and exposures that defaulted” Confidential © Risk Control Limited 2020 133 France 1/0 5/0 9/0 France 1/0 2/0 2/0 individual European Germany 8/1 12/2 19/2 Germany 7/0 14/8 16/9 Italy 5/0 24/0 33/0 Italy 11/1 14/5 105/8 Netherlands 7/3 10/1 11/2 Netherlands 6/6 25/7 28/7 • For example, Fitch was Spain 158/2 69/4 99/7 Spain 207/8 74/10 79/12 UK 31/16 138/17 264/31 UK 104/12 127/32 333/33 Multinational 35/2 121/6 181/7 Multinational 36/24 172/53 181/61 European Total 274/27 442/8 903/8 European Total 372/51 428/115 744/130 negative about the UK in US 1446/284 2000/82 2694/82 US 2146/1708 1090/982 1426/1217 Source: DBRS, Fitch Ratings, Moody’s Investors Service, S&P Global Ratings Loans to large corporations Loans to SMEs Other