

This note shows through a case study how Risk Control’s Stress ControllerTM software may be used to implement top down stress testing of a bank. The calculations are based on the publicly available financial statement and Pillar 3 disclosures of a large UK bank.
1. Executive Summary
This note shows through a case study how Risk Control’s Stress ControllerTM software may be used to implement top down stress testing of a bank. The calculations are based on the publicly available financial statement and Pillar 3 disclosures of a large UK bank.
We show how the balance sheet, P&L and key financial ratios are affected by scenarios involving recessions in America, Europe and the UK. A set of equations is constructed to describe the evolution of the bank’s financial statements.
Changes in the credit quality of the bank’s loan book and fluctuations in the value of mark-to-market exposures affect asset values and income through provisions and mark-to-market asset write-offs. For a base case and for each of the stress scenarios, predictions are supplied for the bank’s key variables.
The results show how the bank’s impairment provisions rise, and capital, asset growth, returns on equity and profitability are depressed by the different recession scenarios. A UK-based recession has a larger impact than the other recession scenarios but shows a more rapid recovery.
Note that the framework used here may be used either with coarse, public data to perform top down stress testing or with highly granular internal bank data for bottom-up stress testing purposes. The financial statement modeling is highly flexible since equations may be written first in Excel, converted into scripts and then imported into the software for use at run-time to perform calculations.
For more information, contact: sales_enquiries@riskcontrollimited.com
2. Introduction
This note presents the results of an illustrative set of forecasts for the balance sheet of a major bank conditional on several macroeconomic scenarios.
The calculations are performed using Risk Control’s software Stress ControllerTM. This software permits the user to formulate a macroeconomic scenario and then to forecast conditional time paths for a wider set of macroeconomic variables for different geographical regions. The impact of the macroeconomic variable time paths on a bank’s portfolio may then be calculated and estimates of provisions may be fed into a model of the bank’s financial statements.
As an example bank, we have chosen Barclays Group PLC (hereafter referred to as the bank). The calculations presented here are based entirely on publicly disclosed data and have not been sanctioned or endorsed in any way by the bank. This bank has been selected as the example used in our case study because of its importance as a major UK bank with a strong international presence.
Using publicly available information from the bank’s annual report and Pillar 3 risk disclosures, we have:
1. Prepared appropriate historical macro data for the geographical regions within which the bank operates (i.e. Europe, UK, the Americas, Africa and the Middle East and Asia),
2. Extractedinformation from the bank’s annual report on its historical financial statements,
3. Generateda set of user-defined financial statements modeling equations.
4. Performed stressed financial forecasting calculations under different scenarios.
The scenarios we analyze are a base case (in this study we use the forecasts by IMF World Economic Outlook as the base case) and three stress scenarios. The three stress scenarios consist of 3-year recessions in (i) Europe,
(ii) UK and (iii) the Americas respectively. In each case, the recession is specified to be negative shocks to real GDP of 2% and 1% in the first 2 quarters and of 0.5% in the subsequent 10 quarters.
The results are intuitive and convincing with capital ratios and indicators of profitability in the stress scenario cases following paths markedly below the baseline paths and with impairment provisions boosted and loan and deposit growth depressed compared to the base case.
Two important advantages of the software are as follows. First, the calculations presented here illustrate how one may use Stress ControllerTM to analyze bank financial statements and the vulnerability a bank exhibits with respect to macroeconomic shocks of different types even with relatively simple public data. Stress ControllerTM may also be used with complex and elaborate bank exposure data (for example, with tens or hundreds of thousands of underlying individual or semi-aggregated exposures) to perform bottom up stress analyses.
Second, the financial statement model employed consists of a set of equations linking balance sheet and P&L quantities (i) to macroeconomic variables, (ii) to provisions and mark-to-market write-offs based on exposures representing the bank’s assets, (iii) to user supplied parameters and variables (for example, capital injections and dividend payout rates). These equations may be created by the user of Stress ControllerTM and then imported as part of the data employed. At run-time, the software uses them to perform calculations. This approach ensures maximum flexibility.
3. Generating Consistent Macroeconomic Scenarios
In devising stress tests, one must first accomplish the (often challenging) task of generating consistent time paths for multiple macroeconomic variables. For example, one may wish to consider the impact of a recession in the US affecting say US GDP. However, this raises the issue of what is the impact on European or Asian GDP and also what happens to interest rates, exchange rates, inflation and commodity prices?
Risk Control’s Stress ControllerTM software contains an embedded macroeconomic model in which one may specify a series of shocks to a particular variable and calculate conditional forecasts of this and other variables into the future. The macroeconomic model employed is a statistical model commonly referred to as a Global Vector Autoregressive or GVAR model. Such models have been extensively used by academics and practitioners in economic forecasting units in central banks and other bodies to forecast macro time series.
It is important to allow for contagion between regions in the propagation of macroeconomic scenarios.GVAR models suppose that for each geographical region there exists a vector of macroeconomic variables which evolve linearly over time as non-stationary but cointegrated time series. The variables in each region are affected by their own lagged values and by weighted sums of variables from other regions.
The GVAR model included in Stress ControllerTM is highly flexible in that one may readily change the countries and regions. In the exercise reported in this note, we adopt a set of regions consistent with the bank’s approach to categorizing its loan exposures. Specifically, we suppose that the regions comprise: (a) UK, (b) Europe (excluding the UK), (c) the Americas (comprising South, Central and North American countries), (d) the Middle East and Africa, and (e) Asia.
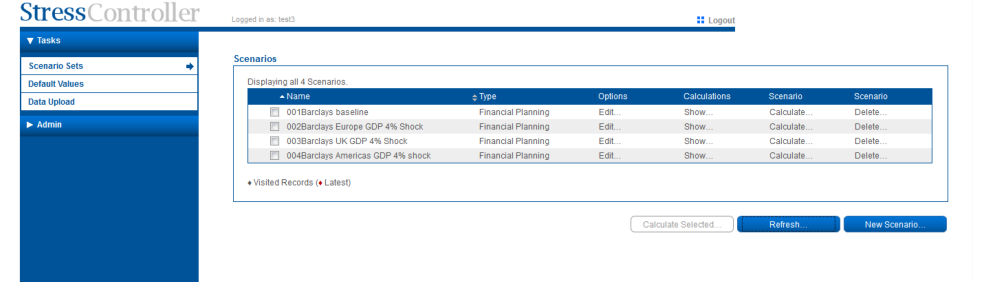
To set up scenarios within Stress ControllerTM, one operates through the web-based interface. Scenarios are stored within an underlying relational database and repeated calculations may be performed for a given scenario after amendments are made to the scenario itself or after the underlying data has been updated. Figure 1 shows the list of scenarios within the Stress ControllerTM web-based interface.
Figure 2 shows a screen shot during the editing of a scenario. Scenarios consist of sequences of period-byperiod shocks to macroeconomic variables. Non-interest-rate macro time series are stored in log form. Hence, a shock of negative one unit in a given quarter to a scenario variable such as GDP corresponds to a minus 1% innovation.
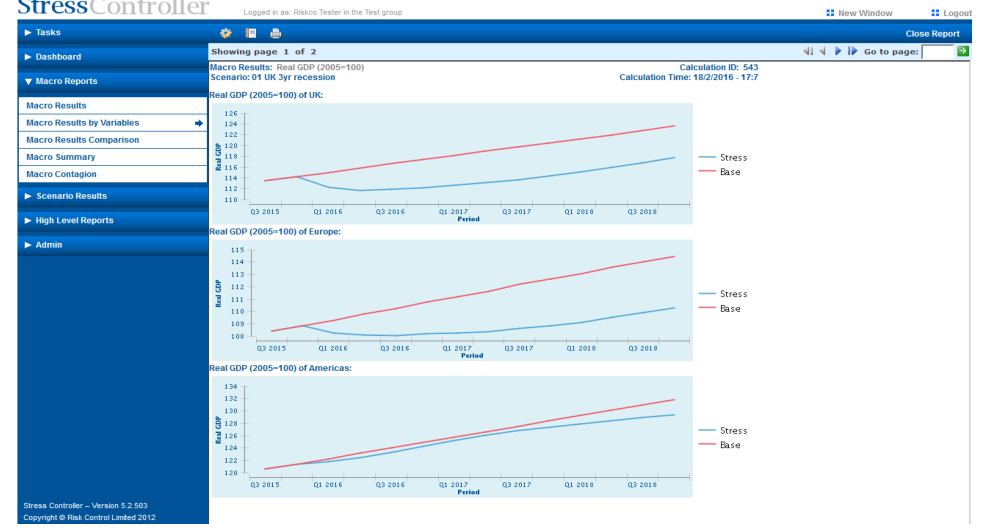
Stress ControllerTM produces time paths of macroeconomic variables such as those shown in Figure 3. These time series are the mean values of the variables in question conditional on the assumed shocks to the scenario variables.
Note that, as an alternative to generating macroeconomic scenarios within Stress ControllerTM one may import a scenario in the form of a set of time series for different macroeconomic variables. Hence, one may work with scenarios generated by regulators or a bank economicsdepartment, importing the scenario time series into the application and then performing additional calculations with them.
Figure 2: Editing Scenarios - Shocks to GDP
4. The Bank’s Loan Portfolio
4.1 Loan Data
This section presents a description of the bank’s loan books based on its Pillar 3 disclosures as recorded in its annual report. The bank provides information on the breakdown of its loan book by region, sector, credit quality, and asset class.
Table 1 shows the matrix of sector and region loan volumes. These figures are derived from the bank’s annual reports for 2014 and 2013. To be specific, we have made the following assumptions and adjustments when deriving Table 1.
In the annual report of 2013 the full matrix of loan breakdown by sector and region is given directly, while in 2014 only the aggregation numbers (the right-hand side column and the bottom row of Table 1) are provided. We assume that within each sector the distribution across regions remains the same as that in 2013. We then set the sector ‘Other financial institutions’ as the balancing sector to ensure the sum of each region to be consistent with the region total figures given in the 2014 annual report. For cell UK-Home loans, the value (126,668 million) is specifically given in the 2014 annual report therefore we take this value and assign the difference between this value and the estimated number to another region, Europe.
248,387 73,226 88,165 42,197 17,903 469,878 Source: the bank’s Annual Report 2014(page 149 and 515) and 2013 (page 152).
Table 2 shows the distribution by credit quality within each asset class. This distribution is not given directly in the annual report, we collect information on performing and non-performing loans from different sections of the bank’s 2014 annual report and make some assumptions to derive the figures in Table 2. Due to the lack of information on ‘Other retail’ and the breakdown of Wholesale into ‘to bank’ and ‘to customer’, we assume credit quality distribution of Wholesale to bank, Wholesale to customer and Other retail are the same as the overall ‘Wholesale’.
Report 2014.
Table 3 contains the calibrated probability of default (PD) for different asset classes and credit quality groups. These PDs are chosen from the PD ranges provided by the bank which are shown in Table 4. The bank only provides information for the overall retail and wholesale, we thus make assumptions to further differentiate between different asset classes. Within the same credit quality group, we let the calibrated PD of ‘Cards’ to be higher than the other retail classes and ‘Home loans’ to be no-higher than ‘Other retail’. Similarly, PDs of ‘Wholesale to customer’ are calibrated to be significantly higher than that of ‘Wholesale to bank’.
In Table 5, we confirm that the initially calibrated total loss rates (70 bps) approximately match the target total loss rates (78 bps) derived from the information disclosed by the bank in its annual report. To achieve this we adjust the PDs in Table 3 and the recovery rates (displayed in the 2nd column of Table 5) to ensure that, for each asset class, the loss rate from our calibration (displayed in the 3rd column of Table 5) matches the loss rate disclosed by the bank (displayed in the 6th column of Table 5).
| Industrial sectors | credit | class | UK | Europe | Americas | East | Asia | Total | ||
|---|---|---|---|---|---|---|---|---|---|---|
| Banks | Wholesale | to | bank | 6,442 | 12,756 | 11,426 | 2,612 | 7,029 | 40,265 | |
| Other financial | institutionsa | Wholesale | to | customer | 26,800 | 11,036 | 53,143 | 8,023 | 4,386 | 103,388 |
| Manufacturing | Wholesale | to | customer | 5,975 | 2,158 | 1,461 | 1,372 | 682.4018 | 11,647 | |
| Construction and | property | Wholesale | to | customer | 17,314 | 2290.781 | 911.7345 | 2182.059 | 143.0546 | 22,842 |
| Government and | central bank | Wholesale | to | customer | 1,549 | 1741.938 | 686.1573 | 1327.238 | 1811.054 | 7,115 |
| Government and | central bank | Wholesale | to | bank | 402 | 451.949 | 178.0248 | 344.3545 | 469.8815 | 1,846 |
| Energy and water | Wholesale | to | customer | 1,964 | 3476.484 | 1705.596 | 841.9163 | 547.5319 | 8,536 | |
| Wholesale and | retail distribution and leisure | Wholesale | to | customer | 9,964 | 1343.854 | 481.1331 | 1368.741 | 181.4618 | 13,339 |
| Business and other | services | Wholesale | to | customer | 14,303 | 2961.82 | 2475.618 | 2147.766 | 483.9721 | 22,372 |
| Home loans | Home loans | 126,668 | 26183.71 | 727.3205 | 13068.52 | 326.4572 | 166,974 | |||
| Cards, unsecured | loans and other personal lending | Cards | 31,480 | 7590.703 | 14115.22 | 4293.799 | 1433.874 | 58,914 | ||
| Other wholesale | Wholesale | to | customer | 1,107 | 247.3307 | 171.1883 | 924.8132 | 81.82667 | 2,532 | |
| Other retail | Other retail | 4,419 | 987 | 683 | 3,692 | 327 | 10,108 |
| Performing | Performing | Performing Past | due not | Impaired Impaired | |||
|---|---|---|---|---|---|---|---|
| Asset classes strong | satisfactory | higher | risk | impaired | collectively individually | Total | |
| Wholesale to bank | 0.7499 | 0.1874 | 0.0097 | 0.0394 | 0.0022 | 0.0114 | 1 |
| Wholesale to customer | 0.7499 | 0.1874 | 0.0097 | 0.0394 | 0.0022 | 0.0114 | 1 |
| Home loans | 0.8578 | 0.0830 | 0.0036 | 0.0026 | 0.0503 | 0.0027 | 1 |
| Cards | 0.2124 | 0.6806 | 0.0209 | 0.0061 | 0.0690 | 0.0111 | 1 |
| Other retail | 0.7499 | 0.1874 | 0.0097 | 0.0394 | 0.0022 | 0.0114 | 1 |
Source: the ‘Credit quality of L&A’ data on pages from 147 to 148 and from 171 to 173 of the bank’s Annual
| Performing | Performing | Performing | Past due | not Impaired | Impaired | |
|---|---|---|---|---|---|---|
| Asset classes strong | satisfactory | higher | risk impaired | collectively | individually | |
| Wholesale to bank | 0.01 | 0.02 | 0.03 | 15 | 20 | 20 |
| Wholesale to customer | 0.01 | 0.6 | 11 | 15 | 20 | 20 |
| Home loans | 0.3 | 2 | 10 | 15 | 20 | 20 |
| Cards | 0.6 | 5 | 12 | 15 | 20 | 20 |
| Other retail | 0.4 | 2 | 10 | 15 | 20 | 20 |
| Retail | Wholesale | ||
|---|---|---|---|
| lending | lending | ||
| Financial statement | Default | ||
| description | PD | PD | grade |
| strong | 0.0-0.6% | 0.0-0.05% | 1-3 |
| 0.05-0.15% | 4-5 | ||
| 0.15-0.30% | 6-8 | ||
| 0.3-0.60% | 9-11 | ||
| Satisfactory | 0.60-10% | 0.6-2.15% | 12-14 |
| 2.15-11.35% | 15-19 | ||
| Higher risk | 10.00%+ | 11.35%+ | 20-21 |
Source: the ‘Internal measures of credit quality’ table on page 146 of the bank’s Annual Report 2014.
| recovery | calibrated | loss weight | of total loss from | report |
|---|---|---|---|---|
| Asset classes ratio | rate | (bps) each | class rate (bps) | (bps) |
| Wholesale to bank | 0.99 | 0.874 | 0.090 70.370 | 0.283 |
| Wholesale to customer | 0.6 | 43.562 | 0.408 | 15.512 |
| Home loans | 0.7 | 46.773 | 0.355 | 53.906 |
| Cards | 0.5 | 273.642 | 0.125 | 405.763 |
| Other retail | 0.55 | 73.541 | 0.022 | 85.538 |
4.2 Loan Modeling and Sensitivities
One may model loans within Stress ControllerTM either as individual rated exposures or as diversified pool exposures with a default rate that evolves over time. For public data analysis such as the exercise reported in this paper, we use diversified pool exposures. In separate publications, we have shown how to derive simple but rigorous models of the dynamic behavior of loss rates on pools of homogeneous loans. These may be modeled unconditionally or conditional on macroeconomic variables. In the latter case, the default rate evolves as an auto-correlated time series driven by shocks to macro variables like GDP, interest rates or unemployment. The sensitivities we employ in this case study are sector-specific and asset-class-specific and draw on the estimates we have obtained in a series of past studies of the macroeconomic impact on loan books using data from different banks and a range of public data sources.
5. Modeling Financial Statements
5.1 The Bank’s Financial Statements
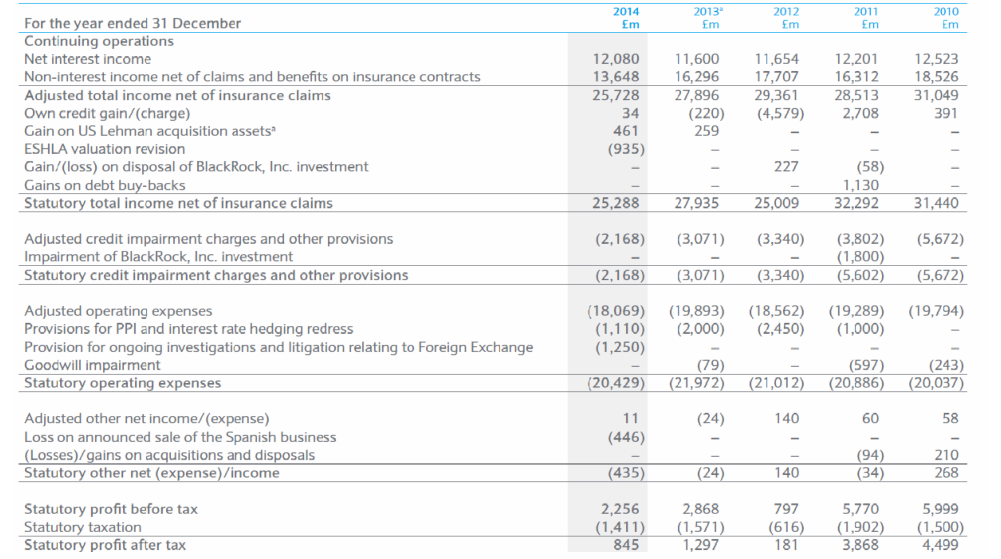
Figure 4: Historical B/S from the Bank’s Annual Report
In Figures 4 and 5, the historical consolidated summary financial statements of the bank are presented for the past 5 years. These historical financial statements are imported into Stress ControllerTM and serve as the starting point for forecasts of future financial statements conditional on macroeconomic scenarios.[1]
5.2 Modeling the Bank’s Balance Sheet
Detailed description of the equations used in modeling the bank’s balance sheet and P&L are provided in the Appendix. Key assumptions of the modeling approach are as follows.
1. We view the bank’s financial statement as balance-sheet driven. Both sides of the balance sheet are assumed to be directly affected by the macro-economy. The asset side is also affected through the impact of macro shocks on provisions and changes in mark-to-market values.
2. Loans and deposits are assumed to be linked to (a) GDP growth in the relevant region, and (b) its own historical trend. The relative importance of (a) and (b) and the sensitivity to macro shocks vary for different loans and deposits. The approach employed in this case study could easily be generalized to include interest rates or other macroeconomic variables such as unemployment rates but we have preferred in this exercise to keep the analysis as simple as possible.
3. Marked-to-market assets and liabilities are assumed to be sensitive to relevant macro indicators, in particular to GDP or national equity indices.
4. Items such as ‘Cash’ and ‘Others Assets/Liabilities/Expenses’ are modeled as moving averages of the previous balances.
5. All Balance Sheet items, except ‘Cash’ and ‘Other Assets/Liabilities’, have been modeled taking into account inflation.
6. Income is modeled based on the forecasted balance-sheet. Both interest and non-interest income are modeled as being affected by the combined changes in loan-type assets and non-loan type assets, but with different weights on different types of assets (e.g. weight of loan-type assets on interest income is 0.8 but on non-interest income is 0.2) and the weights are user-defined parameters. For interest income, the impact from changes of forecasted interest rates is modeled
1The calculations are performed on a quarterly basis so the data is imported after converting the annual reports into quarterly data.
7. The credit impairment charge is calculated as the expected losses of loans and advances to retail and wholesale customers, taking into account the lagged impact of macroeconomic variables on provisions. (Recall that loans are modeled as diversified pool exposures.)
8. We view the operating expenses of the bank as controlled by the management rather than reacting passively to changes in the size of the bank’s balance-sheet. We therefore allow the user to input the forecasted rate of change of operating expenses.
9. To balance the balance sheet at the end of each forecasting, we adjust the gap between forecast ‘Total Assets’ and ‘Total Liabilities and Shareholder Equities’, allowing this gap to be absorbed by multiple items employing user-defined weights. The items adjusted to balance assets and liabilities are referred to as the B/S ‘balancing items’.
10. We model shareholders’ equity changes as influenced by: (i) retained earnings from the forecast Income Statements, (ii) dividend payouts based on user defined ‘dividend payout ratios’ and (iii) reserve and employee share scheme changes which are also user-defined.
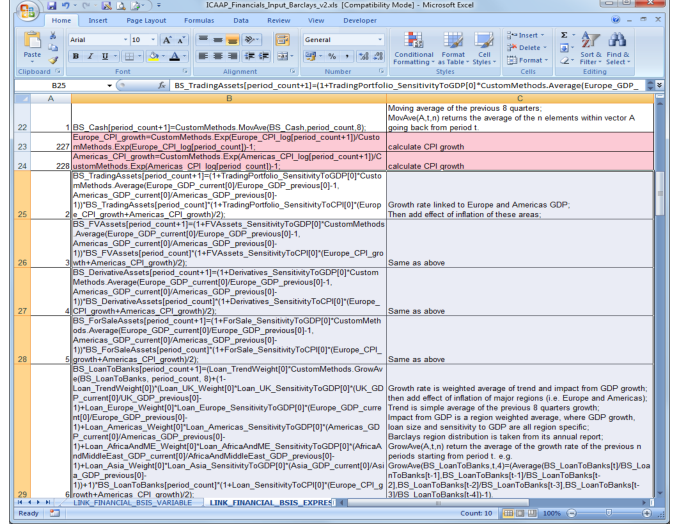
The equations for the financial statements analysis are treated in Stress ControllerTMas part of the data of the model. They are imported from a ‘feeder’ Excel workbook. A screenshot of the equations stored in such a workbook is provided in Figure 6.
To take an example, the item ‘Trading portfolio assets’ is modeled as: BS_TradingAssets[period_count+1]=(1+TradingPortfolio_SensitivityToGDP[0]*CustomMethods.Aver age(Europe_GDP_current[0]/Europe_GDP_previous[0]-1, Americas_GDP_current[0]/Americas_GDP_previous[0]- 1))*BS_TradingAssets[period_count]*(1+TradingPortfolio_SensitivityToCPI[0]*(Europe_CPI_growth +Americas_CPI_growth)/2);
Before the above equation is executed, all the variables employed in the equation must be declared by importing a user workbook containing the definition of each variable. Further details of how the equations are specified and used within Stress ControllerTM are provided in the Appendix.
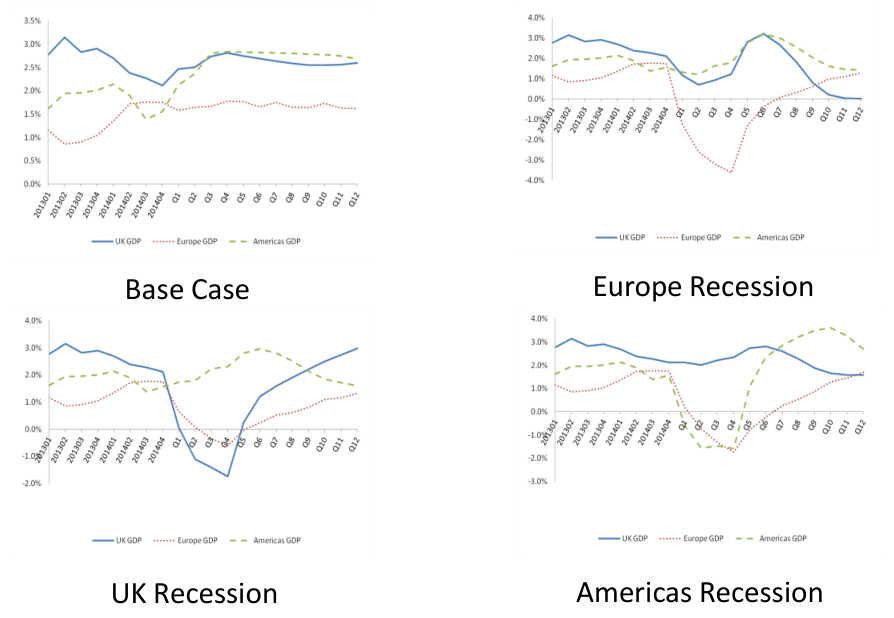
Note: In Figure 7 we plot out, in each scenario, the historical year-on-year GDP growth for the past 8 quarters and the forecasted year-on-year GDP growth for the future 12 quarters.
6. Results
Using the approach described above, we performed an analysis of the impact of several stress scenarios on the bank’s financial statements and key risk indicators. We present below results for (i) a base case (the forecasts by IMF World Economic Outlook), (ii) a European recession, (iii) a UK recession, and (iv) a recession in America.
Figure 7 shows the time paths of real GDP 1-year growth rates for the UK, Europe and America. The time paths are shown for the base case and the three stress cases described above. We display quarterly historical data up to the end of 2015 followed by projections quarter by quarter until the end of 2018. Note that we start the forecast calculations for financial statements in Q1 2015 because the financial statement data available is for the end of 2014.
The recession scenarios assume a sequence of shocks to real GDP in the geographical region in question. In all cases, the shocks are -2% in Q1, -1% in Q2 and -0.5% in Q3, Q4,.., Q12. These shocks sum to a cumulative negative shocks of 8% over 3 years.
As one might expect, the impact of a recession is greatest for the region itself. However, recessions in each region have serious implications for outcomes in other regions. Note that the fact that American and European GDP growth rates are affected by a UK recession does not imply a direct causal relationship. Instead, the implication is that when a recession occurs in the UK, on average one would expect recessions of the magnitude shown in the other regions.
variation of the loans over the forecasted period and (b) the lag effect of GDP shock to the provision of credit loans.
© Copyright Risk Control Limited 2016
Figure 8 shows the path of credit impairment provisions under the four scenarios considered. The impairments are driven by the impact of GDP shocks on the expected losses of the diversified pool exposures included in the software to describe the bank’s loan book. These are broken down by sector, credit quality and geographical region.
As one may observe from Figure 8, impairment provisions are flat in the base case but rise significantly in the three recession scenarios, showing the highest growth in the UK recession scenario. The software models the impairment provision of the stressed scenarios as a function of the relevant factor’s deviation from the base case dynamics (in this study, the GDP’s path under stressed scenarios deviating from the base case result). Therefore one would expect the base case provision dynamics to be flat.
Figure 9 presents a series of plots of key financial indicators under the four scenarios. Capital, measured in different ways, is down in all three recession scenarios. The figures for returns on equity and Risk Weighted Assets shown in Figure 9 again show consistent patterns of decline as the recessions emerge.
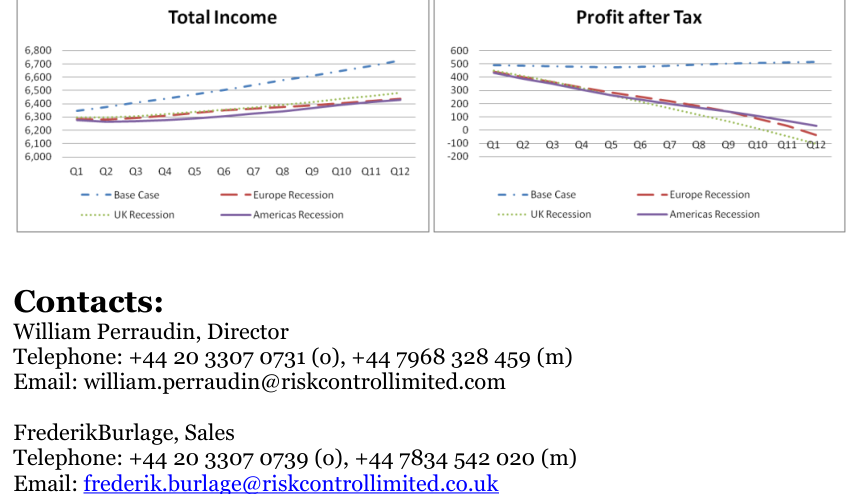
Tables 5 and 6 and Figures 10 and 11 show selected items from the bank’s balance sheet and income statements. Loan and deposit growth are depressed in the recession scenarios. Total income shows much slower growth in the stressed cases and profits are down, showing the combined effect of scenario-based size changes in the interest-bearing assets/liabilities, changes in levels of relevant interest rates and changes in the credit provision charges.
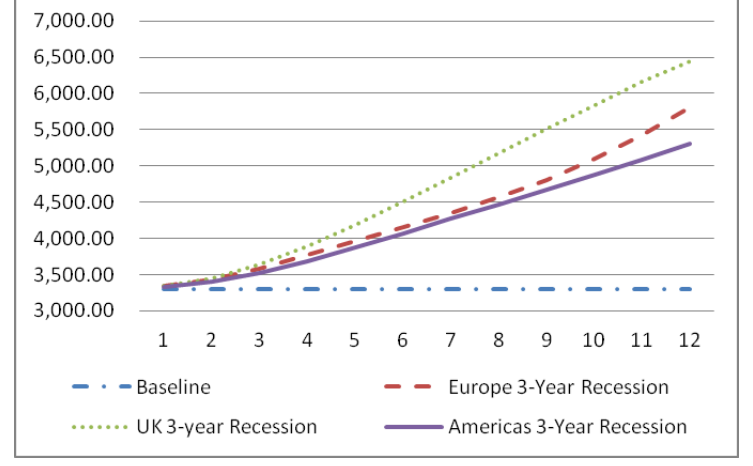
Note: based on the credit risk modeling of a static credit portfolio, we have also taken into account (a) the
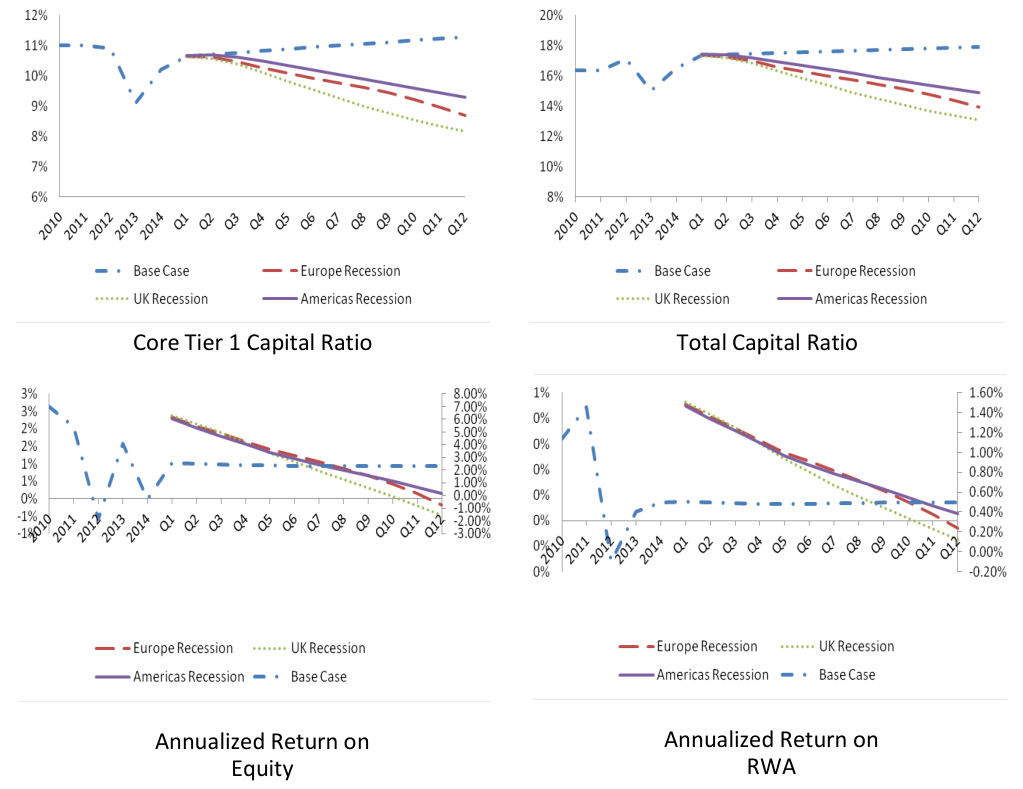
Note: We plot out the KPI measure for the previous 5 years and future 12 forecasted quarters.
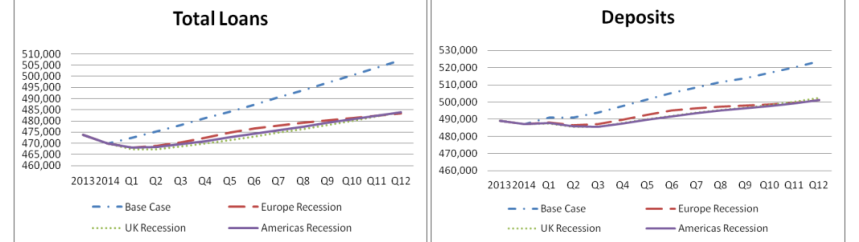
| Cash and Mark-to-Market Assets | 661,062 | 719,897 | 746,773 | 744,312 | 744,592 | 746,705 | 749,912 | 753,469 | 757,533 | 761,716 | 766,210 | 768,990 | 772,336 | 775,929 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Total Loans | 473,659 | 469,878 | 472,398 | 475,267 | 478,193 | 481,175 | 484,223 | 487,359 | 490,610 | 493,876 | 497,156 | 500,526 | 503,949 | 507,387 |
| Other Assets | 208,907 | 168,131 | 197,593 | 194,475 | 192,868 | 191,180 | 188,990 | 187,806 | 187,740 | 188,933 | 191,546 | 190,799 | 190,354 | 190,039 |
| Total Assets | 1,343,628 | 1,357,906 | 1,416,763 | 1,414,053 | 1,415,653 | 1,419,060 | 1,423,125 | 1,428,634 | 1,435,883 | 1,444,525 | 1,454,911 | 1,460,315 | 1,466,638 | 1,473,355 |
| Deposits | 488,972 | 487,271 | 490,824 | 490,933 | 493,736 | 497,579 | 501,482 | 505,127 | 508,529 | 511,492 | 513,977 | 516,887 | 520,261 | 523,738 |
| Mark-to-Market Liabilities | 662,126 | 665,895 | 721,309 | 719,539 | 717,739 | 716,233 | 714,860 | 715,398 | 718,156 | 723,071 | 730,545 | 732,086 | 733,874 | 735,992 |
| Other Liabilities | 128,581 | 138,782 | 137,920 | 136,122 | 135,974 | 136,302 | 137,101 | 137,685 | 138,026 | 138,035 | 137,699 | 137,885 | 138,275 | 138,621 |
| Total Liabilities | 1,279,679 | 1,291,948 | 1,350,053 | 1,346,594 | 1,347,449 | 1,350,115 | 1,353,444 | 1,358,211 | 1,364,712 | 1,372,598 | 1,382,221 | 1,386,858 | 1,392,410 | 1,398,352 |
| Total Equity | 63,949 | 65,958 | 66,710 | 67,459 | 68,204 | 68,945 | 69,681 | 70,423 | 71,172 | 71,927 | 72,691 | 73,458 | 74,228 | 75,004 |
| Total Liabilities and Equity | 1,343,628 | 1,357,906 | 1,416,763 | 1,414,053 | 1,415,653 | 1,419,060 | 1,423,125 | 1,428,634 | 1,435,883 | 1,444,525 | 1,454,911 | 1,460,315 | 1,466,638 | 1,473,355 |
| UK Recession | 2013 | 2014 | Q1 | Q2 | Q3 | Q4 | Q5 | Q6 | Q7 | Q8 | Q9 | Q10 | Q11 | Q12 |
| Cash and Mark-to-Market Assets | 661,062 | 719,897 | 743,859 | 739,871 | 737,452 | 737,729 | 739,291 | 741,124 | 743,276 | 745,563 | 748,249 | 749,240 | 750,870 | 752,766 |
| Total Loans | 473,659 | 469,878 | 467,387 | 467,309 | 468,495 | 469,853 | 471,377 | 473,003 | 474,718 | 476,462 | 478,243 | 480,128 | 482,073 | 483,923 |
| Other Assets | 208,907 | 168,131 | 197,466 | 194,601 | 192,585 | 190,860 | 188,636 | 187,415 | 187,310 | 188,458 | 191,019 | 190,237 | 189,721 | 189,340 |
| Total Assets | 1,343,628 | 1,357,906 | 1,408,712 | 1,401,781 | 1,398,532 | 1,398,442 | 1,399,305 | 1,401,542 | 1,405,303 | 1,410,483 | 1,417,511 | 1,419,605 | 1,422,664 | 1,426,029 |
| Deposits | 488,972 | 487,271 | 487,354 | 485,512 | 485,683 | 487,644 | 489,903 | 492,008 | 493,900 | 495,442 | 496,615 | 498,196 | 500,283 | 502,485 |
| Mark-to-Market Liabilities | 662,126 | 665,895 | 717,138 | 713,102 | 709,773 | 706,764 | 704,030 | 703,139 | 704,316 | 707,650 | 713,599 | 713,754 | 714,225 | 714,930 |
| Other Liabilities | 128,581 | 138,782 | 137,548 | 135,820 | 135,093 | 135,463 | 136,265 | 136,801 | 137,050 | 136,960 | 136,520 | 136,578 | 136,837 | 137,108 |
| Total Liabilities | 1,279,679 | 1,291,948 | 1,342,041 | 1,334,434 | 1,330,549 | 1,329,871 | 1,330,199 | 1,331,948 | 1,335,267 | 1,340,052 | 1,346,734 | 1,348,529 | 1,351,345 | 1,354,522 |
| Total Equity | 63,949 | 65,958 | 66,671 | 67,347 | 67,983 | 68,571 | 69,106 | 69,595 | 70,037 | 70,431 | 70,778 | 71,076 | 71,319 | 71,507 |
| Total Liabilities and Equity | 1,343,628 | 1,357,906 | 1,408,712 | 1,401,781 | 1,398,532 | 1,398,442 | 1,399,305 | 1,401,542 | 1,405,303 | 1,410,483 | 1,417,511 | 1,419,605 | 1,422,664 | 1,426,029 |
| Total | Income | 27,935 | 25,288 | 6,347 | 6,377 | 6,407 | 6,440 | 6,472 | 6,505 | 6,541 | 6,577 | 6,612 | 6,650 | 6,687 | 6,725 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Credit | Impairment Charge | -3,071 | -2,168 | -544 | -547 | -550 | -553 | -556 | -559 | -562 | -565 | -568 | -572 | -575 | -579 |
| Total | Expenses | -21,996 | -20,864 | -5,190 | -5,222 | -5,255 | -5,289 | -5,325 | -5,348 | -5,372 | -5,395 | -5,418 | -5,447 | -5,475 | -5,504 |
| Profit | before Tax | 2,868 | 2,256 | 612 | 608 | 602 | 598 | 591 | 598 | 607 | 617 | 626 | 632 | 637 | 643 |
| Profit | after Tax | 1,297 | 845 | 490 | 486 | 482 | 478 | 473 | 479 | 486 | 493 | 501 | 505 | 509 | 514 |
| 2013 | 2014 | ||||||||||||||
| UK Recession | annual | annual | Q1 | Q2 | Q3 | Q4 | Q5 | Q6 | Q7 | Q8 | Q9 | Q10 | Q11 | Q12 | |
| Total | Income | 27,935 | 25,288 | 6,297 | 6,296 | 6,307 | 6,321 | 6,337 | 6,354 | 6,373 | 6,392 | 6,413 | 6,436 | 6,460 | 6,483 |
| Credit | Impairment Charge | -3,071 | -2,168 | -545 | -562 | -592 | -635 | -685 | -740 | -797 | -856 | -915 | -973 | -1,030 | -1,083 |
| Total | Expenses | -21,996 | -20,864 | -5,190 | -5,222 | -5,255 | -5,289 | -5,325 | -5,348 | -5,372 | -5,395 | -5,418 | -5,447 | -5,475 | -5,504 |
| Profit | before Tax | 2,868 | 2,256 | 561 | 512 | 460 | 396 | 327 | 266 | 205 | 142 | 80 | 16 | -45 | -103 |
| Profit | after Tax | 1,297 | 845 | 449 | 409 | 368 | 317 | 262 | 213 | 164 | 113 | 64 | 13 | -45 | -103 |
Appendix
Section A.1: Introduction This Appendix provides information on how one may write a financial statement model for a bank for use in Stress ControllerTM. We present an illustrative model for a particular bank, namely the Barclays Group PLC. TheAppendix is organized as follows.In section A.2, we give a specific example of how to declare all the variables that will be employed in an example equation. In section A.3, we explain how each balance sheet (B/S) item within the ‘Assets’ and ‘Liabilities’ categories are forecast. In section A.4, we illustrate the forecasting of the income statement (I/S) and in section A.5, the forecasting of B/S items within the ‘Shareholders’ equity’ category. Finally, in A.6, we show how one balance the B/S by recalculating the ‘balancing items’.
Section A.2: Variables Declaration Before the equations of financial statements modeling can be executed, variables employed in the equations must be loaded into the database by importing a user workbook in which the definition of each variable is specified. The definition of each variable is stored in a string consisting of four sections. Each section must adhere to certain rules. The four sections are:
(1) Major category:
(2) Name of the variable
(3) Minor category
(4) Indicators for database management
The sections are separated by hyphens. (Note that the hyphen symbol is therefore a reserved character that should not be used for other purposes.) To illustrate the declaration of variables, consider the B/S variable: ‘Trading portfolio assets’. This is modeled as: BS_TradingAssets[t+1]=(1+TradingPortfolio_SensitivityToGDP[0]* CustomMethods.Average(Europe_GDP[t+1]/Europe_GDP[t]-1, Americas_GDP[t+1]/Americas_GDP[t]- 1))*BS_TradingAssets[t]*(1+TradingPortfolio_SensitivityToCPI[0]*(Europe_ CPI_growth+Americas_CPI_growth)/2); For the above equation to be valid, the user must declare the variables it includes as follow:
(1) BS_TradingAssets Group-Trading portfolio assets-BS-1-1-3-0
• ‘Group’: this indicates the variable is group level data;
• ‘BS’: this indicates the variable is from the B/S;
• ‘Trading portfolio assets’: this is the name of the variable as it appears in the B/S;
• ‘1-1-3-0’: this code specifies that the variable (i) will be saved in the database, (ii) will be displayed in the interface, (iii) will have the relative position 3 in the interface and (iv) will not be highlighted.
The time series indicator [t+1] implies that this variable has a time dimension, and [t+1] represents the period to be calculated and [t] the first lag.
(2) TradingPortfolio_SensitivityToGDP Parameter-Group TradingPortfolio_SensitivityToGDP- SCALAR-1-1-1-0
‘Parameter’: this is a user-defined parameter that will be imported from a user-supplied workbook; ‘SCALAR’: this indicates the parameter is scalar valued (and has no time dimension); ‘Group TradingPortfolio’: this is the name of the parameter in the user-supplied workbook; The time series indicator [0] implies that this variable has no time-series dimension.
(3) Europe_GDP Macro-Europe:Real GDP (2005=100)-MACRORESULT-1-1-1-0
‘Macro’: this indicates the variable is a variable supplied by the macro model; ‘MACRORESULT’: this item should be fetched from the macro results within Stress ControllerTM; ‘Europe:Real GDP (2005=100)’: this is the name of the macro variable;
The time series indicator [t+1] implies that this variable has time dimension, and [t+1] represents the period to be calculated and [t] its first lag.
Section A.3: B/S-Assets and Liabilities In this section, we explain the modeling of each B/S item. Assets
1. Cash, balance at central banks and items in the course of collection
This item is estimated as the average of the previous 8 quarters.Note that this item may be adjusted in the rebalancing of the balance sheet. BS_Cash[t+1]=CustomMethods.MovAve(BS_Cash,t,8);
2. Trading portfolio assets
The growth rate of this item is estimated as being sensitive to the GDP growth rates of Europe and Americas, where sensitivity is a user-defined parameter. Modeling has taken into account inflation changes. Please note that this item might be recalculated for rebalancing the balance sheet.
3. BS_TradingAssets[period_count+1]=(1+TradingPortfolio_SensitivityToGDP[0]*CustomMethods.Aver age(Europe_GDP_current[0]/Europe_GDP_previous[0]-1, Americas_GDP_current[0]/Americas_GDP_previous[0]- 1))*BS_TradingAssets[period_count]*(1+TradingPortfolio_SensitivityToCPI[0]*(Europe_CPI_growth +Americas_CPI_growth)/2);Financial assets designated at fair value
Same as above, while sensitivity set as a separate parameter. Modeling has taken into account the inflation changes. BS_FVAssets[t+1]=(1+FVAssets_SensitivityToGDP[0]*CustomMethods.Average(Europe_GDP[t+1]/E urope_GDP[t]-1, Americas_GDP[t+1]/Americas_GDP[t]-1))*BS_FVAssets[t] *(1+FVAssets_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
4. Derivative financial instruments assets
As above except that the sensitivity is set as a separate parameter. Modeling has taken into account inflation. BS_DerivativeAssets[t+1]=(1+Derivatives_SensitivityToGDP[0]*CustomMethods.Average(Europe_GD P[t+1]/Europe_GDP[t]-1, Americas_GDP[t+1]/Americas_GDP[t]-1))*BS_DerivativeAssets[t] *(1+Derivatives_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
5. Available for sale financial investments
Same as above except that the sensitivity set as a separate parameter. Modeling has taken into account inflation. BS_ForSaleAssets[t+1]=(1+ForSale_SensitivityToGDP[0]*CustomMethods.Average(Europe_GDP[t+1] /Europe_GDP[t]-1, Americas_GDP[t+1]/Americas_GDP[t]-1))*BS_ForSaleAssets[t] *(1+ForSale_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
6. Gross loans and advances to banks
The growth rate of this item is estimated as the weighted average of (1) impact from trend and (2) GDP growth. The weights are user-defined parameters and impact from trend is calculated as the average growth rate of previous 8 quarters. The GDP growth is a region-weighted average where the weights are taken from the bank’s annual report but can be user-defined. Modeling has taken into account inflation. BS_LoanToBanks[t+1]=(Loan_TrendWeight[0]*CustomMethods.GrowAve(BS_LoanToBanks, t, 8)+(1- Loan_TrendWeight[0])*(Loan_UK_Weight[0]*Loan_UK_SensitivityToGDP[0]*(UK_GDP[t+1]/UK_ GDP[t]- 1)+Loan_Europe_Weight[0]*Loan_Europe_SensitivityToGDP[0]*(Europe_GDP[t+1]/Europe_GDP[t] - 1)+Loan_Americas_Weight[0]*Loan_Americas_SensitivityToGDP[0]*(Americas_GDP[t+1]/Americas _GDP[t]- 1)+Loan_AfricaAndME_Weight[0]*Loan_AfricaAndME_SensitivityToGDP[0]*(AfricaAndMiddleEast _GDP[t+1]/AfricaAndMiddleEast_GDP[t]- 1)+Loan_Asia_Weight[0]*Loan_Asia_SensitivityToGDP[0]*(Asia_GDP[t+1]/Asia_GDP[t]- 1))+1)*BS_LoanToBanks[t] *(1+Loan_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
7. Less: bank allowance for impairment
This item should be calculated as the balance from last period plus a fraction of the total credit provision estimated for this period minus the write-off occurring in this period. The total credit provision is estimated based on the provision calculation results from the risk modeling section of Stress ControllerTM, taking into account (1) the lagged effects of macro-economic shock on the credit quality of loans and (2) changes in the forecast volume of loans.The relative impact and write-offsare user-defined input parameters. BS_Allowance_Banks[period_count+1]=BS_Allowance_Banks[period_count]+Ave_CreditPoolProvisi on_current*BS_LAToBanks_Scaling/4.0*Credit_Provision_FractionOfBank[period_count+1]- Loan_WriteOff_banks[period_count+1]*(Ave_CreditPoolProvision_current/Ave_CreditPoolProvision _previous);
8. Loans and advances to banks
This is a dependent item. BS_NetLoanToBanks[t+1]=BS_LoanToBanks[t+1]-BS_Allowance_Banks[t+1];
9. Gross loans and advances to customers
The treatment is similar to that of Gross loans and advances to banks. Modeling allows for inflation changes. BS_LoanToCustomers[t+1]=(Loan_TrendWeight[0]*CustomMethods.GrowAve(BS_LoanToCustomer s, t, 8)+(1- Loan_TrendWeight[0])*(Loan_UK_Weight[0]*Loan_UK_SensitivityToGDP[0]*(UK_GDP[t+1]/UK_ GDP[t]- 1)+Loan_Europe_Weight[0]*Loan_Europe_SensitivityToGDP[0]*(Europe_GDP[t+1]/Europe_GDP[t] - 1)+Loan_Americas_Weight[0]*Loan_Americas_SensitivityToGDP[0]*(Americas_GDP[t+1]/Americas _GDP[t]- 1)+Loan_AfricaAndME_Weight[0]*Loan_AfricaAndME_SensitivityToGDP[0]*(AfricaAndMiddleEast _GDP[t+1]/AfricaAndMiddleEast_GDP[t]- 1)+Loan_Asia_Weight[0]*Loan_Asia_SensitivityToGDP[0]*(Asia_GDP[t+1]/Asia_GDP[t]- 1))+1)*BS_LoanToCustomers[t] *(1+Loan_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
10. Less: customers allowance for impairment
The treatment is similar to that of item 7 ‘Less: bank allowance for impairment’. BS_Allowance_Customers[period_count+1]=BS_Allowance_Customers[period_count]+BS_LAToCus tomers_Scaling*Ave_CreditPoolProvision_current/4.0*(1- Credit_Provision_FractionOfBank[period_count+1])- Loan_WriteOff_customers[period_count+1]*(Ave_CreditPoolProvision_current/Ave_CreditPoolProvi sion_previous);
11. Loans and advances to customers
This is a dependent item. BS_NetLoanToCustomers[t+1]=BS_LoanToCustomers[t+1]-BS_Allowance_Customers[t+1];
12. Reverse repurchase agreements and other similar secured lending
This item is estimated as the average of the previous 8 quarters. Modeling allows for the effect of inflation. BS_RepoAssets[t+1]=CustomMethods.MovAve(BS_RepoAssets,t,8) *(1+Other_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
13. Other assets
This item is estimated as the average of the previous 8 quarters. Please be noted that this item might be recalculated for rebalancing the balance sheet. BS_OtherAssets[t+1]=CustomMethods.MovAve(BS_OtherAssets,t,8);
14. Total assets
This is a dependent item. BS_TotalAssets[t+1]=BS_Cash[t+1]+BS_TradingAssets[t+1]+BS_FVAssets[t+1]+BS_DerivativeAssets [t+1]+BS_ForSaleAssets[t+1]+BS_NetLoanToBanks[t+1]+BS_NetLoanToCustomers[t+1]+BS_RepoAs sets[t+1]+BS_OtherAssets[t+1];
Liabilities
15. Deposits and items in the course of collection due to banks
This item is estimated as the average of the previous 8 quarters. Modeling has taken into account the inflation changes. Note that this item may be recalculated when the balance sheet is rebalanced. BS_DueToBanks[t+1]=CustomMethods.MovAve(BS_DueToBanks,t,8) *(1+Deposit_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
16. Customer accounts
This item is calculated similarly to the gross loans and advances items. It shares the same region weights that are used in estimating ‘Gross loans and advances to banks’ and ‘Gross loans and advances to customers’. Modeling allows for the impact of inflation. Note that this item may be recalculated when the balance sheet is rebalanced. BS_Deposits[t+1]=(Deposit_TrendWeight[0]*CustomMethods.GrowAve(BS_Deposits, t, 8)+(1- Deposit_TrendWeight[0])*(Loan_UK_Weight[0]*Deposit_UK_SensitivityToGDP[0]*(UK_GDP[t+1]/ UK_GDP[t]- 1)+Loan_Europe_Weight[0]*Deposit_Europe_SensitivityToGDP[0]*(Europe_GDP[t+1]/Europe_GD P[t]- 1)+Loan_Americas_Weight[0]*Deposit_Americas_SensitivityToGDP[0]*(Americas_GDP[t+1]/Americ as_GDP[t]- 1)+Loan_AfricaAndME_Weight[0]*Deposit_AfricaAndME_SensitivityToGDP[0]*(AfricaAndMiddleEa st_GDP[t+1]/AfricaAndMiddleEast_GDP[t]- 1)+Loan_Asia_Weight[0]*Deposit_Asia_SensitivityToGDP[0]*(Asia_GDP[t+1]/Asia_GDP[t]- 1))+1)*BS_Deposits[t] *(1+Deposit_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
17. Repurchase agreements and other similar secured borrowing
This item is estimated as the average of the previous 8 quarters. Modeling allows for the impact of inflation. BS_RepoLiabilities[t+1]=CustomMethods.MovAve(BS_RepoLiabilities,t,8) *(1+Other_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
18. Trading portfolio liabilities
The growth rate of this item is estimated in the same way as that of item ‘Trading portfolio assets’: linked to average GDP growth in Europe and Americas. It also shares the parameters of sensitivity to GDP as that used in estimating item ‘Trading portfolio assets’. Modeling allows for the impact of inflation. BS_TradingLiabilities[t+1]=(1+TradingPortfolio_SensitivityToGDP[0]*CustomMethods.Average(Euro pe_GDP[t+1]/Europe_GDP[t]-1, Americas_GDP[t+1]/Americas_GDP[t]-1))*BS_TradingLiabilities[t] *(1+TradingPortfolio_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
19. Financial liabilities designated at fair value
The growth rate of this item is estimated in the same way as that of item ‘Financial assets designated at fair value’ in that it is linked to average GDP growth in Europe and Americas. It also shares the GDP sensitivity parameters used in estimating item‘Financial assets designated at fair value’. Modeling allows for the impact of inflation. BS_FVLiabilities[t+1]=(1+FVAssets_SensitivityToGDP[0]*CustomMethods.Average(Europe_GDP[t+1 ]/Europe_GDP[t]-1, Americas_GDP[t+1]/Americas_GDP[t]-1))*BS_FVLiabilities[t] *(1+FVAssets_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
20. Derivative financial instruments liabilities
The growth rate of this item is estimated in the same way as that of item ‘Derivative financial instruments assets’: linked to average GDP growth in Europe and Americas. It also share the parameters of sensitivity to GDP as that used in estimating item ‘Derivative financial instruments assets’. Modeling has taken into account the inflation changes. BS_DerivativeLiabilities[t+1]=(1+Derivatives_SensitivityToGDP[0]*CustomMethods.Average(Europe _GDP[t+1]/Europe_GDP[t]-1, Americas_GDP[t+1]/Americas_GDP[t]-1))*BS_DerivativeLiabilities[t] *(1+Other_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
21. Debt securities in issue
This item is estimated as the average of the previous 8 quarters. Please be noted that this item might be recalculated for rebalancing the balance sheet.Modeling has taken into account the inflation changes.
BS_DebtIssue[t+1]=CustomMethods.MovAve(BS_DebtIssue,t,8) *(1+Other_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
22. Subordinated liabilities
This item is estimated as the average of the previous 8 quarters. Modeling has taken into account the inflation changes. BS_SubDebt[t+1]=CustomMethods.MovAve(BS_SubDebt,t,8) *(1+Other_SensitivityToCPI[0]*(Europe_CPI_growth+Americas_CPI_growth)/2);
23. Other liabilities
This item is estimated as the average of the previous 8 quarters. Please be noted that this item might be recalculated for rebalancing the balance sheet. BS_OtherLiabilities[t+1]=CustomMethods.MovAve(BS_OtherLiabilities,t,8);
24. Total liabilities
This is a dependent item. BS_TotalLiabilities[t+1]=BS_DueToBanks[t+1]+BS_Deposits[t+1]+BS_RepoLiabilities[t+1]+BS_Trad ingLiabilities[t+1]+BS_FVLiabilities[t+1]+BS_DerivativeLiabilities[t+1]+BS_DebtIssue[t+1]+BS_Sub Debt[t+1]+BS_OtherLiabilities[t+1];
Section A.4: I/S Continuing operations
25. Net interest income
The growth rate of this item linked to the growth rate of both loan-type and non-loan-type assets. We also model the impact from the changes in the forecasted interest rates.
26. IS_IntIncome[period_count+1]=IS_IntIncome[period_count]*(IntIncome_Weight_On_Loan[0]*Loa nAsset_growth+IntIncome_Weight_On_NonLoan[0]*NonLoanAsset_growth)*(1+IntIncome_Sensiti vity_IntRate[0]*Average_Int_Change);Noninterest income net of claims and benefits on insurance contracts
The growth rate of this item is linked to both loan-type and non-loan type assets forecasted in B/S. IS_NonIntIncome[period_count+1]=IS_NonIntIncome[period_count]*(NonIntIncome_Weight_On_ Loan[0]*LoanAsset_growth+NonIntIncome_Weight_On_NonLoan[0]*NonLoanAsset_growth);
27. Total income net of insurance claims
This is a dependent item. IS_TotalIncome[t+1]=IS_IntIncome[t+1]+IS_NonIntIncome[t+1];
28. Credit impairment charges and other provisions
This item is estimated based on the provision calculation results from the risk modeling section of Stress ControllerTM, taking into account (1) the lagged effect of macro-economic shocks on the credit quality of loans and (2) forecast changes in the volume of loans. IS_CreditCharges[0][period_count+1]=IS_CreditCharges[0][hist_len- 1]/Credit_Pool_Provision[0][hist_len-1]*Ave_CreditPoolProvision_current*BS_LATotal_Scaling;
29. Impairment of investment in BlackRock, Inc.
This item reports the extraordinary impairment associated with the Blackrock holding. IS_ExtroImpairment[t+1]=Extrodinary_Impairment[t+1];
30. Operating expenses
The growth rate of this item is user-supplied. IS_OPExpenses[t+1]=IS_OPExpenses[t]*(1+OperationExpense_growth[t+1]);
31. Other
This item is estimated as the average of the previous 8 quarters. IS_OtherExpenses[t+1]=CustomMethods.MovAve(IS_OtherExpenses,t,8);
32. Profit before tax
This is a dependent item.
IS_PBT[t+1]=IS_TotalIncome[t+1]+IS_CreditCharges[t+1]+IS_ExtroImpairment[t+1]+IS_OPExpens es[t+1]+IS_OtherExpenses[t+1];
33. Taxation
The average tax rate is a user-supplied parameter. The calculation of this item is then the bigger of zero and the user-supplied tax rate. IS_Tax[t+1]=-1*CustomMethods.Max(0,1*Tax_AverageRate[0]*IS_PBT[t+1]);
34. Profit after tax from continuing operations
This is a dependent item. IS_PAT_ConOperation[t+1]=IS_PBT[t+1]+IS_Tax[t+1];
35. Profit for the year from discontinued operations, including gain on disposal
This item will be user-defined. IS_DisconOperation[t+1]=Discontinued_GainLoss[t+1];
36. Profit after tax
This is a dependent item. IS_PAT[t+1]=IS_PAT_ConOperation[t+1]-IS_DisconOperation[t+1];
37. Profit attributable to equity holders of the Parent
This item is calculated using the user-supplied profit attribution ratio. IS_ProfitToEq[t+1]=IS_PAT[t+1]*Profit_Attributable_Ratio[t+1];
38. Profit attributable to noncontrolling interests
This is a dependent item. IS_ProfitToMI[t+1]=IS_PAT[t+1]-IS_ProfitToEq[t+1];
Section A.5: B/S Shareholders equity
39. Shareholders equity excluding non-controlling interests
This item is estimated as balance from last period plus any capital injection, which is a user-defined parameter in this case, attribution from profit of this period which has been calculated in the previous steps, dividend payout, reserve changes and employee share scheme changes. BS_Equity_Control[period_count+1]=BS_Equity_Control[period_count]+Capital_Injection[period_c ount+1]+IS_ProfitToEq[period_count+1]*(1- Dividend_Payout_Ratio[period_count+1])+Reserve_Control_Change[period_count+1]+Employee_S hare_Schemes[period_count+1];
40. Noncontrolling interests
Similar as the above item, the estimate of this items equals the balance from last period plus the contribution from profit of this period and other changes. BS_Equity_NoControl[period_count+1]=BS_Equity_NoControl[period_count]+IS_ProfitToMI[perio d_count+1]+MI_Equity_Change[period_count+1];
41. Total shareholders equity
This is a dependent item. BS_TotalEquity[t+1]=BS_Equity_Control[t+1]+BS_Equity_NoControl[t+1];
42. Total liabilities and shareholders equity
This is a dependent item. BS_TotalLiaAndEquity[t+1]=BS_TotalLiabilities[t+1]+BS_TotalEquity[t+1];
43. Cash, balance at central banks and items in the course of collection
Dividend is assumed to be cash dividend so deduction is modeled. BS_Cash[period_count+1]=BS_Cash[period_count+1]- IS_ProfitToEq[period_count+1]*Dividend_Payout_Ratio[period_count+1];
44. Recalculate ‘Total Assets’, ‘Total Liabilites’ and ‘Total Liabilities and Shareholder Equities’ before rebalancing calculation
Section A.6: B/S Balancing items The ‘balancing items’ are chosen by the user to absorb the gap between total assets and total liabilities and equity generated during the item-by-item forecasting. They are re-calculated based on the results completed after Sections II to IV.
45. Cash, balance at central banks and items in the course of collection
Here, we adopt the ‘one-side’ absorbing approach, under which the ‘balancing items’ within the assets category are only updated if total liabilities and equities is higher than he total assets in the period in question. If so, a user-supplied absorbing ratio is employed. BS_Cash[t+1]=BS_Cash[t+1]+CustomMethods.Max(0,BS_TotalLiaAndEquity[t+1]- BS_TotalAssets[t+1])*GapAbsorb_Asset_Cash[0];
46. Trading portfolio assets
As above. BS_TradingAssets[t+1]=BS_TradingAssets[t+1]+CustomMethods.Max(0,BS_TotalLiaAndEquity[t+1]- BS_TotalAssets[t+1])*GapAbsorb_Asset_TradingPortfolio[0];
47. Other assets
As above. BS_OtherAssets[t+1]=BS_OtherAssets[t+1]+CustomMethods.Max(0,BS_TotalLiaAndEquity[t+1]- BS_TotalAssets[t+1])*GapAbsorb_Asset_Other[0];
48. Deposits and items in the course of collection due to banks
Similar to assets ‘balancing items’, the ‘balancing items’ within the liabilities category are only updated if total assets exceed total liabilities and equities in the period in question. If so, a user-supplied absorbing ratio is employed. BS_DueToBanks[t+1]=BS_DueToBanks[t+1]+CustomMethods.Max(0,BS_TotalAssets[t+1]- BS_TotalLiaAndEquity[t+1])*GapAbsorb_Liability_DueToBanks[0];
49. Customer accounts
As above BS_Deposits[t+1]=BS_Deposits[t+1]+CustomMethods.Max(0,BS_TotalAssets[t+1]- BS_TotalLiaAndEquity[t+1])*GapAbsorb_Liability_CustomerAccount[0];
50. Debt securities in issue
As above BS_DebtIssue[t+1]=BS_DebtIssue[t+1]+CustomMethods.Max(0,BS_TotalAssets[t+1]- BS_TotalLiaAndEquity[t+1])*GapAbsorb_Liability_DebtIssue[0];
51. Other liabilities
As above BS_OtherLiabilities[t+1]=BS_OtherLiabilities[t+1]+CustomMethods.Max(0,BS_TotalAssets[t+1]- BS_TotalLiaAndEquity[t+1])*GapAbsorb_Liability_Other[0];
52. Total assets
This is a dependent item. BS_TotalAssets[t+1]=BS_Cash[t+1]+BS_TradingAssets[t+1]+BS_FVAssets[t+1]+BS_DerivativeAssets [t+1]+BS_ForSaleAssets[t+1]+BS_NetLoanToBanks[t+1]+BS_NetLoanToCustomers[t+1]+BS_RepoAs sets[t+1]+BS_OtherAssets[t+1];
53. Total liabilities
This is a dependent item. BS_TotalLiabilities[t+1]=BS_DueToBanks[t+1]+BS_DueToBanks[t+1]+BS_Deposits[t+1]+BS_RepoLi abilities[t+1]+BS_TradingLiabilities[t+1]+BS_FVLiabilities[t+1]+BS_DerivativeLiabilities[t+1]+BS_D ebtIssue[t+1]+BS_SubDebt[t+1]+BS_OtherLiabilities[t+1];
54. Total liabilities and shareholders’ equity
This is a dependent item. BS_TotalLiaAndEquity[t+1]=BS_TotalLiabilities[t+1]+BS_TotalEquity[t+1];